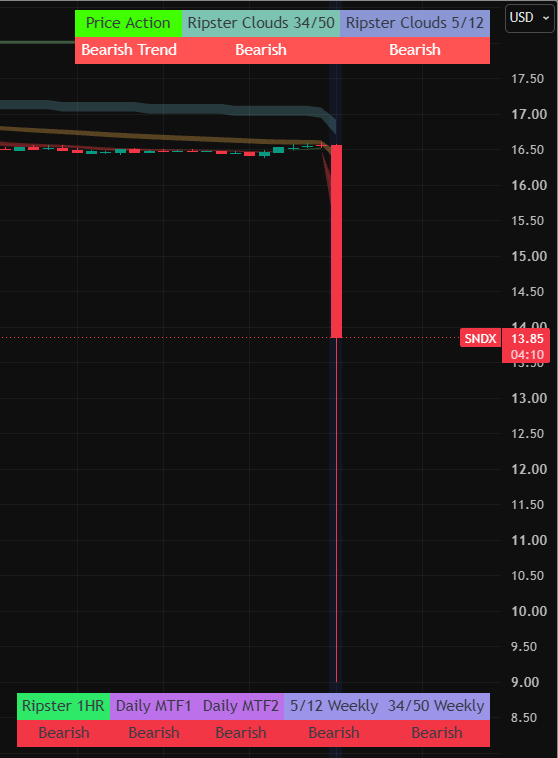
BREAKING: Syndax Pharmaceuticals $SNDX reports a Phase 2 trial failure for axatilimab in idiopathic pulmonary fibrosis (IPF).
The MAXPIRe trial failed to meet its primary endpoint for slowing lung-function decline, and Syndax will not pursue further development in IPF.
The setback does not affect ongoing cGVHD trials, with results expected later in 2026 and early 2028.
Q2 was an exceptional quarter for @SoFi and a testament to the incredible work of our team. 19th Consecutive quarter of the rule of 40 at 70 with 40% revenue growth and 30% EBITDA margin. SoFi Plus driving an inflection point in increased products per member.
We delivered record adjusted net revenue of $1.2 billion, record adjusted EBITDA of $358 million, welcomed 1.1 million new members and added a record 2.2 million new products - all while continuing to invest in innovation across our business.
These results show the durability of our growth, the strength of our everything app.
Thank you to our members and clients for trusting us to help you get your money right!
https://t.co/j1ZcHE31FT
People keep confusing a bubble with “stocks go up and get overvalued”. A bubble is when when a prevailing trend and a prevailing misconception about that trend interact reflexively, each reinforcing the other until the gap between perception and reality becomes unsustainable.
A bubble is not when everyone realizes that right now every iota of AI demand eventually, at some point upstream, must move through memory OEMs. Nor is it when estimates continue rising because things are better than expected. And it’s not just when stocks trade expensive to historical valuations.
The reason behind the moves in the AI infrastructure layer so far have been simply that we don’t have enough. They’ve been driven by the fundamental reality more than the perception of the future. It’s why the bulk of the most bullish parts of this cycle have been lumpy and centered around earnings season when companies uniformly come out and confirm there’s still not enough. In the bubble, the reality is driven by the market - not the other way around.
Everyone keeps saying “people are gonna freak out if it’s not a bubble!”. I think that’s silly, we have a transformative new technology that needs crazy capital to fuel it coming to fruition, that has and always will result in a bubble as long as we have financial markets.
But if you want to call the top in a bubble, you need a much stronger view on what the misconception is and what negative catalyst forces broad perception to align with realizing it than you do on valuation.
$HIMS launched Labs AI which is its first AI care agent for personalized health insights and nuanced health questions.
The company says Labs AI is built with guardrails and uses a custom AI system to support Hims & Hers care platform.
$AMD CEO ON ADDITIONAL MULTI-GIGAWATT AI OPPORTUNITIES
“A growing number of new customers [are] engaging on large-scale deployments, including additional multi-gigawatt opportunities... The largest deployments are for inference.”
“We have strong and increasing confidence in our ability to deliver tens of billions of dollars in annual data center AI revenue in 2027 and to exceed our long-term growth target of greater than 80% in the coming years.”
$AMD data center business has compounded into a ~$23B run-rate engine.
With OpenAI and $META each committing 6 GW of Instinct deployments, AMD now has 12 GW tied to major AI customers as it pushes to become the real second source in AI compute.
ANTHROPIC COMMITS TO SPENDING $200B ON GOOGLE CLOUD AND CHIPS OVER THE NEXT 5 YEAR — THE INFORMATION
Google $GOOGL is now the most valuable company on Planet Earth, overtaking $NVDA Nvidia.
PayPal $PYPL : The Market Is Missing The Setup
PayPal Holdings, Inc $PYPL . has quietly turned into one of those stocks the market no longer wants to think about. And in my experience, that’s usually where things start to get interesting.
This is still a company operating across 200+ markets, with roughly 450 million active accounts and nearly $2 trillion in annual payment volume. Those are not the metrics of a broken business. Yet the stock trades like one.
So the real question isn’t what PayPal is, but why the market has decided it no longer matters.
I think that’s where the opportunity lies.
A Business The Market Has Already Written Off
Let’s call it what it is: sentiment around PayPal has collapsed.
Since its separation from eBay, the company went from being a high-multiple fintech compounder to what the market now treats as a low-growth, commoditized payments platform. Competition intensified, growth slowed, and the narrative shifted from “category leader” to “just another wallet.”
But here’s what doesn’t add up to me.
Despite all the negativity, PayPal is still growing. Not hyper-growth, but stable, mid-single to low-double-digit growth across key metrics. And more importantly, it’s still generating significant cash flow with a massive installed user base.
Markets don’t usually price businesses like this at under 9x forward earnings unless they believe something structurally broken is happening.
I don’t see that here.
The Quarter Everyone Is Complaining About… Was Actually Solid
Let’s go straight to the numbers, because that’s where the disconnect becomes obvious.
PayPal reported Q1 2026 results that beat expectations on both the top and bottom line:
🔹Revenue came in at $8.4 billion, up 7% YoY
🔹Adjusted EPS was $1.34, ahead of the $1.27 consensus
🔹Total Payment Volume (TPV) grew 11% YoY to $460+ billion
Now step back for a second.
This is a company the market is treating like it’s stagnating, yet it’s still growing double digits on volume and mid-single digits on revenue at massive scale.
That’s not a decline story. That’s a mature platform with operating leverage.
And yet, the stock sold off.
Why?
Guidance, Not Fundamentals, Is Driving The Reaction
The real issue wasn’t the quarter. It was the forward outlook.
Management guided for a mid-single-digit EPS decline in Q2 and, more importantly, did not raise full-year guidance despite the Q1 beat.
That’s what the Street didn’t like.
But here’s how I interpret it: this looks more like conservative positioning than fundamental deterioration.
Companies that are undergoing internal restructuring and cost realignment tend to guide cautiously. PayPal is doing both right now.
So instead of asking, “Why didn’t they raise guidance?”, I think the better question is:
What happens if they eventually do?
The Quiet Transformation Underway
One of the more underappreciated developments here is the internal restructuring.
PayPal is reorganizing into three core segments:
🔹Checkout Solutions & Core PayPal
🔹Consumer Financial Services & Venmo
🔹Payment Services & Crypto
At first glance, this looks like corporate reshuffling. But structurally, it matters.
This kind of segmentation typically does two things:
🔹Improves accountability and capital allocation
🔹Makes individual business units easier to evaluate (and potentially monetize)
And yes, that includes the possibility of spinning off or selling assets like Venmo.
The market isn’t pricing in any of that optionality right now.
Cost Discipline + AI = Margin Expansion Story
Another piece that’s getting overlooked is the cost side.
Management is targeting ~$1.5 billion in run-rate savings over the next 2–3 years, driven by operational efficiencies and AI integration.
That’s not trivial.
For a company already generating billions in operating income, even modest margin expansion can materially impact earnings.
This is how mature platforms re-accelerate EPS growth without needing explosive revenue growth.
It’s not flashy but it works.
The Growth Drivers Are Still There (Just Not Hyped)
If you strip away the noise, some key growth engines are still performing:
🔹Branded checkout remains resilient
🔹Venmo monetization is improving
🔹Buy Now, Pay Later (BNPL) volume surged ~20%
These are not legacy segments in decline. These are still scaling businesses.
The issue is that none of them individually feel like a “breakout narrative” right now.
And markets tend to ignore companies that don’t have a clean, compelling story.
$AMD Q1’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $10.25B (Est. $9.89B) 🟢; +38% YoY
🔹 Adj. EPS: $1.37 (Est. $1.28) 🟢; +43% YoY
🔹 Data Center Revenue: $5.8B (Est. $5.6B) 🟢; +57% YoY
🔹 Adj. Gross Margin: 55% (Est. 55.06%) 🔴; +1 ppt YoY
🔹 Data Center now the primary driver of revenue & earnings growth
Q2 Guide:
🔹 Revenue: ~$11.2B +/- $300M (Est. $10.52B) 🟢; +46% YoY at midpoint
🔹 Adj. Gross Margin: ~56% (Est. 55.25%) 🟢
Segment Performance:
🔹 Data Center: $5.8B; +57% YoY
🔹 Client & Gaming: $3.6B; +23% YoY
🔹 Client: $2.9B; +26% YoY
🔹 Gaming: $720M; +11% YoY
🔹 Embedded: $873M; +6% YoY
Other Metrics:
🔹 Meta & AMD: Plan to deploy up to 6 GW of AMD Instinct GPUs
🔹 Meta: First 1 GW to be powered by custom AMD Instinct MI450-based GPU
🔹 Meta: Lead customer for upcoming 6th Gen AMD EPYC CPUs, “Venice” and “Verano”
🔹 AMD & Samsung: Collaborating on HBM4 supply for AMD Instinct MI455X GPUs
🔹 AMD & TCS: Co-developing AMD Helios-based rack-scale AI infrastructure
Financials:
🔹 Adj. Operating Income: $2.54B; +43% YoY
🔹 Adj. Operating Margin: 25%; +1 ppt YoY
🔹 Adj. Net Income: $2.27B; +45% YoY
🔹 GAAP Gross Margin: 53%; +3 ppts YoY
🔹 GAAP Operating Income: $1.48B; +83% YoY
🔹 GAAP Net Income: $1.38B; +95% YoY
🔹 GAAP EPS: $0.84; +91% YoY
Commentary:
🔸 “We delivered an outstanding first quarter, driven by accelerating demand for AI infrastructure, with Data Center now the primary driver of our revenue and earnings growth.”
🔸 “We are seeing strong momentum as inferencing and agentic AI drive increasing demand for high-performance CPUs and accelerators.”
🔸 “Looking ahead, we expect server growth to accelerate meaningfully as we scale supply to meet demand.”
🔸 “Customer engagement around MI450 Series and Helios is strengthening, with leading customer forecasts exceeding our initial expectations and a growing pipeline of large-scale deployments providing us with increasing visibility into our growth trajectory.”
According to the @OECD, Italy’s taxes on workers amount to a STUNNING 45.8% of wages.
It's NO SURPRISE ITALY LAGS WAY BEHIND THE US, where taxes on wages are much lower.
ITALIAN TAXES = ITALIAN WORKERS SLAVES OF THE STATE.
$AMZN CEO: "If our chips business was a standalone business and sold chips produced this year to AWS and other third parties as other leading chip companies do, our annual revenue run rate would be $50 billion. As best as we can tell, our custom silicon business is now one of the top three data center chip businesses in the world. And the speed at which we've gotten here is extraordinary"