Filecrux reads every SEC filing, every day.
Hundreds of companies file paperwork. Most of it is nothing. We find the few that matter and write them in plain English.
Every report ends with a dated call. A later filing settles it. We publish the score either way.
$OLED Is Universal Display's 15% Q3 revenue gain the start of a turn, with 2026 guidance still at the low end?
🏢 Universal Display, an OLED materials and licensing firm, posted Q3 revenue of $160.4M vs $139.6M a year ago, its first yearly gain of 2026 after Q2 fell to $152.2M from $171.8M, against a market value of about $4.15B at the $90.27 close at 16:00 ET on October 28, 2026
📈 Operating income rose 25% to $53.7M, and adjusted EPS of $1.23, which strips out a $28.9M UDC Ventures investment gain, is up 34% from $0.92 a year earlier
⚠️ Reported EPS of $1.72 also counts that gain, a non-cash rise in a minority stake's carrying value, plus a $7.2M currency gain on a Korean tax receivable
⚠️ The year-ago royalty line was cut by a $9.5M out-of-period adjustment, so without it Q3 growth is about 8%, and material sales actually fell to $79.7M from $82.6M as their gross margin slid to 50% from 60%
⚠️ The company still sees 2026 revenue around the low end of $630M-$670M, and after $454.8M in nine months that low end needs about $175M in Q4, roughly 9% above Q3
💰 It bought back 963,333 shares for $78.8M in Q3, cutting diluted shares to 45.8M from 47.7M a year ago, and still held $903.1M in cash and investments on September 30, 2026
📅 Next: Management's call on the quarter follows the release, and the $0.50 Q4 dividend goes to holders of record December 17, 2026, paid December 31, 2026
Source: SEC 8-K, Oct 28 + SEC 8-K, Jul 30
$MUSA Can Murphy USA's 35% profit jump last when RINs credits, not pump margins, supplied most of the gain?
🏢 Murphy USA, a gas and convenience chain with 1,808 stores mostly near Walmart Supercenters, earned $176.0M or $9.59 a diluted share in Q3 2026, up 35% from $129.9M, and is valued at about $9.48B at $515.835 a share at 15:59 ET on October 28, 2026
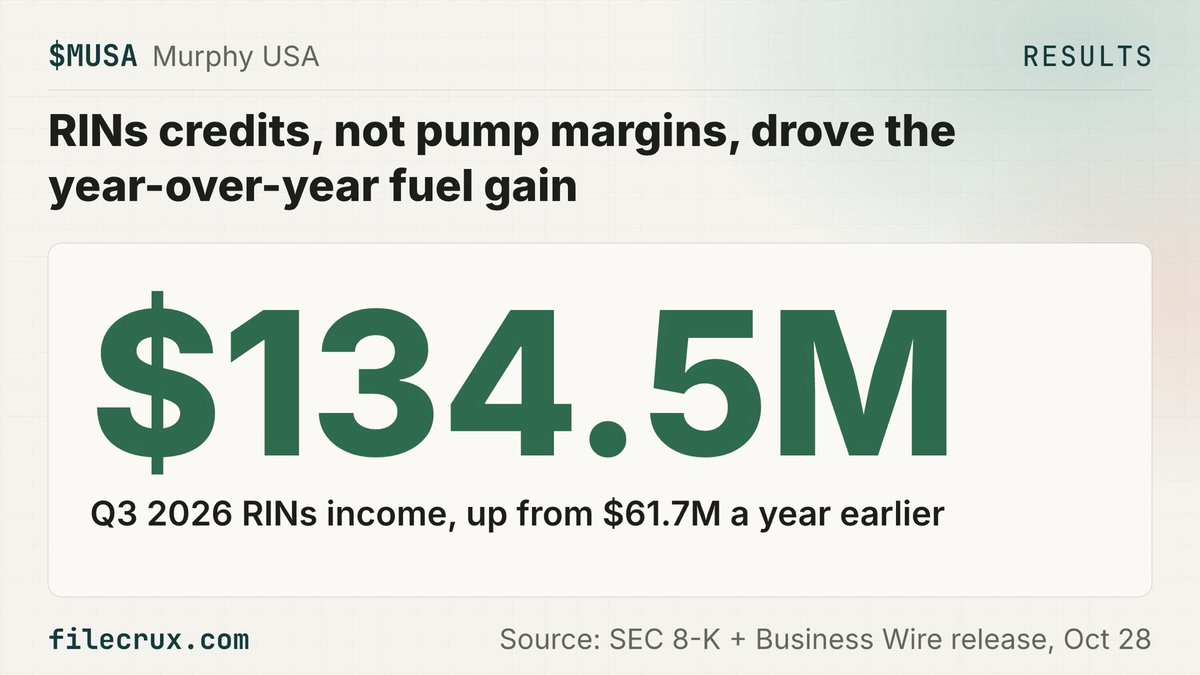
📈 RINs income, booked as other revenue, more than doubled to $134.5M from $61.7M, supplying about $72.8M of the $94.6M rise in total fuel contribution
📉 Store-level fuel profit barely moved, with retail fuel contribution up 0.1% to $355.0M as margins fell 3.2% to 27.4 cpg, while merchandise contribution fell 2.8% to $234.5M against last year's nicotine promotion
📉 Net income was also below Q2 2026's $209.1M, and the release does not update August's outlook of about $636M full-year net income, which assumed 35 cpg all-in fuel margins in the second half
📈 Q3's all-in fuel margin of 37.0 cpg ran above that 35-cent assumption, and nine-month net income of $521.4M leaves about $114.6M for Q4 to reach $636M
💰 Operating cash flow rose to $348.1M from $184.8M, though $148.9M of the rise was a working-capital swing (+$85.6M vs -$63.3M); it covered $154.4M of capex and $157.7M of buybacks at an average $549.22, and buybacks cut diluted shares to 18.36M from 19.23M, so EPS rose 42%
📅 Next: Management Q&A webcast on October 29, 2026 at 10:00 a.m. Central Time; the $0.72 dividend is payable December 1, 2026
Source: SEC 8-K + Business Wire release, Oct 28
$AMRZ Is today's second 2026 adjusted EBITDA cut, to $2.95B–$3.05B after an August 6 revision of February's $3.25B–$3.34B, the last one?
🏢 Amrize, the North American cement, aggregates and roofing supplier spun off from Holcim and worth about $21.91B at $40.06 at 16:00 ET on October 28, 2026, now expects 2026 adjusted EBITDA of $2.95–3.05B on revenue of $12.2–12.4B
✂️ That EBITDA range sits entirely below the $3.25–3.34B the company set on February 17, when it promised 8–11% growth, and follows an earlier revision on August 6
✂️ Revenue guidance is now $12.2–12.4B, with both ends lower than February's $12.29–12.52B, after the August 6 release had raised revenue guidance on demand
⚠️ With $2,253M earned through September, the new range implies $697–797M of Q4 adjusted EBITDA, as the company warns elevated interest rates may hit Q4 volumes and Building Envelope prices will not cover costs until 2027
⚠️ Net debt was $5,549M at September 30, or 1.8x trailing adjusted EBITDA against 1.1x at December 31, 2025, after $1.11B of buybacks and dividends and a $551M nine-month free cash flow outflow left $299M of cash
📈 On the other side, Q3 itself held up, with revenue up 2.2% to $3,771M, net income up 3.3% to $558M and Building Materials margins up 30bps, and the $1B buyback, about 4% of share capital, was completed on October 28, 2026
📅 Next: Q3 earnings presentation dated October 29, 2026; the $0.11 dividend is paid November 18, 2026
Source: SEC 8-K, Oct 28 + Business Wire releases, Feb 17 & Aug 6
$CP Is CPKC's 16% core EPS jump real earnings when reported net income stayed flat at C$916M?
🏢 Canadian Pacific Kansas City, the only single-line railroad linking Canada, the US and Mexico, posted Q3 2026 revenue up 15% to C$4.2B and core adjusted diluted EPS up 16% to C$1.28 from C$1.10, with the stock at $89.56 at 16:05 ET on October 28, 2026
🧾 Reported net income was flat at C$916M and diluted EPS rose only 3% to C$1.04 from C$1.01, because tax expense jumped to C$448M from C$296M, including a C$94M Canada Revenue Agency reassessment tied to the Kansas City Southern purchase
📈 Core EPS of C$1.28 is reported C$1.04 plus C$0.11 of CRA tax, C$0.11 of KCS purchase accounting, C$0.03 of merger advice, C$0.02 of Mexican tax and C$0.01 of acquisition costs, less C$0.04 tax effect
💰 Core adjusted income rose 12% to C$1,119M as diluted shares fell about 4% to 877.6M after 11.3M shares were repurchased for C$1,487M
📉 Ton-mile volume rose 6%, but the operating ratio worsened 130 bps to 64.8%, under fuel's 170 bps hit
🏦 Adjusted free cash of C$1,018M, up from C$415M, did not cover the buyback, and long-term debt rose to C$25,846M from C$23,891M a year earlier
⚠️ CPKC has objected to other CRA positions and says its reserves are enough, but the timing and amount of a final resolution cannot be determined yet
📅 Next: Call at 4:30 p.m. ET on Oct. 28, 2026, replay through Nov. 4, 2026; watch for numbers behind its claim that it is on track to meet its commitments for the year
Source: CPKC Q3 release, SEC 8-K, Oct 28, 2026
$RYZ Will Ryerson's $115.0M adjusted EBITDA (excluding LIFO) beat turn into cash after Q3 operations used $18.2M?
🏢 Ryerson, a metals processor and distributor that merged with Olympic Steel (market value about $1.54B at $29.705 a share at 16:00 ET on October 28, 2026), earned $32.0M ($0.61 a diluted share) in Q3 2026 against a $14.8M loss a year earlier, and its adjusted EBITDA excluding LIFO of $115.0M beat its own $88-92M guidance
🔥 Operations still used $18.2M of cash and free cash flow was -$39.5M in Q3, because working capital needs took up the profit
🏦 Debt rose $51M in the quarter to $1.01B, against $40.5M of cash and a market value of about $1.54B at $29.705 a share at 16:00 ET on October 28, 2026
📈 Revenue rose 87.5% from a year earlier to $2.18B, but $602M of that came from Olympic Steel, leaving same-store revenue at $1.58B
📉 Q4 guidance calls for net income of $16-20M ($0.30-0.38 a share) and adjusted EBITDA excluding LIFO of $100-104M, a step down from Q3's $115.0M, as shipments fall 6% to 8% with three fewer business days
📈 On the other side, leverage fell to 3.2x net debt to trailing EBITDA from 4.0x in Q2, and the company targets below 3.0x by year-end as seasonal working capital needs ease
📅 Next: Ryerson's call to discuss third quarter 2026 results is set for October 29, 2026, 10 a.m. Eastern Time, where the working-capital outlook is the item to watch
Source: PR Newswire release, Oct 28 + SEC 8-K, Oct 28
$EG Is Everest's $600M casualty reserve hit in its core reinsurance book the last one, after over $200M in Q2?
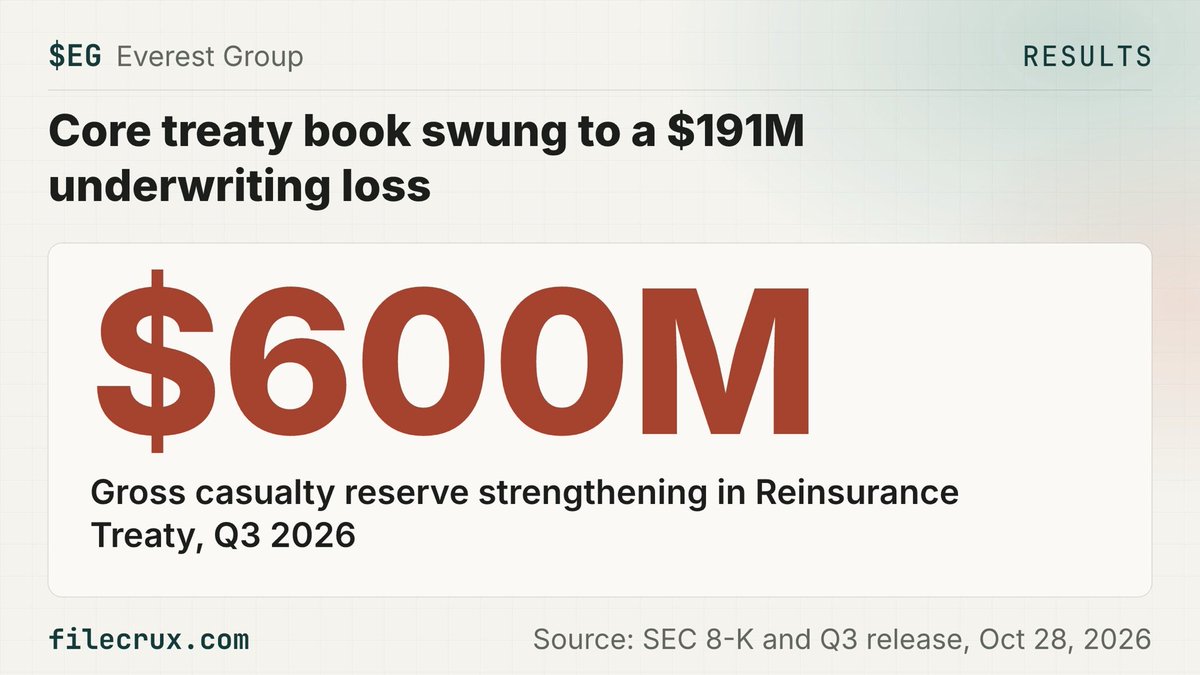
🏢 Everest Group, an S&P 500 reinsurer and insurer worth about $14.82B at $386.47 a share at 16:00 ET on October 28, 2026, took about $600M of gross casualty reserve strengthening in its Reinsurance Treaty segment in Q3 2026
🧾 The segment's $253M of net adverse prior-year development includes that gross strengthening and, with $277M of catastrophe losses, took its combined ratio to 108.5% from 87.0% and a $335M underwriting profit to a $191M loss
⚠️ This is the second quarter in a row of casualty strengthening, after over $200M in Q2, and the treaty book is shrinking casualty fast, with Casualty XOL premiums down 24.8% and Casualty Pro-Rata down 15.8%
📉 Net operating income fell to $290M from $316M while net investment income rose to $634M from $540M; operating EPS rose to $7.62 from $7.54 only as buybacks cut diluted shares to 37.6M from 41.4M
📈 Holders can point to the underlying business: the treaty attritional combined ratio improved to 84.9% from 86.0%, and book value per share excluding bond marks rose to $414.00 from $379.70 at December 31, 2025
⚠️ At $386.47 the stock trades about 1.01 times its $381.04 GAAP book value per share at September 30, so another reserve charge would come straight out of the book that supports the price
📅 Next: Management takes questions on Thursday October 29, 2026; watch whether the casualty reserve review is done
Source: SEC 8-K and Q3 release, Oct 28, 2026
$EBAY Follow-up: Is eBay's Q3 beat worth more than its Q4 guide for just 7–9% growth?
🏢 eBay, the online marketplace, reported Q3 2026 revenue of $3,206M, up 14%, and non-GAAP EPS of $1.51, after its October 22 8-K said Q3 would land above August guidance and announced a cut of about 9% of its workforce costing $130–150M in pre-tax charges, mostly in Q4
📈 Revenue topped August's $3.07–3.12B range by about $86M, GMV of $23.2B beat the $22.0–22.4B guide, and EPS beat the $1.36–1.42 guide
⚠️ Q4 guidance of $3.19–3.24B calls for 7–9% FX-neutral revenue growth, about half of Q3's 13%, with non-GAAP EPS of $1.48–1.53 roughly flat with Q3
⚠️ Part of the growth was bought, since Depop, acquired July 30 for $1.4B in cash, lifted active buyers to 147M while buyers excluding Depop and Tise grew only 1%
📉 GAAP EPS fell 13% to $1.11 because last year's Q3 had a (4.3)% tax rate, against 17.1% now
🏢 At $123.98 at 16:39 ET on October 28, 2026, eBay is worth about $55.17B, about 19.8 times the midpoint of its new full-year non-GAAP EPS guide of $6.25–6.30
💰 eBay returned $827M in Q3, including $689M of buybacks for about 6 million shares, more than its $749M of free cash flow, with about $1.3B of authorization left
📈 The Q4 slowdown runs against a tough base, since Q4 2025 revenue grew 15%, and the full-year guide still calls for 12–13% FX-neutral growth to $12.62–12.67B
📅 Next: Q4 dividend of $0.31 a share is payable December 18, 2026 to holders of record December 4, 2026
Source: PR Newswire release, Oct 28 + SEC 8-Ks
$EHC Can Encompass Health beat its raised $1,395M-$1,415M 2026 EBITDA guide after a 15.5% Q3 jump?
🏢 Encompass Health, the largest US inpatient rehab hospital operator, is worth about $12.06B at $122.22 a share at 16:00 ET on October 28, 2026, and grew Q3 2026 adjusted EBITDA 15.5% to $346.6M on revenue up 8.9% to $1,609.5M
🚀 It lifted 2026 adjusted EBITDA guidance to $1,395M-$1,415M from $1,365M-$1,395M and adjusted EPS to $6.23-$6.37 from $6.02-$6.25, so the new floor is the old ceiling
📈 Because January-September adjusted EBITDA already totals $1,043.4M, the new range implies $351.6M-$371.6M for Q4, 1.4% to 7.2% above Q3, and Q4 adjusted EPS of $1.56-$1.70 versus Q3's $1.52
📈 Demand carried the quarter, with discharges up 5.7%, same-store discharges up 3.0% and net patient revenue per discharge up 4.0% to $22,543
💰 Q3 diluted shares fell to 99.7M from 102.3M a year earlier, helped by 1,906,499 shares bought back for $203.7M this year, so adjusted EPS rose 23.6% against 20.7% adjusted income growth to $151.9M
🏦 Nine-month capex rose to $617.2M from $507.1M and long-term debt to $2,551.3M from $2,447.2M at year-end, though debt to adjusted EBITDA eased to 1.9x from 2.0x
⚠️ The release lists rising Medicare audit activity and the CMS review choice demonstration among risks that could leave reimbursement claims unpaid or delayed
📅 Next: Management walks through the quarter on its October 29, 2026 earnings call, and the September 2026 Form 10-Q is still to be filed
Source: PR Newswire release + SEC 8-K, Oct 28, 2026
$UCTT Will Ultra Clean sell the last $193.2M of its stock program after raising $169.1M from September 26 to October 28?
🏦 Ultra Clean, a Hayward, Calif. supplier of parts, subsystems and cleaning services mainly to the chip industry, sold 2.2 million new shares for $169.1M net from September 26 to October 28, 2026, after its quarter closed, its October 28 10-Q says
🏦 The October 27 results release showed only $34.0M of such sales through the September 25 quarter end, under an August 14, 2026 agreement allowing up to $400M of share sales
⚠️ The 2.2 million shares add about 4.9% to the 45.3 million shares outstanding on July 29, and the $169.1M equals about 6.7% of Ultra Clean's roughly $2.54B market value at $56.04 a share at 16:00 ET on October 28, 2026
⚠️ The new shares equal about 4.8% of the 46.2 million diluted shares behind Q3 EPS, and the 10-Q does not say whether the October 27 Q4 EPS guide assumed them
⚠️ About $193.2M of the program is still unused, which at $56.04 would mean roughly 3.4 million more shares before fees, or about 7.6% of the July share count; the company is not obligated to sell any of it
📈 In return the company got about $77 a share after fees, against an $80.13 weighted-average sale price before fees on Q3 sales and well above the $56.04 close at 16:00 ET on October 28, 2026, and used part of the cash to repay its $50.0M revolver in full
📅 Next: Later filings will show whether the remaining $193.2M is sold; the 10-Q gives no date
Source: SEC 10-Q, Oct 28 + 8-K, Oct 27
$AWK Will American Water's standalone 2027 EPS guide of $6.53–$6.63 still count once the Essential merger closes?
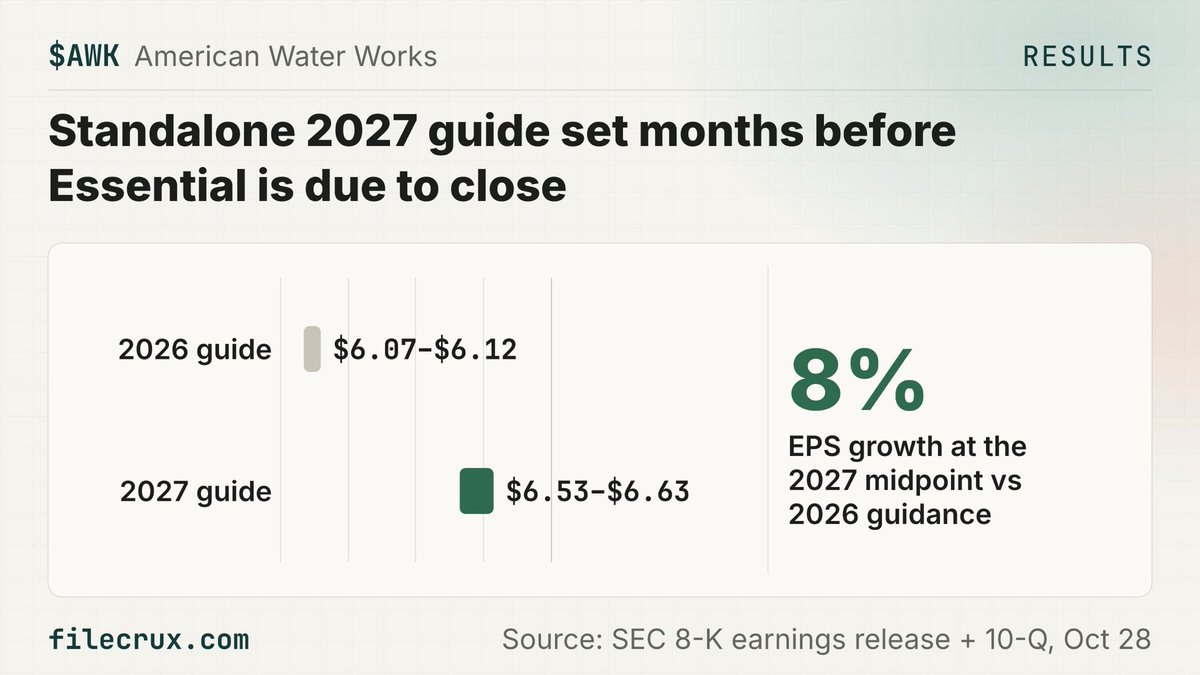
🏢 American Water Works, a US water and wastewater utility worth about $27.8B at $139.86 a share at 16:00 ET on October 28, 2026, set standalone 2027 adjusted EPS guidance of $6.53–$6.63, which it puts at 8% growth at the midpoint over 2026 guidance
🚀 It also narrowed 2026 adjusted EPS guidance to $6.07–$6.12 from $6.02–$6.12 after Q3 adjusted EPS rose to $2.00 from $1.89, while Q3 GAAP EPS stayed flat at $1.94, held down by weather and merger costs this year and by HOS seller-note interest income that lifted Q3 2025
⚠️ The 2027 range leaves out the all-stock Essential Utilities merger, which pays 0.305 AWK shares per Essential share and is expected to close by the end of Q1 2027, so the share count behind 2027 per-share earnings will change
🏦 Growth is funded with debt and equity: 2027 standalone capex is $4.1B against about $3.7B for 2026, long-term debt rose to $13.99B from $12.78B as the current portion fell to $898M from $1.48B, and June equity forward settlements raised $476M
✅ To recover its spending, regulators have granted $284M of new annualized revenue since January 1, with $360M more requested, and 8% growth sits inside the 7-9% long-term EPS target the company affirmed
📅 Next: Management walks through the 2027 guide on a 9 a.m. ET conference call on October 29, 2026, and still targets an Essential close by end of Q1 2027
Source: SEC 8-K earnings release + 10-Q, Oct 28
$INVH Can Invitation Homes' new $500M buyback keep lifting Core FFO per share if home sales keep funding it?
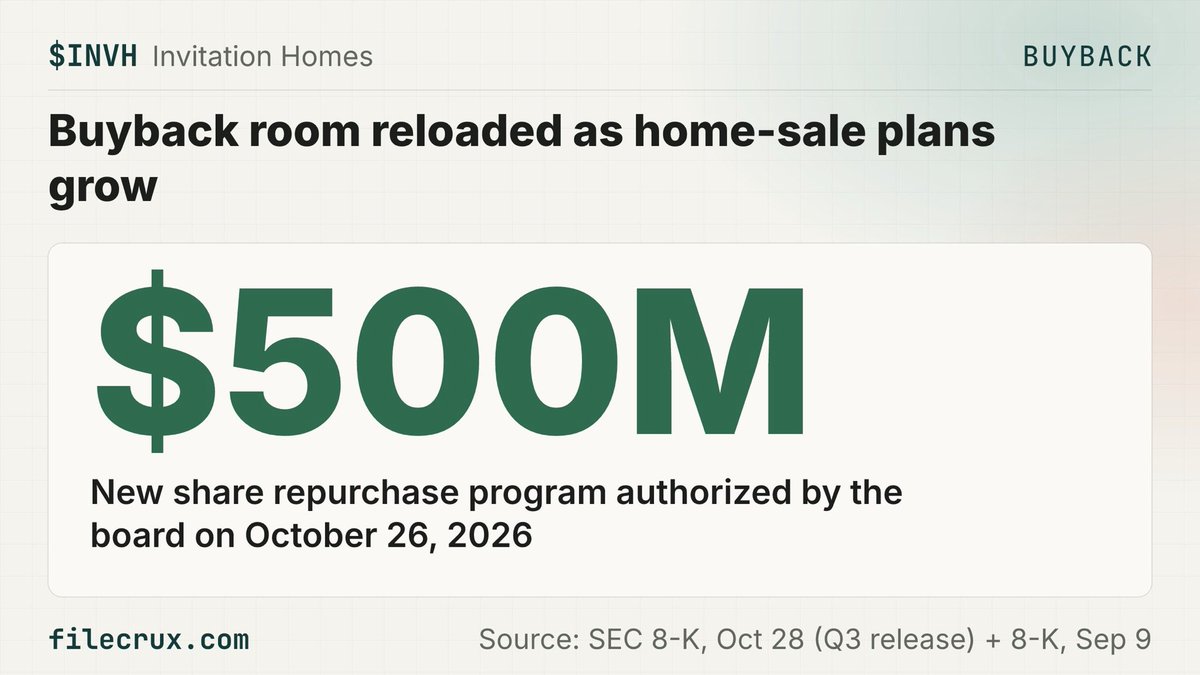
💰 Invitation Homes, an S&P 500 single-family home landlord, said its board authorized a new $500M share buyback on October 26, 2026, alongside its Q3 results
💰 The new program equals about 3.2% of the company's roughly $15.80B market value at $26.75 a share at 16:00 ET on October 28, 2026
🏢 It adds to room that was nearly used up, since the company bought back nearly $1B of stock from December 1, 2025 through October 27, 2026 at an average $26.78, against a $1B authorization that had $300M left as of September 4
🚀 Full-year 2026 Core FFO guidance rose $0.01 to a $1.96 midpoint, and after $1.46 earned through nine months that implies about $0.50 a share in Q4 versus $0.48 in Q3
🏦 Buybacks are funded by home sales, and the $950M sales guidance, up $100M, leaves only about $117M to sell in Q4 after $833M sold year to date; the $500M program has no expiration date and repurchases are at the company's discretion
⚠️ The bear case is that growth leans on buybacks, with Q3 Core FFO up 2.4% mainly on a lower share count and Same Store NOI up 1.1%, though the company sells homes near $460K while its stock implies about $280K per home
📅 Next: Management webcasts its Q3 review on Thursday, October 29, 2026; watch for the pace of buybacks and Q4 home sales
Source: SEC 8-K, Oct 28 (Q3 release) + 8-K, Sep 9
$COHU Can Cohu's AI-chip test ramp, with a $178M Q4 guide up 46% and a ~$120M HPC outlook, keep growing into 2027?
🏢 Cohu, a San Diego maker of chip test and inspection equipment worth about $2.52B at $53.19 at 16:00 ET on October 28, 2026, reported Q3 2026 sales up 37% to $173.0M and GAAP net income of $12.1M against a $4.1M loss a year earlier
🚀 Cohu raised its FY26 high-performance computing revenue outlook to about $120M from the $100M to $110M it gave on July 30, roughly a fifth of the about $625M full-year sales implied by $447.1M for nine months plus the $178M Q4 midpoint
📈 Q3 bookings rose 126% from a year earlier, with systems up 318% and recurring up 36%; the release gives growth rates, not a bookings dollar total, against Q3 sales growth of 37% and a Q4 guide of $178M plus or minus $7M
🏦 Cash and investments of $507.9M on September 26 cover about $302M of borrowings and debt; Q3 interest expense rose to $1.8M from $0.1M a year earlier, while interest income rose to $3.9M from $1.3M
⚠️ Q3 diluted weighted shares were 54.4M against 47.4M basic, so Q3 GAAP EPS was $0.22 diluted against $0.26 basic
⚠️ The case against is that Q3 sales beat the $170M midpoint guided on July 30 by only $3M, and $53.19 is about 31 times Q3 non-GAAP EPS of $0.43 annualized
📅 Next: Q4 2026 results will test the $178 million +/- $7 million sales guide and the ~$120 million HPC outlook
Source: SEC 8-K, Oct 28 + SEC 8-K, Jul 30
$DMC Can Del Monte Foods lift adjusted EPS back up after it fell 28% to $0.50?
📉 Del Monte Corporation, the former Fresh Del Monte Produce selling fresh and packaged food in more than 90 countries, saw Q3 2026 adjusted diluted EPS fall about 28% to $0.50 from $0.69 while net sales rose 7.2% to $1.10B
🔥 Bananas, 29% of sales, swung to a $2.7M gross loss from a $4.6M profit, including about $6.1M of extra Costa Rica disease-prevention costs after heavy El Niño rain
🏦 Long-term debt rose to $482.5M from $173.0M at end-2025 on the Del Monte Foods purchase and inventory, over a third of the roughly $1.37B market value at the $29.01 close, 16:00 ET October 28, 2026
📉 Quarterly interest expense more than tripled to $6.3M from $1.8M, a key reason adjusted EPS fell while adjusted EBITDA rose 5.0% to $60.9M
🔥 Nine-month operating cash flow fell to $53.1M from $234.2M as inventories took $101.1M, short of $69.2M of capex plus $42.5M of dividends, leaving $21.1M of cash
⚠️ As a Permitted Acquisition, the Del Monte Foods deal stepped the credit agreement's leverage cap up to 4.25x from 3.75x for four quarters, and it says it complied on September 25, 2026
📈 Prepared Foods, built on Del Monte Foods, earned the top segment gross margin of 17.5% on $261.2M of sales and helped lift total gross profit 27.0% to $102.6M
📅 Next: Q4 cash flow shows whether the inventory build unwinds, while the board keeps the $0.30 quarterly payout, due December 4, 2026 (record date November 11, 2026)
Source: SEC 10-Q + 8-K earnings release, Oct 28, 2026
$UFPI Is UFP Industries' 11.1% sales gain worth much when Q3 net earnings fell 22.4% on a $19M freight hit?
🏢 UFP Industries, a Grand Rapids maker of wood products for retail, packaging and construction, said Q3 2026 sales rose 11.1% to $1.73B but net earnings fell 22.4% to $58.6M, about 1.4% of its ~$4.32B market value at $78.27 at 16:00 ET on Oct. 28, 2026
📉 Diluted EPS fell to $1.05 from $1.29 a year ago and the adjusted EBITDA margin fell to 6.9% from 9.0%, as freight net of fuel surcharges rose $19M, or 1.3% of net sales
⚠️ Packaging was hit hardest, with net earnings down 46.6% on 18.0% higher sales, while freight spot rates rose 30% in the quarter before leveling off at a high level
📉 Nine-month operating cash flow fell to $235M from $399M, with about $100M tied up in seasonal working capital that the company expects to turn into cash in Q4
🤝 The results follow the Oct. 26, 2026 8-K on buying pallet maker Apache Products for about $27M, small next to roughly $2.0B of liquidity and no revolver borrowings
💰 On the other side, the full-year outlook is unchanged, the company expects to meet or exceed its $60M cost-savings goal by year-end, and it bought back $182.7M of stock this year at an average $84.24
📅 Next: CEO Will Schwartz and CFO Michael Cole take the results to investors on October 29, 2026 from 10:00 a.m. ET, with freight rates the figure to watch
Source: PR Newswire release, Oct 28 + SEC 8-K, Oct 26
$MTH Can Meritage keep returning more cash than it earns while orders fall 15% and cash slides to $677M?
🏢 Meritage Homes, the fifth-largest U.S. homebuilder, worth about $4.04B at $62.005 a share at 15:59 ET on October 28, 2026, said Q3 2026 net earnings fell 32% to $67.8M, or $1.04 a diluted share against $1.39 a year earlier
💰 In the first nine months of 2026 it paid out nearly $380M in buybacks and dividends, which is 177% of its $213.7M of earnings, and bought back 6.0% of its shares, with $229M of buyback room left
📉 Cash fell to $677M at September 30 from $807.3M at June 30, a drop of about $130M in a quarter when only $86M went to buybacks and dividends
📉 The sales that pay for those returns are slowing: Q3 orders fell 15% to 3,083 homes, and backlog fell 5% to 1,611 homes, about half of the 3,187 homes it closed in Q3
⚠️ Home closing gross margin fell 170 bps to 17.4% on higher lot and incentive costs, and net debt-to-capital rose to 18.9% from 16.9% at December 31, 2025
📈 On the other side, operating cash flow for the nine months was $259.5M against a $125.4M outflow a year earlier, Q3 land spend was cut almost 40% to $329M, and nothing is drawn on the revolver
📅 Next: The Q3 call is at 11:00 a.m. Eastern Time on Thursday, October 29, 2026; watch the next quarter's order trends and the buyback pace
Source: GlobeNewswire release, Oct 28 + SEC 8-K, Oct 28
$F Can Ford reach its raised $10.5B–$11B profit guide with wholesale shipments down 9%?
🚀 Ford, the Dearborn maker of Ford trucks and Lincoln luxury vehicles worth about $46.57B at $11.67 a share at 16:37 ET on October 28, 2026, lifted its full-year adjusted EBIT floor, now guiding $10.5B–$11B versus $10B–$11B before
📉 Third-quarter wholesale shipments fell 9% to 1,049,000 vehicles and revenue slipped 2% to $49.5B, yet adjusted EBIT edged up to $2.7B from $2.6B a year ago
📉 Ford Pro EBIT fell 16% and Ford Blue EBIT fell 10% on commodity costs and lower volume, so the gain leaned on a smaller Model e loss and a 27% rise in Ford Credit pre-tax earnings to $803M
📉 Net income fell to $2.0B from $2.4B mostly on taxes, as a $630M tax benefit a year ago became a $97M provision while pre-tax income rose to $2.15B from $1.82B
📈 With $8.6B of adjusted EBIT banked through nine months, the new range needs $1.9B–$2.4B in Q4, below Q3's $2.7B but above the roughly $1.0B Ford earned in Q4 2025
⚠️ Free cash flow guidance stayed at $6B–$7B against $4.9B so far, and the outlook excludes a significant Middle East escalation or a material US downturn
📈 Adjusted free cash flow rose to $4.7B from $4.3B a year ago, and Ford ended the quarter with $25.3B of cash and $46.4B of liquidity
📅 Next: The 15-cent dividend is payable Dec. 1 to holders of record Nov. 10, and replays of the October 28 call run through November 4, 2026
Source: SEC 8-K and Q3 release, Oct 28, 2026
$EFOR Does Everforth's beat of its own Q3 guidance hide a 39% drop in net income?
🏢 Everforth, a technology and digital engineering company worth about $1.58B at $38.615 a share at 16:00 ET on October 28, 2026, reported Q3 2026 revenue of $1,031.4M, up 2% from a year ago and above the top of its guidance
📉 Q3 net income fell 39% to $23.1M, or $0.56 a diluted share against $0.87 a year ago, as gross margin slipped 110 basis points to 28.3%, SG&A rose to $217.7M from $212.2M (including $8.3M of acquisition, integration and strategic planning costs against $4.2M), net interest expense rose to $20.2M from $17.4M and income taxes rose to $13.3M from $12.4M
⚠️ The Q4 guide of $965–995M in revenue and $93–103M in adjusted EBITDA puts even its top end below Q3's $106.3M, partly because Q4 has 3 fewer billable days than Q3
⚠️ Free cash flow fell to $46.5M from $72.0M a year ago, and long-term debt stood at $1,391.0M on September 30, up from $1,169.4M at the end of 2025, though the company cut debt by $52.8M during the quarter
📈 On the other side, net income rose 63% from Q2's $14.2M, the company paid down $52.8M of debt in the quarter, and the diluted share count fell to 41.1M from 43.7M a year ago
📅 Next: Watch whether Everforth lands inside its $965–995M Q4 revenue range; a replay of the October 28 call is available until November 11, 2026
Source: SEC 8-K with Q3 2026 earnings release, Oct 28
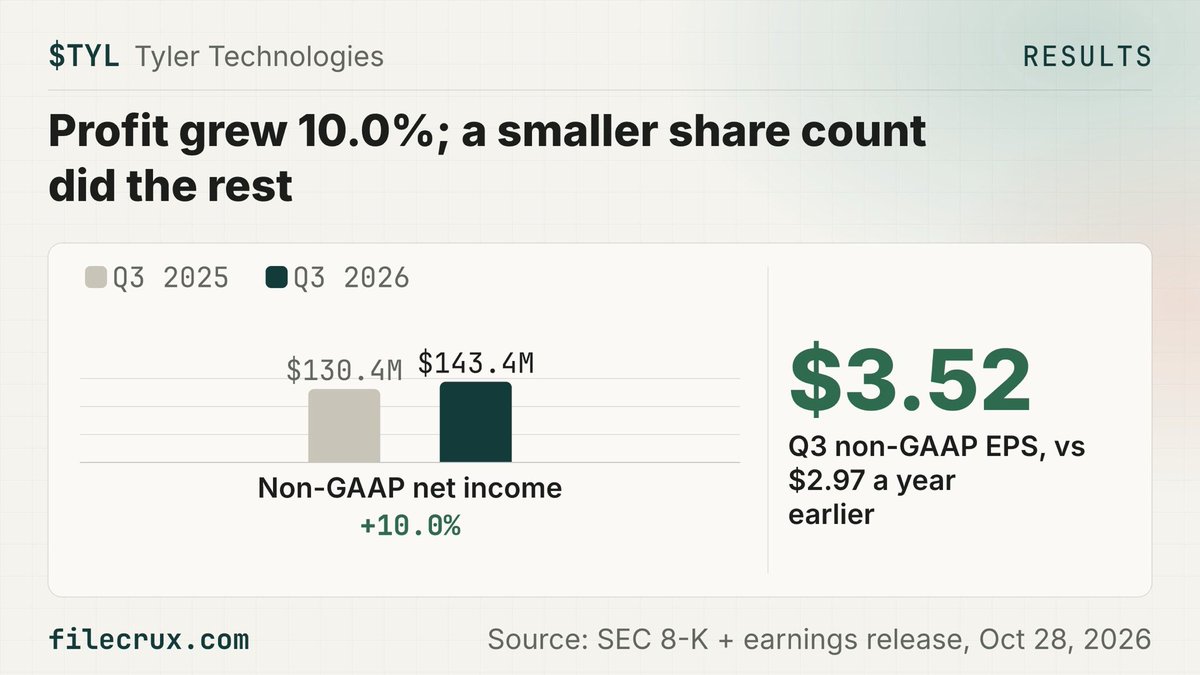
$TYL Can Tyler keep EPS growing once its $260.0M buyback plan ends on October 29, 2026?
🏢 Tyler Technologies, the S&P 500 software maker for local, state and federal governments, reported Q3 2026 non-GAAP EPS of $3.52, up from $2.97 a year earlier, on revenue up 8.7% to $647.6M
⚠️ Non-GAAP net income rose only 10.0%, to $143.4M from $130.4M, so the rest of the EPS gain came from diluted shares falling to 40.7M from 43.8M
💰 Tyler spent $1.124B on its own shares in the first nine months, about 7.6% of its $14.79B market value at $361.05 at 16:00 ET on October 28, 2026
🏦 The Q3 buyback of $369.1M outran free cash flow, so cash fell $107.1M to $788.2M, and $1.41B of convertible notes due 2031 lifted Q3 interest expense to $3.8M from $1.2M
⚠️ Full-year non-GAAP EPS guidance of $12.95 to $13.20, less $9.79 earned through September, implies Q4 EPS of $3.16 to $3.41, below Q3's $3.52
🏆 On the other side, GAAP operating income rose 19.5% to $117.0M, SaaS revenue grew 21.2%, and record free cash flow of $277.0M covered about three-quarters of the Q3 buyback
📅 Next: Tyler's $260.0M repurchase plan runs out on October 29, 2026, the morning management takes analyst questions, with about $1.37B of buyback authorization still left
Source: SEC 8-K + earnings release, Oct 28, 2026
$HAPN Can Happen beat its raised $1.87-$1.92 2026 EPS guide once Q4 is reported?
🚀 Happen, formerly LendingClub, is a digital bank holding $13.3B of assets, valued near $1.65B at $14.325 a share at 16:35 ET on October 28, 2026, and it raised its 2026 diluted EPS guide to $1.87-$1.92 from $1.80-$1.90 after Q3 EPS of $0.50, up 35% from $0.37
⚠️ Its new Q4 guide of $0.43-$0.48 is below the $0.50 earned in both Q2 and Q3, and with $1.44 already earned through Q3 it is exactly what the $1.87-$1.92 full-year range implies.
📉 Total net revenue slipped 1% to $263.2M, which the company ties to its 2026 switch to fair value accounting, while pre-tax income rose 34% to $76.8M as a $15.9M provision benefit replaced a $46.3M expense
⚠️ Marketing spend jumped 79% to $72.8M, and the guide assumes a stable consumer plus a 25 basis point Fed hike in December
🚀 The guide midpoint moves about 2.4% to $1.895, which puts the $14.325 price at about 7.6 times 2026 EPS guidance and 1.09 times Q3 tangible book of $13.11 a share
📈 Against that, the low end of the Q4 guide is still 23% above Q4 2025's $0.35, originations grew 26% to $3.3B and risk-adjusted revenue rose 27% to $279.1M
📅 Next: Q4 2026 results against the $0.43-$0.48 EPS guide; Happen's webcast was slated for 2:00 p.m. Pacific Time, Wednesday, October 28, 2026
Source: PR Newswire release + SEC 8-K, Oct 28
$OGE Follow-up: Will OGE's new $750M share-sale program blunt its weather-driven 2026 EPS raise?
🏢 OGE Energy, parent of utility Oklahoma Gas and Electric with about 919,000 customers in Oklahoma and western Arkansas, set up a program on October 28, 2026 to sell up to $750M of common stock over time through 12 sales agents, including by forward sales
🚀 It follows the company's Q3 release filed by 8-K the same day, which lifted 2026 EPS guidance to $2.62-$2.68 because of warmer than normal weather
⚠️ At the $48.875 close at 16:00 ET on October 28, 2026, $750M buys about 15.3M shares, roughly 7.4% of the 206.4M outstanding and of OGE's about $10.09B market value
⚠️ If fully issued, that would spread earnings over about 7% more shares, after Q3 diluted shares already rose to 208.2M from 202.1M a year earlier
🏦 OGE says proceeds will fund capital spending and other general corporate purposes, including repaying or refinancing debt, and it had $135.1M of short-term debt at a 4.17% average rate on September 30, 2026
🏦 OGE does not have to sell anything and can suspend the program at any time, and forward sales pay cash only at settlement, at a price that adjusts daily and falls for expected dividends, possibly none if OGE picks cash or net share settlement
📅 Next: Watch the next quarterly filing for shares sold or forward agreements entered under the program
Source: SEC 424B5 + 8-K, Oct 28