Impressionante grafico che conferma quello che segnalo da tempo: la Cina non ha più bisogno di commerciare, perché la sua domanda interna è coperta dalla produzione domestica. La parte eccedente della quale inonda il pianeta
(HT Torsten Slok)
What Everyone Missed In Leo’s Blow-Up👇
Leopold Aschenbrenner lost $30 billion (~67%) in a month.
The consensus post-mortem, from the Wall Street Journal to the replies on X, is that a young man used 4-to-1 leverage on concentrated positions and got carried out. While that is true, it does not convey any useful information. Leverage is certainly the reason Leopold lost so much, so quickly. But it is not the reason he lost. Leverage is merely a magnifying glass. It doesn’t pass judgement.
The reason the reason his fund was doomed was because he’s wrong. And no one, anywhere, has explained why.
On the morning of Thursday, July 30, before the opening bell, Situational Awareness LP sold its entire public stock portfolio — the long side and the short side together, roughly $16 billion of it — to Citadel in a single block trade.
Millennium Management and Jane Street bid for the assets. Ken Griffin and Citadel won.
That night, Aschenbrenner wrote to his limited partners. Net performance for the month, unaudited: down 67%. Net performance for the year: still up 80%.
"We let you down this month," he wrote. "We came closer to permanent capital impairment than is acceptable to us."
Six days earlier, on July 24, he had written a different letter. That one reported a 439% net return for the first half of 2026, described the selloff in artificial intelligence stocks as one of the best buying opportunities since early 2025, and invited his investors to wire more money starting August 1. It closed with a postscript: "At times we call out opportunities that seem like a particularly good time to add funds, if you have been waiting for one."
Assets that stood near $45 billion at the start of July finished the month around $10 billion, and roughly half of what remains is a single illiquid private stake in Anthropic.
Leopold is 25 years old. He graduated from Columbia at 19, as valedictorian. He worked at the FTX Future Fund from February to November of 2022, then joined OpenAI's Superalignment team, then was fired in April 2024. Two months after the firing he published a 165-page essay called "Situational Awareness: The Decade Ahead," raised $225 million from Patrick and John Collison, Nat Friedman and Daniel Gross, and started a hedge fund. He had never managed money before.
Situational Awareness was constructed to express only two ideas.
The first conviction: the physical build-out of artificial intelligence — the chips, the memory, the power, the data centers, the neoclouds — was the trade of the decade. The fund's disclosed long positions read like an inventory of the second derivative of the AI boom. Bloom Energy Corporation (NYSE: BE), fuel cells for data centers. Sandisk Corporation (NASDAQ: SNDK) and Micron Technology, Inc. (NASDAQ: MU), memory. CoreWeave, Inc. (NASDAQ: CRWV) and Nebius Group N.V. (NASDAQ: NBIS), rented compute. IREN Limited, Core Scientific, Applied Digital, Riot Platforms, CleanSpark, Bitfarms, Bitdeer — bitcoin miners converting their substations into AI compute.
The second conviction: application software was going to be destroyed by A.I. Not disrupted. Obliterated.
Leo explained why on Dwarkesh Patel's podcast, in June 2024:
"I'm so bearish on the wrapper companies because they're betting on stagnation. They're betting that you have these intermediate models and it takes so much schlep to integrate them. I'm really bearish because we're just going to sonic boom you. We're going to get the unhobblings. We're going to get the drop-in remote worker. Your stuff is not going to matter."
That was the whole thesis. Buy the compute. Short the stuff that runs on the compute.
By CNBC's reporting, the short leg included Adobe Inc. (NASDAQ: ADBE). A 13F does not disclose short stock. It does not disclose swaps. We only know about Adobe because reporters were told… but you can look at the tape and, when you do, it’s clear that Leo was short software in a major way.
Between the June 30 close and the July 29 close — the last session before the block trade cleared his shorts — the two sides of his portfolio did this.
The longs:
· Sandisk: down 55.32%
· Nebius: down 46.33%
· Bloom Energy: down 45.90%
· CoreWeave: down 38.90%
· Micron: down 35.98%
· IREN: down 35.91%
The shorts, over the same 20 sessions:
· Workday, Inc. (NASDAQ: WDAY): up 37.24%
· Adobe: up 28.49%
· Intuit Inc. (NASDAQ: INTU): up 27.64%
· Salesforce, Inc. (NYSE: CRM): up 20.25%
· Veeva Systems Inc. (NYSE: VEEV): up 17.15%
Over that same window the Invesco QQQ Trust fell 10.14% and the SPDR S&P 500 ETF Trust fell 2.32%. Nvidia — the supposed epicenter of the AI trade — fell 5.04%, and finished the full month of July up 0.33%.
This was not an AI crash.
The S&P 500 stayed near its record throughout. This was a violent rotation out of the leveraged, capital-hungry, second-derivative end of the AI complex and into the profitable, cash-generating, asset-light end of it. Which is to say: the market rotated out of exactly what he owned and into exactly what he was short.
Then there is Microsoft.
Microsoft Corporation (NASDAQ: MSFT) closed at $390.54 on Wednesday, July 29. It closed at $451.10 on Thursday, July 30. That is a gain of 15.51% in a single session on 110.2 million shares, against a July average of 37.1 million. Yes, Microsoft reported its fiscal fourth quarter after the close on July 29. But the results were nothing out of the ordinary. Revenue came in at $90.007 billion against a $87.62 billion consensus. That is a 2.7% beat. Earnings were $4.74 per share against $4.21. It was a good quarter. Not a historic one. A 2.7% revenue beat does not add roughly $450 billion of market value to the most widely owned company on earth in six and a half hours. Something else was in that tape.
And the answer is extremely important. Leo blew up quickly because of leverage. But he failed because he is simply wrong.
Aschenbrenner's software thesis rests on a single premise: that a company selling enterprise software is selling the work the software performs. If a model can perform that work, the company is worth nothing.
That premise is what a very smart 25-year-old engineer believes. It is not what anyone who has ever run a business believes.
Nobody buys Microsoft because Microsoft writes the best code. They buy Microsoft because Microsoft is the rail everything else runs on. Active Directory is where your employee identities live. Excel is where your board deck's numbers come from. Teams is where the compliance-recorded conversation happened. Azure holds a FedRAMP High authorization and Department of Defense Impact Level 5 clearance, which means a defense contractor cannot casually swap it out for something cheaper without re-clearing the entire stack with the government.
Veeva runs the customer relationship management and regulatory document systems of the pharmaceutical industry. Nineteen of the top 20 biopharmaceutical companies use Veeva's regulatory information management platform. Those systems are validated under GxP — the good-practice quality regulations that govern anything touching a drug — and 21 CFR Part 11, the Food and Drug Administration's rule for electronic records and signatures. Every major release is formally qualified. When an FDA inspector arrives, the audit trail in that system is the company's defense.
You cannot replace that with a model that is very good at writing code. You would have to re-validate a decade of regulated records, in front of a regulator, on a system with no track record, to save a fee that rounds to nothing in terms of the cost of building a new drug.
How small a fee? Veeva's licensing runs somewhere between roughly $1,800 and $6,600 per sales representative per year. A fully loaded pharmaceutical sales rep costs the employer between $134,000 and $219,000 a year. The software is 1% to 5% of the cost of the person using it.
Microsoft raised the price of a Microsoft 365 E3 seat from $36 to $39 per user per month on July 1 of this year, and E5 from $57 to $60. Add Copilot at $30 and a fully loaded E5 seat costs $1,080 a year. Against a knowledge worker costing $75,000 to $120,000 all-in, that is roughly 1% of the employee.
This is the part the compute maximalists cannot see. These companies are not selling labor. They are selling the rails on which labor runs, at a price so far below the value created that the buyer never bothers to negotiate hard, and with switching costs so high that the buyer could not leave even if he wanted to.
Do people try to leave? Constantly. And they almost always fail. (Ask me how I know!)
Panorama Consulting Group's tracked studies of enterprise resource planning replacements put average cost overruns at 189% across industries. Gartner projects that by 2027, more than 70% of recently implemented ERP initiatives will fail to fully meet their original business goals. Ripping out a core enterprise system is one of the most reliably disastrous things a large company can attempt, and it was true before anyone had heard of a transformer model.
The incumbents are not being disintermediated by artificial intelligence. They are selling it!
Microsoft passed 30 million paid Copilot seats in the June quarter, up from 15 million in January. Tech wizards like Leo hate copilot. Just like they hated Windows ’97. And everything else Microsoft has ever built. So what? Accenture alone bought 740,000 of them. Bayer, Johnson & Johnson, Mercedes-Benz and Roche have each deployed more than 90,000. Microsoft's commercial remaining performance obligation — contracted revenue not yet recognized, which is the closest thing software has to a railroad's signed freight contracts — stands at $678 billion, up 84% year over year!
Adobe's AI-first annual recurring revenue passed $500 million in the quarter ended May 2026 and tripled year over year. Salesforce's Agentforce went from $800 million of annual recurring revenue in the January quarter to $1.2 billion by April, up 205%. Veeva is giving its AI agents away free inside Vault CRM through 2030, which is the single most revealing data point in the set: Veeva does not need to monetize AI, because Veeva's moat is the validated record, not the intelligence applied to it.
Aschenbrenner thought AI would eat the applications. Instead the applications are selling AI as an upsell on top of a subscription the customer cannot afford to cancel – because it costs nothing compared to the value it delivers.
These software companies are computing toll booths: they’re what enterprises pay to implement compute. And, as compute gets cheaper, they will generate vastly more revenue, not less. The proof is sitting there in their earnings and cash flows: they’re riding on lower and lower cost of compute, which makes their business more and more efficient.
· Adobe: 36.6% operating margin, 35.6% return on invested capital, capital expenditure of $179 million on $23.8 billion of revenue — 0.75% — and $9.85 billion of free cash flow.
· Veeva: 28.7% operating margin, 68.5% return on invested capital, a 44.3% free cash flow margin, and effectively no capital expenditure at all.
· Salesforce: $41.5 billion of revenue, roughly $14.4 billion of free cash flow, capital expenditure of about 1.4% of revenue, and $72.4 billion of contracted backlog.
· Intuit: $18.8 billion of revenue, roughly $6.1 billion of free cash flow, $124 million of capital expenditure.
Veeva earns 68 cents a year on the dollar. And invests nothing it growing its business.
Adobe currently trades at about 11 times trailing earnings. Salesforce at about 13. Intuit at about 14. These are the multiples of a dying industry, applied to businesses converting a third to nearly half of every revenue dollar into free cash.
This enormous mispricing was manufactured by people who like Aschenbrenner, believed these businesses were doomed. But they aren’t.
And that’s not all.
Aschenbrenner assumed that because a technology is transformative, the capital that builds it will earn its cost.
There is no relationship between those two things. In fact, it’s more likely not to be true.
Leo’s own essay contains the tell: "Over the past year, the talk of the town has shifted from $10 billion compute clusters to $100 billion clusters to trillion-dollar clusters. Every six months another zero is added to the boardroom plans."
He wrote that as a bull case. But it isn’t. That is a recipe for a financial disaster.
https://t.co/gqUIUAzmYP, Inc. (NASDAQ: AMZN) spent $131.8 billion of capital expenditure in 2025 against $139.5 billion of operating cash flow. That is 94.5% of everything the business generated, poured back into the ground, in a single year. Its 2026 cap ex guidance is $220 billion.
Alphabet Inc. (NASDAQ: GOOGL) spent $91.4 billion in 2025, 55.5% of operating cash flow, and guides to $195 billion to $205 billion this year.
Meta Platforms, Inc. (NASDAQ: META) spent $72.2 billion, 62.4% of operating cash flow, and guides to $125 billion to $145 billion.
Microsoft spent $115.9 billion in the fiscal year that just ended, against $182.9 billion of operating cash flow. Capital expenditure was 34.9% of revenue, up from 18.1% two years earlier. Free cash flow fell to $67.0 billion from $74.1 billion in fiscal 2024, on revenue that grew by more than a third over the same span. Microsoft is running harder and generating less cash. That is what a huge capital cycle does even to the best business in the world.
Moody's projects hyperscaler capital expenditure of $785 billion in 2026 and close to $1 trillion in 2027, funded in part by roughly $175 billion of debt issuance this year. Where will the money come from…?
Oracle: fiscal 2026 capital expenditure of $55.7 billion, free cash flow of negative $23.7 billion, capital expenditure at 82.6% of revenue, long-term debt up from $76.3 billion to $124.7 billion, and $248 billion of future data-center lease obligations not yet on the balance sheet.
CoreWeave: $5.13 billion of 2025 revenue, $14.9 billion of capital expenditure, negative $7.25 billion of free cash flow, net debt at 8.1 times EBITDA, term loans at 11% to 15%, a weighted-average short-term borrowing rate of 12.3%, and a $1 billion private placement in April 2026 at 9.75%.
Meta's Hyperion campus in Louisiana is financed through a special purpose vehicle in which Blue Owl Capital holds 80% and Meta holds 20%, funded by $27.294 billion of senior secured notes at a 6.581% coupon maturing in 2049. The noteholders have no pledge on the physical data center. Their credit is Meta's promise to pay rent starting in 2029, plus a residual value guarantee. Twenty-seven billion dollars of debt, secured by a lease, sitting off the balance sheet.
And… like the EU’s finance minister explained two decades ago… “when it gets serious, you have to lie.”
Microsoft extended server useful lives from three years to four, then to six, adding about $3.7 billion to fiscal 2023 operating income. Alphabet did the same, adding about $3.0 billion. Amazon added about $2.5 billion in 2024. Meta added $2.59 billion in 2025. Oracle added $573 million. Every one of those is a non-cash increase in reported profit produced by an assumption about how long a chip stays useful. It’s a lie.
But not everyone is lying. Effective January 1, 2025, Amazon shortened the useful life of a subset of its servers and networking equipment from six years back to five, citing, in its own 10-K, "the increased pace of technology development, particularly in the area of artificial intelligence and machine learning." That cost it $1.4 billion of additional depreciation and $1.0 billion of net income.
Amazon is the operator with the longest and hardest-won experience running data centers at scale, and Amazon is the one telling you the hardware wears out faster than the schedules assume.
How could all of this spending possibly pay off?
Bain & Company's global technology report puts it at roughly $2 trillion of annual artificial intelligence revenue by 2030, and calculates that even if every dollar of on-premise IT budget shifted to the cloud and every dollar of AI productivity savings were reinvested, the industry would still be about $800 billion short. Sequoia Capital's David Cahn, who has been running the same arithmetic since 2023, has escalated his estimate from $200 billion to $600 billion to roughly $840 billion.
Against that: OpenAI's audited 2025 revenue was $13.07 billion, with an operating loss of $20.92 billion. Anthropic's 2025 revenue was $10 billion. Combined, $23 billion.
And of every dollar spent on Nvidia systems, roughly 72 to 75 cents is Nvidia's gross profit. Data center is now 88% of Nvidia's revenue. The margin is not in the build-out. The margin is in selling to the build-out.
What’s about to happen is obvious, because it has happened before.
Between 1865 and 1873 the United States built the most consequential physical network in its history and destroyed an enormous amount of capital doing it.
Track mileage went from 35,085 miles in 1865 to 52,922 in 1870 to 74,096 by 1875. Construction peaked at 7,439 miles laid in 1872. Railroad capital reached roughly $4.5 billion at a time when the entire banking system's capital was $720 million and the federal debt was $2.3 billion. In January 1870, of 896,596 shares traded on the New York Stock Exchange, 781,340 — 87% — were railroad shares. From 1870 to 1874, roughly 70% of all railroad securities issued in London were American. American rail bonds paid 6.5% when British consols paid far less, and European capital came for the yield.
Every argument you hear today was made then, too. The railroads will transform the country. Yep, they did compress distance and cost of transportation in a way that seemed impossible only a few years earlier. And it didn’t make any difference.
On September 18, 1873, Jay Cooke & Co. failed. Cooke had contracted to place $100 million of Northern Pacific 7.3% gold bonds, but sold less than $20 million. He ended up effectively owning 75% of the railroad he was supposed to be financing. And it failed. The New York Stock Exchange closed for ten days — the first closure in its history.
By 1876, 134 railroads were in default on $500 million of bonds out of roughly $2 billion outstanding. By 1877, 20% of American railroad track mileage was in receivership. European investors are estimated to have lost around $600 million between 1873 and 1879.
A very large fraction of the capital that built the American rail network was lost.
And where the roads survived, competition took the returns. Revenue per ton-mile fell from 1.88 cents in 1870 to 0.73 cents in 1900, a decline of about 61%. Rate wars on the New York-to-Chicago corridor drove the through rate from $1.88 down to 25 cents, then 20 cents, and no pooling agreement stabilized the worst of it until late 1885.
Every additional mile of track made the network more valuable to America and less valuable to the men who had paid for it.
The AI build-out will have the same problem – but it will be much, much worse. Compute will be a pure commodity.
Nobody disputes that the models are transformative. The problem is, that’s true of all of them.
Which of the second-derivative names Aschenbrenner owned has route control, like a monopoly railroad? Bitcoin miners with retrofitted substations? Rented compute resold at a spread? Memory, an industry that has never once earned its cost of capital through a full cycle? Those are not toll booths. Those are the Northern Pacific just before bankruptcy.
The railroads made a fortune – but not for their investors.
Adams Express Company was incorporated in 1854 with $1.2 million of capital. It did not own a single mile of track. It bought space on other men's trains and moved parcels, money and valuables on them. By 1866 its capital was $10 million and it was paying an 8% dividend quarterly. By 1875 its capital was $12 million. It paid an unbroken $8 per share annual dividend from 1869 forward — straight through the depression that put a fifth of American rail mileage into receivership, and straight through the next one in the 1890s.
American Express Company (NYSE: AXP) declared a $6 dividend in 1869, cut it to $3 in the depression year of 1877, restored it to $6 by late 1881, and held it there for the rest of the century. An 1888 board report showed ten-year net earnings of $26.24 million.
By 1890, the express companies were handling more than 115 million packages a year over 174,535 miles of railroad and steamship routes. And they didn’t own a single locomotive or a single boat.
Pullman's Palace Car Company was organized in 1867 with $1 million of capital. It did not own track either. It owned the sleeping cars and leased them to the railroads. Capital grew to $36 million by the early 1890s with nearly $25 million of accumulated surplus. Dividends ran 9.5% to 12% from 1867 to 1871 and 8% annually for decades after. In 1879, with 464 cars out on lease, it earned gross revenue of $2.2 million and net profit of almost $1 million.
Pullman put out $1 million of equity and earned $1 million a year on a network that cost other people billions and bankrupted a third of them.
Adams Express converted itself into a closed-end investment fund in 1929 and is still listed today as Adams Diversified Equity Fund (NYSE: ADX). The company that rented space on the railroads outlived almost all of them.
I’d bet a lot of money that Leo had never heard of any of these businesses.
But for people who are experienced in putting capital at risk, the pattern is not subtle or hard to understand. When an economy builds an expensive new network, the capital that builds the network earns a poor return because competition, obsolescence and overbuild strip it away. The businesses that ride on the network at near-zero incremental capital cost, and that own the customer relationship, the data or the standard, keep the profit.
I’ve seen this entire act before, during my career.
In the five years after the Telecommunications Act of 1996, carriers poured more than $500 billion into fiber, switches and wireless networks. By the early 2000s no more than 2% of North American long-haul capacity was in use. Global Crossing raised roughly $20 billion, built 100,000 miles of undersea fiber, filed for bankruptcy in January 2002, and saw its assets change hands for about $250 million — roughly 1.25 cents on the dollar of invested capital. WorldCom filed six months later, at the time the largest bankruptcy in American history.
Who got the value? Google, Amazon and Netflix, which built businesses on top of bandwidth that had become nearly free because somebody else had already gone bankrupt providing it. By 2018 and 2019, Google and Facebook were funding roughly four of every five dollars of new transatlantic cable investment — buying the rails only once the rails were cheap and only once they owned the applications that made the rails worth owning.
Leopold Aschenbrenner is not stupid. He is the opposite of stupid, which is part of the problem. He is a brilliant technologist who has never had to make a payroll, never had to explain to an auditor why the electronic records changed, never had to decide whether to spend eighteen months and $40 million ripping out a working system to save $200,000 a year in license fees.
He looked at enterprise software and saw code. A businessman looks at enterprise software and sees the thing his company cannot operate without for a single day, priced at 1% of the employee who uses it, backed by a validated audit trail he would have to rebuild from scratch in front of a regulator, and running on a contract he signed for three years.
An investor who has read a balance sheet from 1874 sees $220 billion of annual capital expenditure, an 8-times-levered reseller of rented compute borrowing at 12%, $27 billion of data-center debt hidden in a special purpose vehicle, and useful-life assumptions that the most experienced operator in the business is quietly walking back.
The kid believed the technology determines the return. But it never has.
It’s the capital structure that determines the returns: who controls the standards, who controls the customer, and who owns the data? Yes, the A.I. models will change everything. But that does not mean the people building the machines will be paid for it.
The money will be made where it was made in 1874 and again in 2004: by the toll booths riding on top of somebody else's ruinous capital expenditure.
Japan is the canary. Nobody is listening.
For thirty years Japan ran the largest monetary experiment in human history. Zero rates. Yield curve control. A central bank that ended up owning roughly half its own government bond market. The theory was that a sovereign borrowing in its own currency faces no real constraint. For three decades the theory held, and every trader who bet against it got carried out on a stretcher. They called it the widowmaker.
The widowmaker is collecting now.
Debt above 200% of GDP. The 10 year JGB touched 2.91% last week, the highest in thirty years. The policy rate sits at 1%, a level last seen in 1995. Debt servicing in the fiscal 2026 budget hit 31.3 trillion yen, roughly a quarter of the entire national budget, and the Ministry of Finance now assumes a 3% bond rate, the highest assumption since 1997. Social security and interest payments together consume close to 60% of all government spending.
Six of every ten yen Tokyo spends now goes to promises made in the past. The remaining four have to cover defense, education, infrastructure, and everything else a modern state is supposed to do.
The yen sits at 163, a 40 year low. Japan burned roughly 11.7 trillion yen defending it and bought a few weeks of relief. This is the trap they built for themselves. Hike enough to defend the currency and the interest bill detonates. Hold rates to protect the fiscal position and the currency keeps bleeding out. Japan imports 90% of its energy and 60% of its calories, so every tick of depreciation lands directly on the grocery bill.
Now the part almost nobody models correctly. Hyperinflation is a distraction. Four percent for fifteen years cuts purchasing power roughly in half, and it arrives so slowly that no single year ever registers as a crisis. There are no wheelbarrow photographs from a 4% decade. There is a retiree in 2041 who did everything right and is poor anyway.
The Japanese saver pays for this twice. Thirty years of zero rates already moved wealth quietly out of household balance sheets and into the state's. Now the debt those zero rates financed gets inflated away in real terms while consumption taxes climb and benefits get quietly trimmed. A bond issued at 0.2% rolls at 3%, and the gap comes out of somebody's standard of living. Extraction, spread thin enough that nobody can point to the day it happened.
Now look west.
US publicly held debt is at 99% of GDP, the highest since 1946, and the CBO baseline puts it at 120% by 2036. Net interest runs from about 1 trillion this year to 2.1 trillion by 2036. The number that should keep you up: the primary deficit, excluding interest, actually declines over that window, from 2.6% of GDP to 2.1%. The entire deterioration is interest compounding on itself. CBO's own baseline has the average rate on the debt crossing above the growth rate around 2031, the threshold where the arithmetic stops correcting itself and starts feeding itself.
The 30 year is at its highest since 2007. The Fed just held with three members dissenting in favor of a hike. And Japan, sitting on 1.19 trillion of Treasuries as the largest foreign holder, sold nearly 30 billion in the first quarter alone. When domestic bonds pay 2.8% with no currency risk attached, Japanese insurers have no reason to own American paper. The most reliable marginal bidder in the world is packing up and going home.
Central planning dies slowly. It ends as a grinding transfer from everyone who saved to everyone who borrowed, administered by people who will call it stability the entire time it is happening.
Japan is fifteen years ahead of us on this road. Everything happening to them is a broadcast from our own future, running in real time, with the sound turned off.
Leggendo i giornali, mi chiedo quanto devono essere brave quelle persone che, nonostante questa indecente cagnara, continuano a far andare avanti il Paese.
Domani, domenica 14 giugno, dalle 8:55 @micheleboldrin in diretta a Omnibus su La7 per discutere di come costruire un'alternativa politica credibile per l'Italia, delle sfide che il Paese ha di fronte e delle proposte necessarie per affrontarle.
Grazie ad Alex Pineschi 🇮🇹 per aver onorato il nome dell’Italia, Paese che come oggi l’Ucraina 🇺🇦 ha avuto bisogno di uomini coraggiosi per cacciare l’invasore.
Bisogna sempre ricordare al maiale del Cremlino che oltre ai Vannacci, tra noi ci sono patrioti veri.
Poland, Baltic states, now Romania. More and more Russian provocations. Yesterday the former president @MedvedevRussiaE said that the peaceful sleep of the EU citizens is over. Everyone in NATO should finally start taking these facts and words seriously.
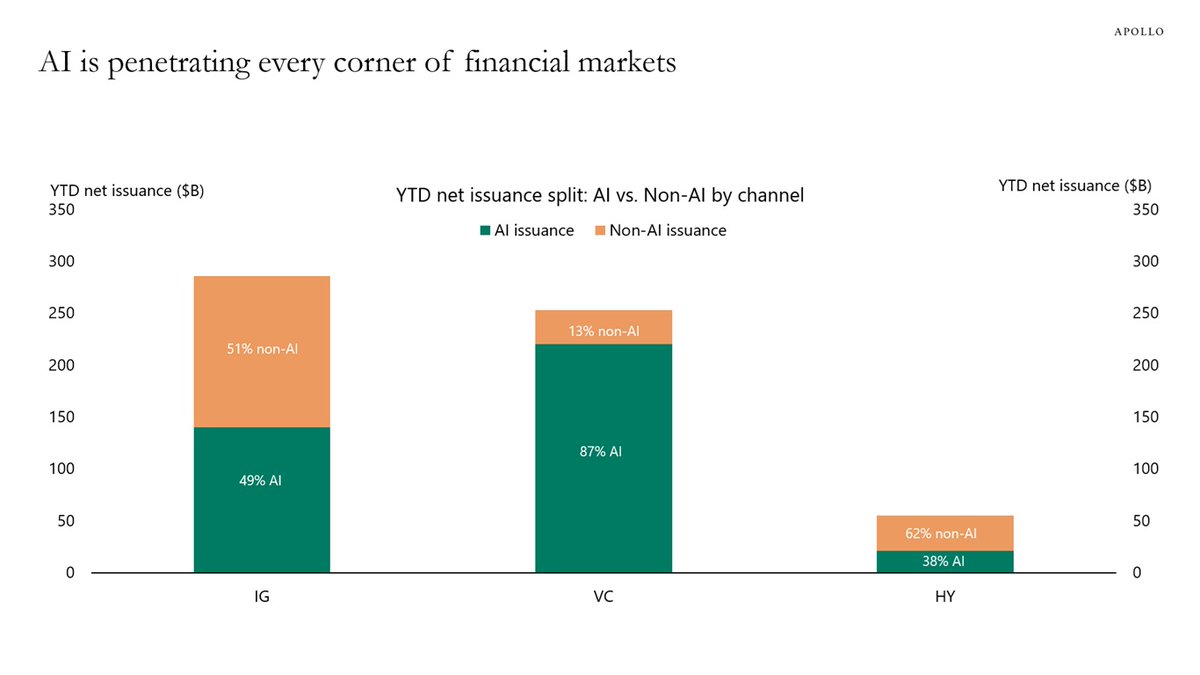
L'incidenza del settore AI nelle emissioni di debito investment grade e high yield e nei funding di venture capital è sempre più pervasiva. Con tutto quello che ne può conseguire, ovviamente
(Via Torsten Slok)
Oftentimes, I read from retail traders dismissive comments about risk manage(ment|rs). Risk management is the most useful skill you can learn when trading on your PA or managing a $3b book (and it’s learnable). And a good Chief Risk Officer is the 2nd most important and useful person in a top hedge fund. I know, it’s obvious. But in years like this, a good self-reminder.
Questo brano di Hermann Hesse è sempre stato per me una guida e un faro. Spero di aver almeno provato ad applicare nella mia vita queste meravigliose parole.
FT Exclusive: Chinese investors are using opaque structures known as special-purpose vehicles to invest in Elon Musk's companies. This way, they conceal their identities to avoid the ire of US authorities and companies wary of Chinese capital https://t.co/HI9TYKCdpl
💬PM @DonaldTusk in Parliament: Poland must pursue the most advanced capabilities, including nuclear and modern unconventional weapons. This is a serious race - a race for security, not for war.