We are currently studying and analysing 2000+ companies
CONCALL TRANSCRIPT AND INVESTOR PPTS
Accurate data like FY26, FY27
- Revenue guidance
- Revenue growth
- PAT guidance
- Capex
- Expected orders
- Current order book
is being uploaded on https://t.co/8g8pe8iGjT portal
#Krishna defence & allied
> One of the debt free, clean shipbulding proxy
> High value, high moat, high margin products
> Revenue would grow in proportion with shipbuilding industry
> high certifications, have few competitors
> One of the only two players approved for buld bars in Indian navy
> Only player to be approved for bulb bars in commercial shipbuilding
> Have multiple new initiatives, almost 6-8 new MOU, JV, products which will boost revenue in next 12-24 months
> New products - ammunation components, aerospace components, composite ship doors, Autonomous Underwater Vehicle (AUV), underwater weld consumables, smart ammunation
> 25-27% EBITDA, 20% PAT, zero debt
> can give 30-40% growth for 3-4 years, still at 40PE
> If you want to look at shipbuilding today, i see it by far the best company
> small mcap company so can grow hugely
If you want to study one mainboard company, in defence, in shipbuilding, with great growth, decent valuations
Do study #krishnadef today!
If you get it, you get it😎
My picks for Diwali 2027 (updated)
Krishna defence
Rappid Valves
Apollo micro
Note:
Removed Viviana power as it a medium term opportunity, rather than long term for me now
These are all my personal opionion, no buy/sell advice
I am downgrading Viviana power tech from long term opportunity to Medium term opportunity
Reasons:
1. Constant need of funds every half year for operations
2. Debt and interest will go up for near future
3. Further revenue boost in next years will come from bigger projects which will have lower margins, confirmed by management in concall
4. I see no clear vision of BESS, earlier they were buying battery packs and owning the complete project, i asked for clear IRR, but never got any answer in concall or in any ppt.
Now they are saying BESS is only EPC play, no clarity to me
5. Establishing subsidiaries like Viviana life spaces was unnecessary and confusing from the start.
Earlier they justified its existence by saying its collateral, i though its fine.
Now the subsidiary is sold. Complete lack of logic to me
6. The bigger rerating electrical equipments is atleast 1.5-2 years away from operations
Good things (why it's a medium term opportunity):
1. They are constantly growing revenue mostly and beating guidance
2. Hired professional management who can handle complex operations as operations scale
3. Already diversified in transformers and growing there
4. Future plans for electrical equiment shows management is aware, only EPC isn't enough for future growth
5. Promoter is smart and capable can execute at scale
So, it's a medium term opportunity now
Notes:
Long term [LT] - Having possibility of multibagger alpha in 3-5 years, company has growth potential for multiple years as per data
Medium term [MT] - Having possibility of significant returns in 1-2 years, beyond 2 years there isn't sure shot visibility right now, or it's a medium term growth candidate rather than multi year growth candidate as per data
These are just my views, might be a bit here and there also😊
Views changed after listening to last 3 concalls, management replies, company debt levels, few other things
Long term [LT] and Medium term [MT] opportunities
Apollo micro - LT
Krishna defence - LT
Rappid valved - LT
Viviana power - MT
Igarashi motors - MT
Eimco elecon - MT
Texmaco rail - MT
Long term [LT] - Having possibility of multibagger alpha in 3-5 years, company has growth potential for multiple years as per data
Medium term [MT] - Having possibility of significant returns in 1-2 years, beyond 2 years there isn't sure shot visibility right now, or it's a medium term growth candidate rather than multi year growth candidate as per data
Note: I share data for fun, no buy/sell reco.
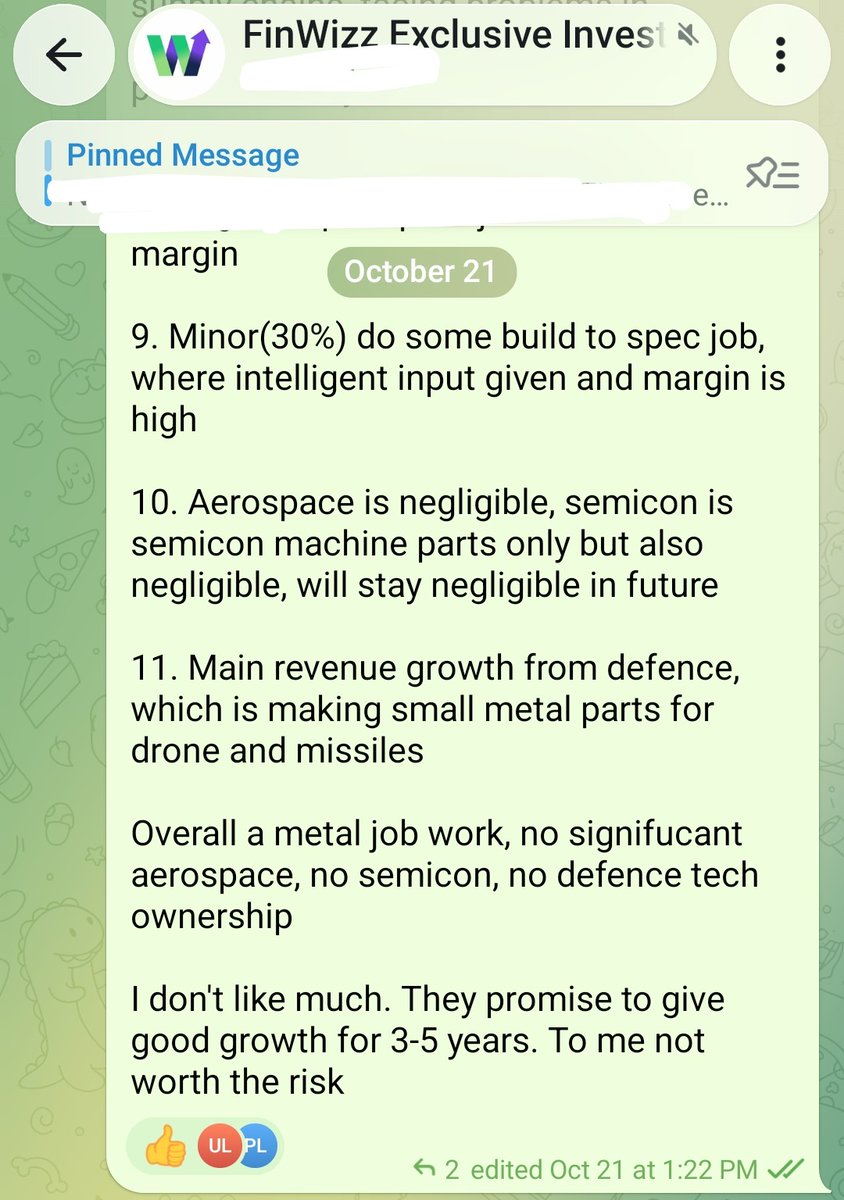
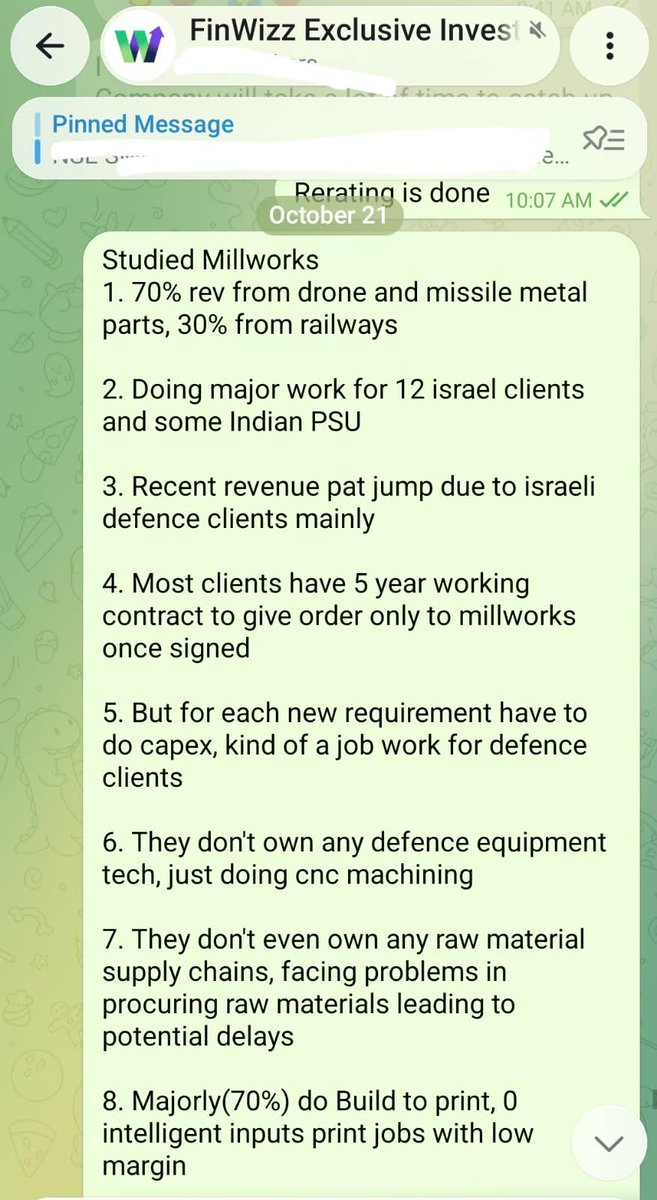
#Millworks Technologies
My notes in FinWizz discussion group
I usually don't put negative views on twitter,
only good companies i discuss on twitter
people start bashing you for writing negative reviews,
so i avoid it mostly
#Apollo micro systems maked a new ATH😎
But i would advise to just watch and enjoy,
don't enter in FOMO
Stock is great but price is also good
Just a nudge, No buy/sell
I don't know how high it can go in medium term,
i only look at long term story
My advice is for long term investors😎
Traders can do what they want😅
My picks for Diwali 2027
Krishna defence
Rappid Valves
Apollo micro
Viviana power
I am studying tens of hundreds of company every month, but the old and tested ones i like more
> Consistent multi year growth in future despite having good past growth
> Strong sectors, great products
> All are 10+ year old co's
> Great promoter, smart, startegic, hard working
> Proven execution, lower risk, medium reward
Only Rappid has yet to prove good execution
So, its a high risk, high reward and only SME in list
Rather than new and exciting names, I am aligned towards the proven names as my number one priority is risk management, then reward
As, i am completing 6 years in market, i have seen hundreds of retailers go broke
To make a bigger potfolio you need to survive and survive
So manage risk, stay in multi year growth sectors, choose gold standard promoters, then look at rewards
Happy Diwali and best of luck!
#Apollo micro systems
Rev up 72% YOY ⬆️
PAT up 53% YOY ⬆️
Krishna defence and allied
Rev up 55% YOY ⬆️
PAT up 70% YOY ⬆️
#Viviana power tech
Rev up 98% YOY ⬆️
PAT up 100% YOY ⬆️
#Viviana power tech
Q2 FY27
Revenue up 98% YOY
PAT up 100% YOY
While bulk of yearly revenue will come from H2
The growth rate 100% is above the management projections of 70%
PE as of today is 12.5, after FY27 results it will be 8.5
Socho ab kya kare😇😎
Precision engineering and aerospace ke naam pe
Casting, forging, cnc machining ki companies ko
50-150 PE pe buy karne waale savdhan rahe
Like i warned about solar sector esp solar epc in 2024,
when euphoria was at peak, people were abusing me,
now the sun is set there
Yaha bi abi thoghless investing chal ri hai,
The sun will set here soon
I am studying many of the popular so called aerospace and precision engineering names,
till now most of them don't have high value precision engineering
Even companies making aerospace components have low complexity, low value, low margin, small TAM but valuations are running at speed of light
It's not very easy to figure out an actual precision engineering or aerospace components maker which is undervlaued
But, it's super easy to not invest in stupidity like a :
> company buying CNC machines, setting up in a factory and calling in precision egnineering
> company doing some aluminium casting, making door handles, some small steel frames for passanger seats and calling it aerospace components
> Some companies are making parts on order without owning raw material supply chain, without owning and tech, any IP, just making stuff on orders, close to zero moat, still people are loading them
Krishna defence and allied
Q2FY27
Rev +55% YOY
PAT +70% YOY
Future revenue growth 30%+ for next 3-5 years
With a PE of 35,
entering into multiple new products in
> aerospace components with AS9100D Certification
> new shuipbuilding special metals
> commercial shipbuilding in addition to naval
> welding consumables (underwater)
> Autonomous underwater vehicle
> underwater robotics
> Naval ammunation
> Tank armours
> RF receiver and naval comunication systems
> Ship composite doors and hatchets
Great management, delivering consistently
The revenue, pat, stock price all can compound at 30% for 5 years
Now do the maths😎
#KRISHNADEF is one of the under discussed and under owned hidden shipbuilding compounder
If you want stocks to study,
which can have a good future,
I won't give you new ones
I will again suggest the same old ghise pite names
Krishna defence : if defence is bullish for years, shipbuilding will be structurally bullish for decades, Shipbuilding is like making trains for the sea, and India is doing it seriously for first time ever.
Rappid valves : Again major shipbuilding beneficiary, with diversification in other industries also.
Can be a chota packet, bada dhamaka. Or Chota packet, chota dhamaka, time will tell
Go study and have fun!
#Rappid #Krishnadef
Note: No buy/sell. Take you call as per your understanding
#Apollo micro systems
Q2 FY27
✅ Highest ever REVENUE
✅ Highest ever EBITDA
✅ Highest ever PBT
✅ Highest ever PAT
✅ Highest ever EBITDA MARGIN
✅ Highest ever ORDER BOOK
Kaise kar lete ho ye sab😎
They have 1765cr order book even after executing the highest revenue
And those 3000-8000cr of anticipated orders haven't arrived yet, wow💥
Have been lucky on finding this one early, grateful🙏
#Apollo micro systems
Standalone
Rev up 36% YOY
PAT up 45% YOY
Consolidated (incl IDL)
Rev up 72% YOY
PAT up 53% YOY
Because IDL is adding lot of revenue and not much profit
Overall a great show, one of the best defence company for next 3 years atleast
Note:
No buy/sell reco