“Aku dapet 20 Hokben. Bukan Hokben yang kaleng-kaleng gue dapet ya, Hokben mahal! Nah, jadi ada yang ngambil nih, siape enih. Di Nusanatara 2, di lobi. Eh Anton di mana Anton, coba lu, coba lu telfon Anton!”
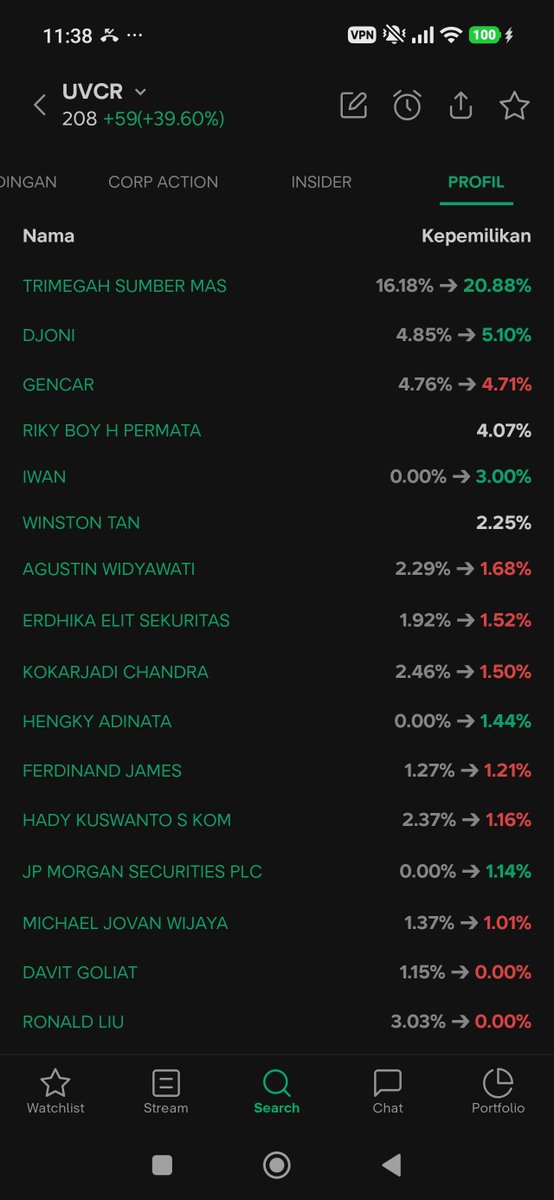
UVCR IJ = TELE IJ 2.0 ?
Same (Different) Henki ?
Another SandBagging By So-Called Finfluencer Group Flow?!
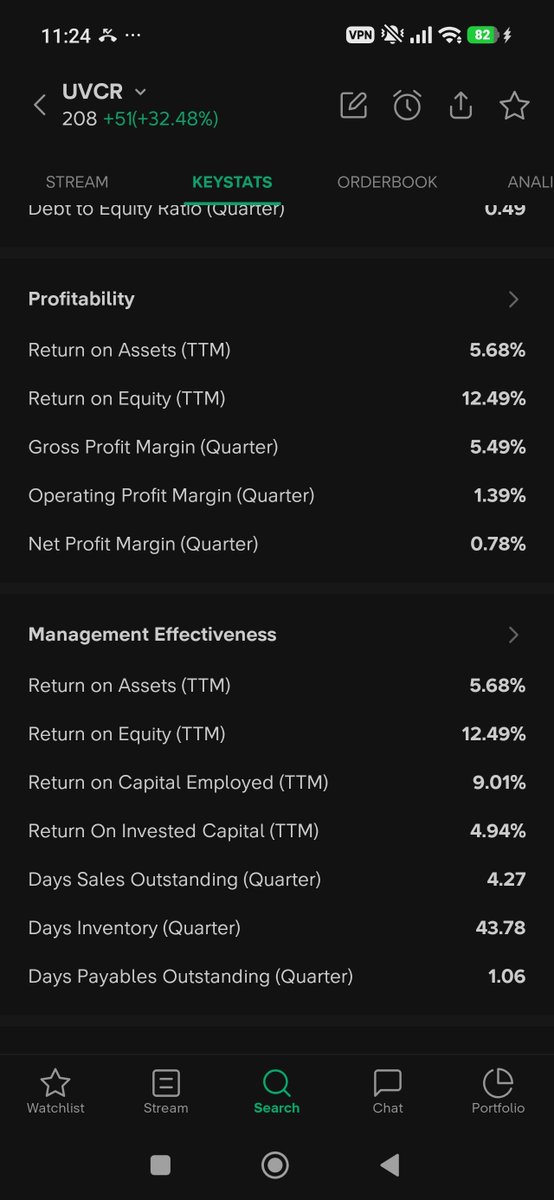
*Razor Thin Margin (NPM below 1 pct)
Those Thin Margin is At Perspective Should be Contested against Int-Expense / Working Capital Trend
(Real Rate Via Govt Yield already Up +50Bps, BI Rate is expected to Follow)
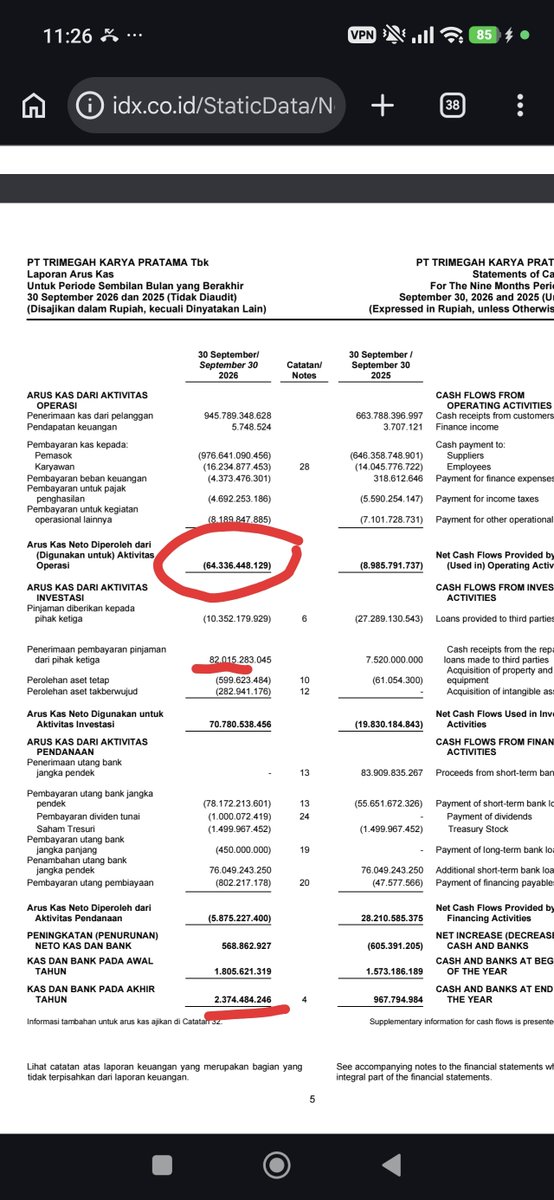
Red Flags yg kejadian Waktu TELE got killed was ;
Revenue naik kenceng + OCF Minus + Persediaan Naik + Aging Piutang 90 Days ++ Naik + Int Bearing debt Naik with Rate yg makin mahal
Slip Aging Turnover Days / Obsolete Persediaan sedikit against rate would kill em..
Really 4X Book & 30X EV/Ebitda ??
at this Int Rate Regime, at this Quick Ratio Level, at market FCF yield comparing..
Aah i might see the wrong Henki
*Henki Tiphone would gladly arouse from whichever Thousand Island Resort He Reside!
I don't think we're going to see an '87-style crash in percentage terms, but today could set the stage for some form of market meltdown that could potentially last a week or two. If the decline picks up steam, throw your oversold indicators out the window. My guess would be $SPY 10%-15% from peak with 20% as a worst case. Nasdaq could drop 20-25%. Possible 1998 cyclical bear market.
Several investment banks have already said the same thing.
History shows most markets on MSCI’s watch list end up downgraded.
Turkey is the exception so far.
Its regulator shut down 130+ funds in one day, and 85 people were detained within weeks.
Indonesia has announced reforms, but we have not seen enforcement yet.
I’ll believe it when I see it.
So, stop debating the downgrade.
Plan for Standalone.
Decide your portfolio allocation NOW, before the decision forces it.
If the downgrade doesn’t happen, consider it a bonus.
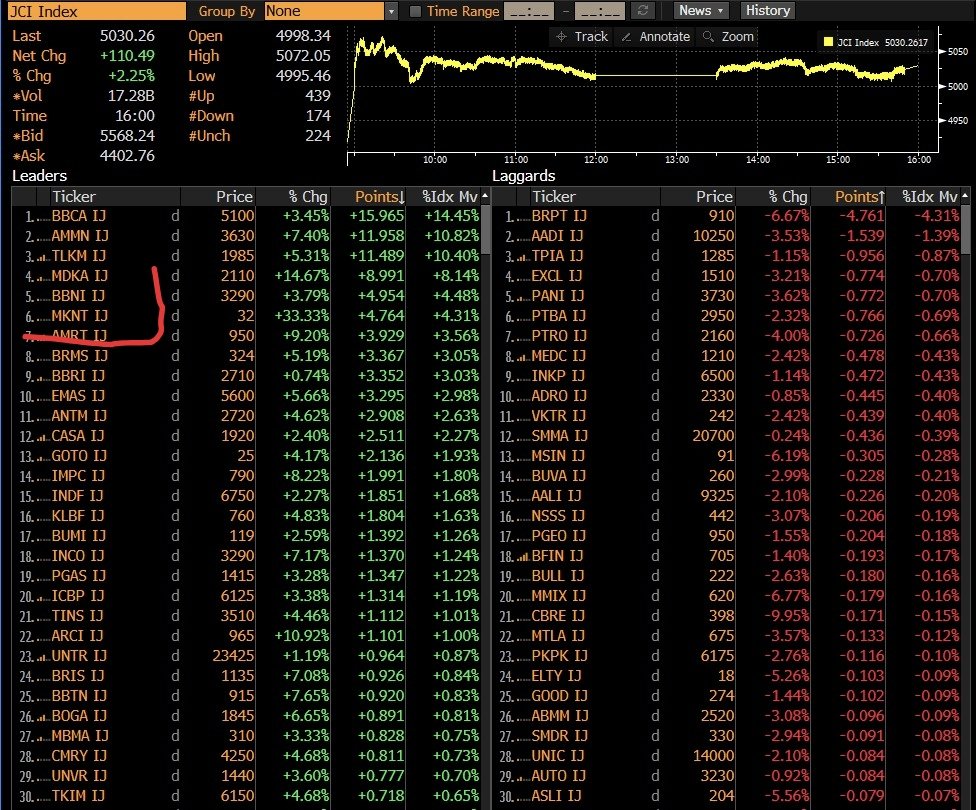
Market Impact Setara BBNI dam diatas ANTM.. lusa besok setara TLKM
Dan @ojkindonesia masih berkomentar Akan Tegas pada "Market Manipulation"
@IDX_BEI Surveillance System ala Nasdaq udah bayar subscription?
@Danantara_ri Beauty Contest Project WTE anda sudah pasti bocor duluan kah awarded / Equity Portion dan Project Debt Financing nya Siapa? Untuk reverse balik Equity Project Value di Market Cap Impact IHSG se vulgar ini?
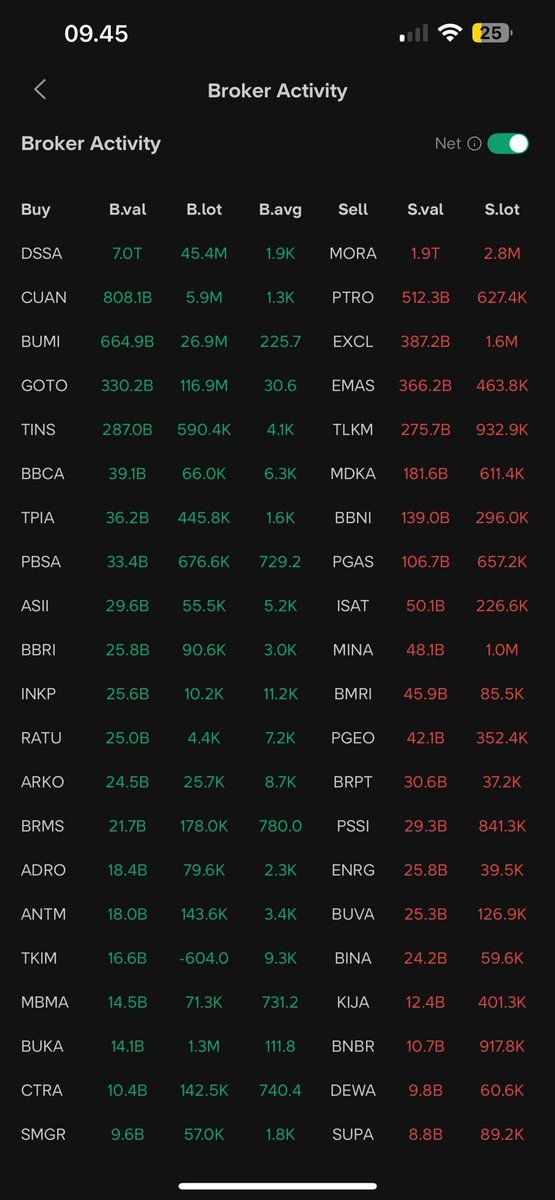
🇮🇩 JUST IN: Bloomberg reported that the Chief Investment Officer of Danantara Indonesia, Pandu Sjahrir, indirectly owns 27.5% stake in Supra Sekuritas (SS), which is recently sanctioned by OJK in relation to stock-market manipulation case.
Based on data from Stockbit, Supra Sekuritas top net buy this year in all market are $DSSA, $CUAN and $BUMI.
There is an interesting market rumor circulating that Bank DBS Indonesia could be merged into $BBCA through an inbreng (non-cash capital contribution) transaction, with BCA remaining the surviving entity and the DBS shareholder receiving newly issued BBCA shares in exchange.
This is what I heard as one possible explanation for BBCA’s sharp rally today, reportedly reaching approximately 7% at the time of writing. To be absolutely clear, this is an unconfirmed market rumor, not an announced corporate action.
One important clarification on the ownership structure: DBS Bank Ltd. currently owns 99% of Bank DBS Indonesia, while BCA already owns the remaining 1%. Temasek is a major shareholder of DBS Group, so any share-for-share transaction would involve the relevant DBS entity rather than automatically converting a directly held Temasek stake into BBCA shares.
Now, does this transaction make economic sense?
Strategically, I can see the rationale. DBS Indonesia has an established corporate banking, treasury, wealth management and institutional client franchise, which could complement BCA’s exceptionally strong domestic deposit franchise, payments ecosystem and retail distribution network. Combining the two could create opportunities in corporate lending, transaction banking, cross-border financing, wealth management and fee-based income.
However, the financial contribution would be relatively modest. DBS Indonesia generated approximately Rp1.72 trillion in net profit in FY25, compared with BCA’s Rp45.2 trillion in the first nine months of 2026 alone. On a simple annualized basis, DBS Indonesia’s earnings would represent less than 3% of BCA’s existing profitability, before any synergies or adjustments.
Therefore, I struggle to see how this transaction alone would fundamentally transform BCA’s earnings trajectory or justify a substantial valuation re-rating.
The more important questions concern the transaction structure and exchange ratio. At what valuation would DBS Indonesia be contributed? How many new BBCA shares would be issued? Would the transaction be earnings-accretive after dilution? What would happen to BCA’s ROE, capital adequacy and cost-to-income ratio? And perhaps most importantly, why would DBS Group want to give up direct control of its Indonesian banking operations in exchange for a minority stake in BCA?
That last question is particularly interesting because DBS Indonesia remains profitable and DBS only recently strengthened its Indonesian financial conglomerate through its securities business.
Of course, an appropriately priced transaction could make sense for both parties, particularly if DBS values exposure to BCA’s franchise more highly than maintaining direct control of its Indonesian subsidiary.
But without knowing the proposed valuation, ownership structure, expected synergies and strategic intentions of both shareholders, I would not automatically interpret the rumor as bullish for BBCA.
A good acquisition is not simply about acquiring a profitable business. It is about acquiring that business at a price that creates value for existing shareholders.
For now, I would treat this as speculation until we see formal confirmation from BCA, DBS or the relevant regulators.
Interesting rumor, though. Let’s see whether there is any substance behind it.
Hehe yang di denda masih 3 doang
Padahal kita tau banyak yang harusnya kena juga
Jadi buat yang gamau mengakui coordinated trading, bilang YPC lah bla2
Bersyukur aja bukan dirimu yang dikirim hadiah ☺️☺️
Jangan ngotot, two wrongs don’t make a right
Baca tuh press release nya biar ngaca
The claim by Indonesia former trade minister Muhammad Lutfi that Singapore is controlling MSCI to hurt Indonesia’s stock market is so retarded.
$MSCI is an independent American company.
Singapore’s Temasek only owns a tiny fraction of its shares (less than 1%). That does not give them the power to tell MSCI what to do.
MSCI has clearly explained why it’s looking at Indonesia’s market status:
1. Problems with unclear share ownership
2. Suspicions of coordinated trading
3. Reforms that haven’t shown strong enough results yet.
These concerns started earlier this year. MSCI warned about them in January and again in June. These issues have been discussed for months, not something that suddenly appeared because of Singapore haze situation.
The specific person from GIC who was named has no public record of being in a position to ‘pressure’ MSCI, and no evidence has been shown to support that claim. Plus GIC does not own MSCI.
Instead of looking for foreign plots, the focus should be on fixing the transparency and trading issues that MSCI have already pointed out.
Indonesia is turning to an unexpected source for help explaining MSCI's downgrade threat to its populace: social media influencers. Read more: https://t.co/ilenW7WAOx
📷️: A screenshot of a video from YouTube of Leon Hartono discussing the threat of an MSCI reclassification