I believe $CMCSA Universal Orlando parks are in much need of some major capex, otherwise will see attendance issues. There are 3 $CMCSA theme parks in Orlando: Islands of Adventure, Universal Orlando, and Epic Universe.
At Islands of Adventure - only 2 rides are < 10 years old. Many of the rides are > 20 years old and its evident. Islands is split into 8 themed "islands". Besides the Harry Potter area (specifically Hagrid Motorbike) and Jurassic's Velocicoaster, the rest of the park is very outdated, under construction, or in refurbishment. It's not worth the $125/day.
Universal Orlando is in worse shape. Many of the newer rides are screen related. The last fully non-screen ride created was The Mummy (2004). The 2018 Fast & Furious ride was widely disliked, closed, and thankfully they are building a F&F coaster (2027 open). All rides open in the last 10 years are using screens only.
Epic Universe is a good addition, but it is ~10 minutes away, and also a good "one day park", meaning it will need to expand, and in order to Universal to maximize the whole ecosystem of staying for multiple days, they will need to upgrade or build quite a few new attractions at the original parks in the next few years.
@ScottGustin Problem is so many parts of Universal in Orlando are under construction. Epic Universe seems too small still, can knock it out in a day, easily.
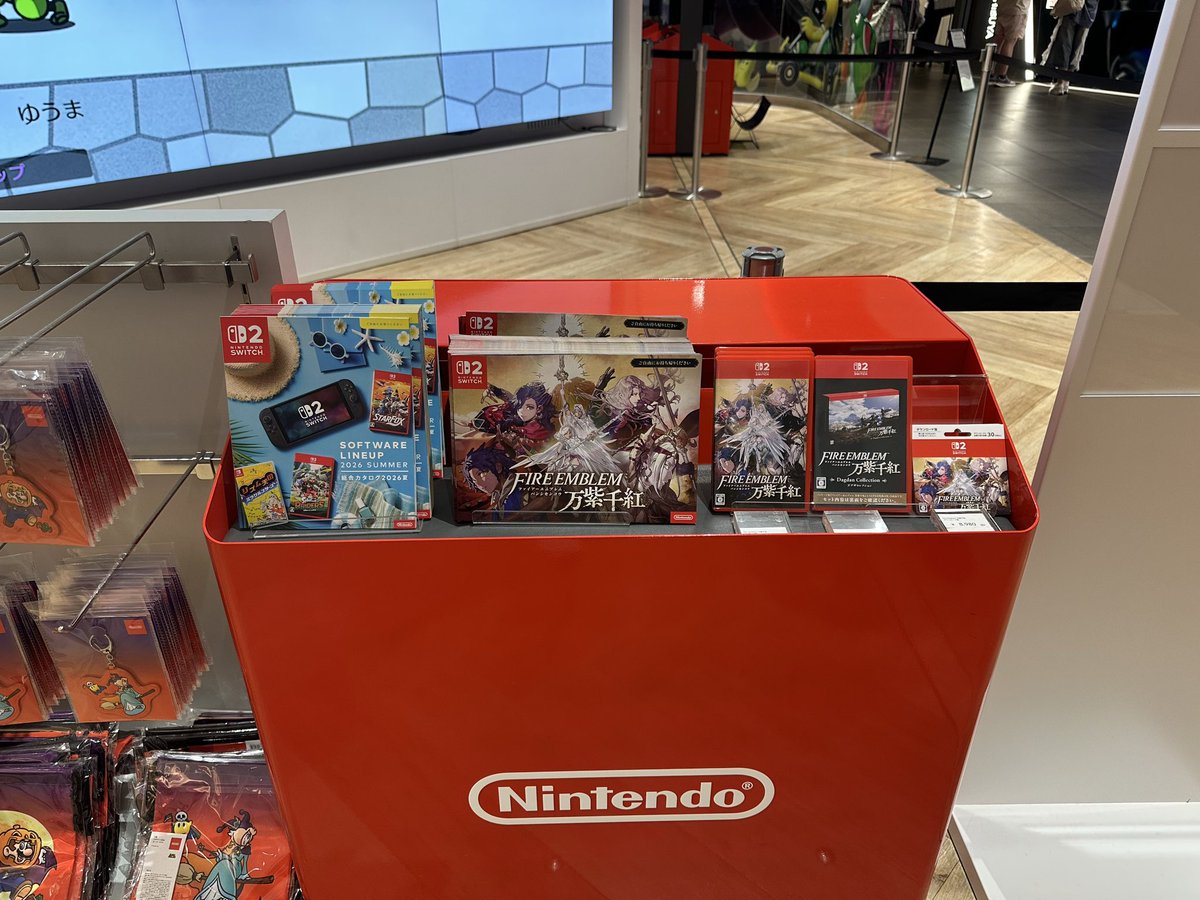
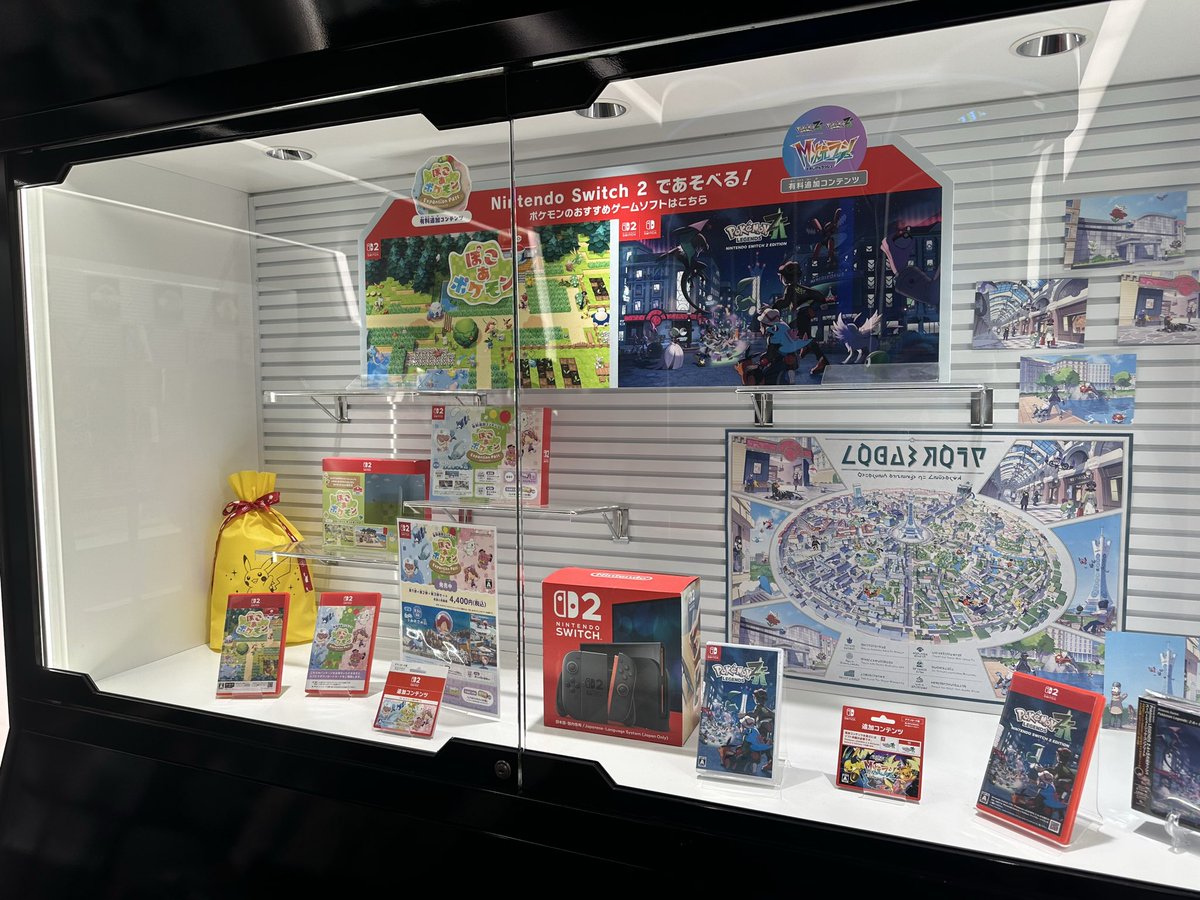
Talking to $NTDOY stores in Japan, they seem to think the releases of Fire Emblem and Ocarina of Time will propel sales of the Switch 2 even higher due to popularity they are seeing.
$NVDA (Barron's)
"So, an Nvidia-backed AI developer is renting computing capacity from an Nvidia-backed cloud provider, using an Nvidia-leased data center that will be filled with Nvidia’s hardware."
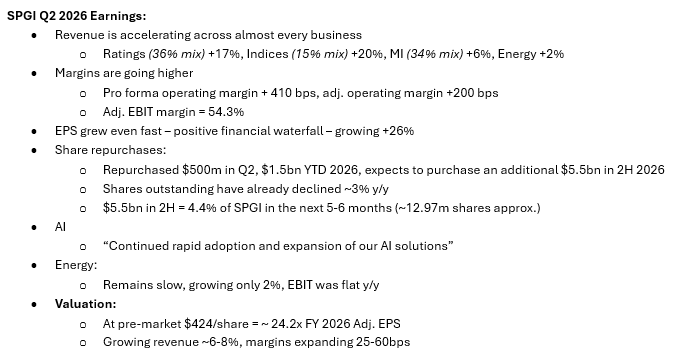
$SPGI Q2 2026:
- strong positive financial waterfall (revenue +10%, EBIT +17%, EPS +26%)
- will repurchase an additional ~4.4% of market cap by year-end
- trading at ~24x 2026 EPS with EPS growing >20%
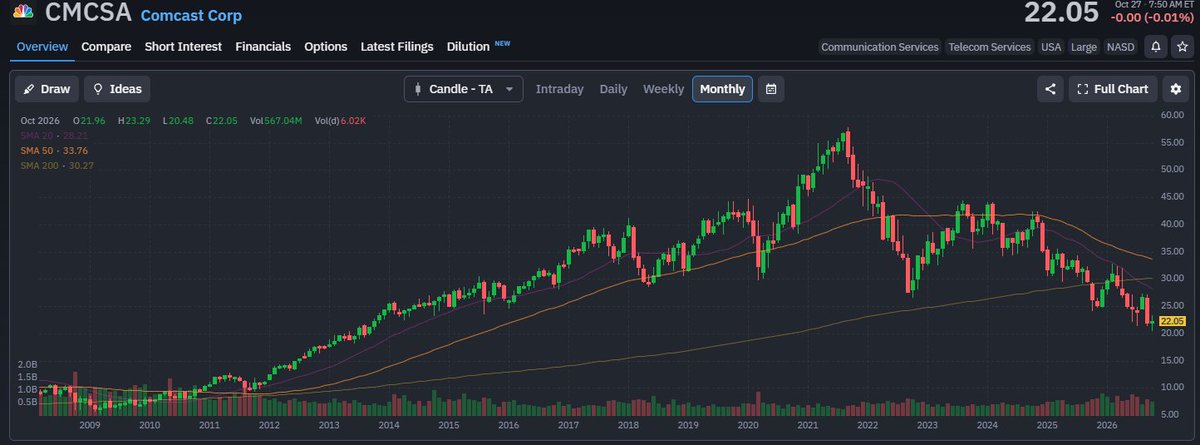
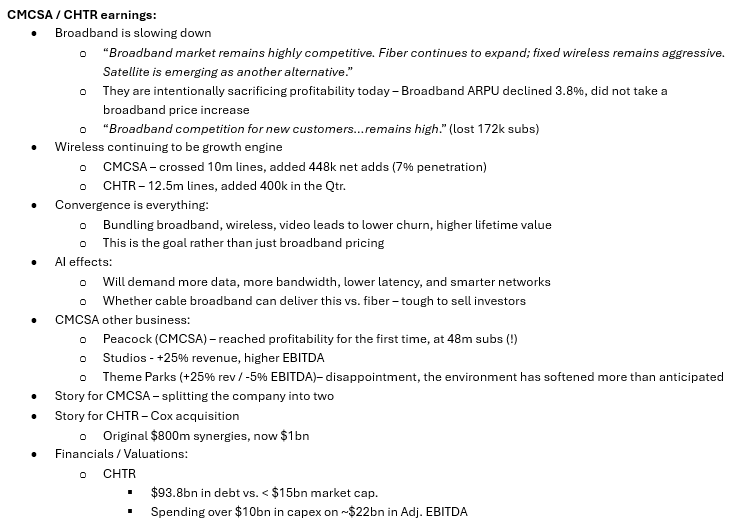
After going through $CMCSA & $CHTR earnings, some points:
- no pricing power in broadband, the "core offering", and as household passing increase, still lowing subs, despite not taking pricing actions
- doing better in wireless (but still competitive)
- goal is lower churn, bundling, convergence
- $CHTR has < $15bn equity but ~ $108bn EV
$GOOG Cloud margins include: GCP infrastructure, Workspace and other enterprise software, consumption-based Cloud, subs, TPU sales...
Excludes shared AI R&D, compensation for general AI-model development, tech-inf. usage for developing general Ai models. These are in "Alphabet-level".
If GOOG spends billions training Gemini, some reasonable portion of that should economically be in Cloud expenses.
GOOG just started selling TPU systems, so possible large upfront revenues from this (contra: CFO said Cloud growth accelerating even excluding TPU system sales)
Possible that $GOOG is permanently turning into a capital-intensive company.
With AI revenue growth + incredible capex spend, will there be adequate ROIC?
- possible that while search monetization rises, user trust deteriorates (GOOG experimenting with sponsored links, contextual ads, direct offers...AI answers blend synthesis and recommendation priority)
- Alphabet began selling TPU systems in Q2: could create large upfront revenues but be low / no margin. Management *did not* disclose TPU margins.
- Planning to expand the use of 3rd party capacity while they build more internal capacity
S&P Global on AI:
- they think private AI funding has probably peaked, moving now to public
- AI infrastructure is still ramping up, from $700bn in capex in 2026, $850bn in 2027...
- copper is the backbone of the data center; no way data centers can deliver enhanced computer power without copper wiring - think there's more upside to Copper
- huge growth opportunities for AI adoption: average company still spends $11 per user on AI tools, equal to a NFLX subscription
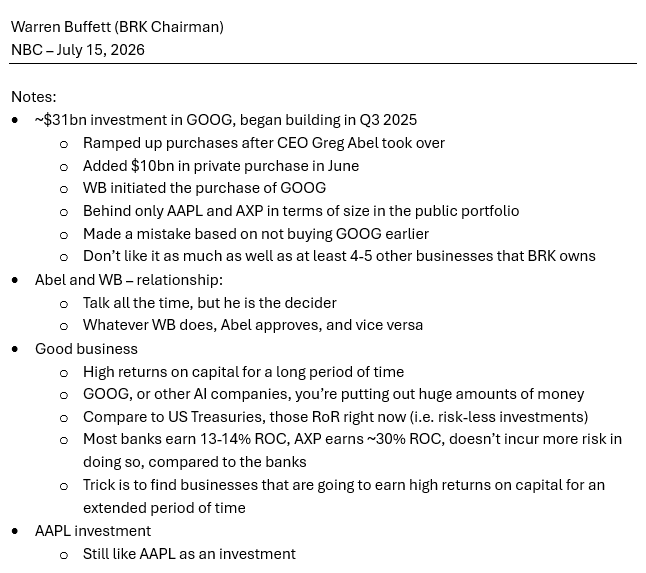
@MichaelGielkens To me, this was a clean slate approach and nothing more. Whether that's for internally managing performance or to give Abel full flexibility, I doubt they'll share these specifics. $BRK
When I watched it, read the transcript, I found the interview odd. She really pressed him over and over about his relationship with Bill Gates. Regarding GOOG, I thought he danced around it, instead talking about Rockefeller, IBM, and comparing his tech investments to his early tech investment in 1958 of "Data Documents". She pressed hard to get him to discuss him "understanding the game of massive CapEx, hyperscalers, why now versus when they were more asset-light..." - not much from him, in my opinion. $BRK
Notes from WB and Becky Quick Interview 7/15/26. They spent more than half discussing his giving, his relationship to Bill Gates, his children. Still some minor nuggets in there.. $BRK