Why Gold Coast commercial property remains strong in QLD
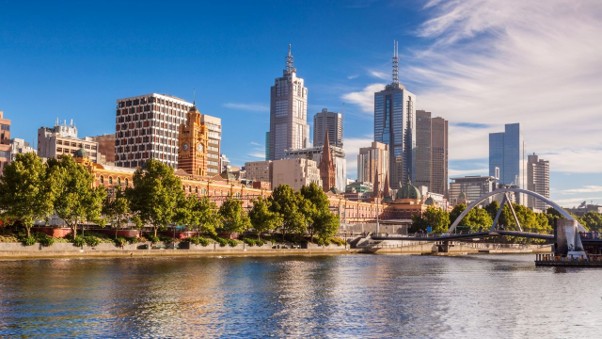
The Gold Coast has overtaken Brisbane as the top location for office buying searches in the 12 months to September 2026, according to https://t.co/V1TpT3oL5Z data. It also leads Brisbane for retail and industrial lease searches, signalling a shift in where investors and businesses are focusing their attention.
Much of the momentum is being driven by interstate migration, with businesses from Sydney and Melbourne relocating to the Gold Coast and seeking premises closer to where their owners want to live. Industry contacts report yields running 20 to 30 per cent higher than comparable assets in southern markets.
Key suburbs leading search activity include Southport for office and retail, Burleigh Heads for industrial and retail, and Surfers Paradise for retail buying and leasing. Demand for A-grade office space is particularly strong, with businesses upgrading to attract staff back to the office.
With major infrastructure spending continuing and land becoming scarce, the Gold Coast commercial market is worth watching. If you are exploring commercial property finance options, a broker can help you compare your options across lenders.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
3 things to check before you refinance
With interest rates rising, a lot of investors are considering refinancing. Here are three things worth checking before you apply.
What your current loan is actually costing you. Look beyond the interest rate alone to understand the full cost of your existing loan, including ongoing fees and remaining term. If you are mid-way through a fixed rate, break costs could affect whether switching makes sense right now.
How much equity you have. Lenders typically require a minimum level of equity before approving a refinance. If your property value has changed since you originally borrowed, your equity position may be higher or lower than you expect. Getting a current picture of your loan-to-value ratio is a useful starting point.
Whether your financial position has changed. Lenders will reassess your income, expenses and existing debts as part of any new application. Changes to your employment, additional credit facilities or shifts in household expenses since you originally borrowed could all affect what you qualify for.
A mortgage broker can help you compare your options.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
4 costs to factor in when buying a new car
The purchase price is usually just the starting point when buying a new car. Here are four additional costs worth factoring in before you commit.
On-road costs. Stamp duty, registration and CTP insurance are payable before you drive away and can add several thousand dollars to the total cost depending on the vehicle price and your state.
Loan fees. Establishment fees, monthly account fees and early repayment charges vary between lenders. These affect the true cost of the loan beyond the interest rate alone.
Insurance. Comprehensive car insurance is typically required by the lender when the vehicle is used as security. Premiums vary based on the vehicle, your age and driving history.
Ongoing running costs. Fuel, servicing and tyres add up over time and are worth building into your budget alongside the loan repayment.
A broker can help you compare your options across lenders.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
WA homes are filling up five times faster than any other state
Western Australia's population is growing five times faster than its housing supply.
New research using ABS data shows WA now has 258 people for every 100 dwellings, up from 240 in 2018, the largest increase of any state or territory.
Perth's median house price has reached $1.01 million, up 18.8 per cent over the year, while WA's mean dwelling price rose 22.9 per cent, the strongest growth nationally.
Over five years, WA prices are up 92.5 per cent compared with 35.2 per cent nationally, moving the state from the fourth cheapest to the third most expensive in Australia.
WA has failed to build enough homes to keep up with population growth every year since 2019, with new supply currently meeting just 70 per cent of estimated demand, the lowest of any state.
A mortgage broker can help you compare your options across lenders.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Victoria moves to ease foreign investor property taxes as housing targets remain out of reach
Victoria's Carroll Labor Government has announced targeted tax concessions for residential developers, with a broader review of foreign investor surcharges promised if the party is re-elected on 28 November.
Under the changes, developers delivering affordable housing through Victoria's Development Facilitation Program will be exempt from the Absentee Owner Surcharge during construction and for up to two years after completion. The changes take effect before caretaker mode on 3 November.
The Property Council estimates the 2023 doubling of the Absentee Owner Surcharge has resulted in approximately $5 billion in lost economic activity, with investment flowing to other states. Victoria is currently building around 55,000 homes per year, well short of the 80,000 needed to meet its decade-long target of 800,000 dwellings.
For developers and property investors active in Victoria, the immediate exemptions offer some relief, though the broader tax review remains dependent on the election outcome.
If you are exploring property finance or development funding options, a broker can help you compare your options across lenders.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
🚨 RBA CASH RATE UPDATE 🚨 | 03/11/2026
The Reserve Bank of Australia has today increased the official cash rate by 0.25%, taking it from 4.60% to 4.85%, marking the fifth rate increase this year and the highest level since 2008.
For homeowners, investors and prospective buyers, this decision could impact mortgage repayments, borrowing capacity and future lending options.
🏡 If you have an existing home loan or are considering buying, refinancing or investing, now is an important time to review your finances and ensure your loan remains competitive and suited to your needs.
📞 Speak with the team at First Choice Home Loans (FCHL) to explore your options, review your current interest rate and understand what the latest RBA decision could mean for you.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Regional commercial property hits $6.2 billion as investors rethink the market
Regional commercial property transactions reached $6.2 billion in 2025, marking the third-highest level on record as investors increasingly view regional centres as growth markets rather than simply high-yield alternatives.
According to Knight Frank's Australian Regional View 2026, regional deals represented about 11 per cent of all Australian commercial property transactions, with retail accounting for more than 40 per cent of activity. The figures point to a fundamental shift in how regional markets are being assessed, driven by population decentralisation, infrastructure investment and economic diversification.
Knight Frank Senior Economist Alistair Read said investor perceptions had changed substantially over the past five years.
"Investors are increasingly recognising that many regional centres now possess the economic scale, population growth and industry diversity required to support long-term commercial property performance," he said.
Population growth is emerging as one of the most significant demand drivers for regional commercial property. About 8.9 million Australians, or 32 per cent of the population, lived outside capital cities in 2024-25, with that figure forecast to reach 9.6 million over the next decade.
Geelong is projected to lead growth with a 22 per cent population increase over the next decade, followed by the Gold Coast at 19 per cent, Wollongong at 16 per cent, Townsville at 14 per cent and Newcastle at 11 per cent. This population growth is expected to drive increased demand for retail, office and industrial space across these regional centres.
However, the regional story is becoming increasingly market-specific. Newcastle is shifting beyond coal and heavy industry, with professional services, healthcare, education, tourism and advanced manufacturing expanding. Its industrial market is also benefiting from the Port of Newcastle, renewable energy investment and defence activity around RAAF Base Williamtown.
Wollongong is experiencing a similar transition towards service industries, with professional services and healthcare growth, the expanding University of Wollongong and the $2 billion BlueScope Land Transformation project at Port Kembla driving future commercial demand.
On the Gold Coast, rapid population growth and economic diversification are creating tight commercial conditions. A-grade office vacancy fell from 18.6 per cent in January 2021 to just 3.2 per cent in January 2026, with limited new supply expected to support rental growth.
Infrastructure investment is also reshaping regional markets. Wagga Wagga has more than $15 billion in infrastructure projects earmarked for the city and surrounding Riverina-Murray region over the next five to 10 years, while Townsville is benefiting from $700 million in defence-related infrastructure investment.
Tourism is providing another tailwind, with total Australian tourism expenditure forecast to rise 22 per cent to $233 billion by 2030, supporting retail, hotel and broader commercial activity in regional destinations.
"Regional can no longer be treated as a single property market," the report said, with infrastructure, employment and industry diversification increasingly determining where commercial property demand is strongest.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Luxury hotels outpace broader market as demand surges
Luxury hotels across Australia and New Zealand are significantly outperforming the wider accommodation sector, driven by strong demand, expanding rate premiums and a limited development pipeline.
According to CBRE's Luxury Hotel Market report, demand across major Australian and New Zealand markets has grown at a 2.9 per cent compound annual growth rate since 2019, more than double the broader hotel market's 1.3 per cent growth rate.
The luxury segment has maintained stable occupancy levels of 78 to 79 per cent despite new supply entering the market.
Since 2020, 20 hotels comprising 3,517 rooms have opened across Australia and New Zealand, with luxury properties representing approximately 33 per cent of all rooms delivered in Australia during this period.
Transaction prices have surged dramatically, with the median price per key increasing by 81 per cent from around $396,000 in 2011-2014 to $718,000 in 2023-2026 year to date. This growth is attracting new global brands and supporting expansion through conversions, repositioning, branded residences and independent operating models.
Since 2021, approximately $3.2 billion in luxury hotel assets have transacted across Australia and New Zealand, with CBRE advising on approximately $1.75 billion, representing 55 per cent of total transaction value.
CBRE's Head of Hotels, Capital Markets, Pacific, Michael Simpson said international capital has been a crucial driver of investment activity.
"These transactions have established new benchmarks for absolute price, price per key and yield, attracting both domestic and international capital," Mr Simpson said.
"Outcomes have been achieved across different market conditions, from transactions executed during pandemic lockdowns to major sales completed as investment activity recovered."
He said that Chinese and Hong Kong investment were particularly active between 2012 and 2018, whilst Singaporean and Malaysian capital has remained steady with a more diversified buyer pool emerging in recent years.
"This depth of offshore interest has supported liquidity and helped establish new pricing benchmarks alongside active domestic capital," Mr Simpson said.
CBRE's Director, Hotel Research, Ally Gibson said luxury hotel performance is supporting the strong pricing outcomes.
"Since 2019, luxury ADR increased across every market analysed and premiums over the all-scales sector are widening considerably," Ms Gibson said.
"In Australia, the average luxury ADR premium over the all-scales sector increased by 53 per cent, from $62 in 2019 to $94 in 2026."
Looking ahead, 11 luxury hotels comprising approximately 1,979 rooms are currently under construction, with most delivery expected in 2026 and 2027. However, beyond the current development cycle, the confirmed pipeline thins materially as feasibility constraints limit new projects.
"Strengthening demand and limited new supply should support the performance and value of established luxury assets, particularly in markets with high barriers to entry," Ms Gibson said.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
5 things that can affect your borrowing capacity that have nothing to do with your income
Most people assume their borrowing capacity is determined primarily by how much they earn. Income is certainly a key factor, but lenders look at the full picture of your financial position, and there are several things entirely unrelated to your salary that can reduce how much you are able to borrow.
Understanding these factors before you apply can help you address any issues early and avoid surprises during the assessment process.
Credit card limits
Lenders assess credit cards at their full limit, not the outstanding balance. A credit card with a $15,000 limit is treated as a $15,000 debt regardless of whether you owe $500 or nothing at all.
If you have multiple cards or a high combined limit, this can reduce your borrowing capacity. Reviewing your credit card limits before applying is worth discussing with a mortgage broker as part of your preparation.
Buy now, pay later accounts
Buy now, pay later balances and active accounts are increasingly scrutinised as part of the home loan assessment process. Even small balances can be flagged, and multiple active accounts can signal to a lender that your discretionary spending is higher than your bank statements alone might suggest. Clearing any outstanding buy now, pay later balances and closing accounts you no longer need before you apply is worth considering.
HECS-HELP debt
Student debt through the HECS-HELP scheme can affect your net income, as repayments are automatically deducted from your salary once you earn above the repayment threshold. Lenders factor this into their serviceability assessment, which means a significant HECS balance can reduce your borrowing capacity even if your gross income looks strong. The larger the debt and the higher your income, the more noticeable the impact is likely to be.
Number of dependants
Lenders use living expense benchmarks that increase with the number of dependants in a household. Two applicants with identical incomes can have different borrowing capacities simply because one has children and the other does not. This is not something you can change, but it is important to understand when you are working out what you can realistically borrow and planning around it.
Existing loan commitments
Any existing debt, including a car loan, personal loan, or an existing mortgage, can affect the amount a lender is willing to extend on a new loan. Each commitment reduces your assessed capacity to service additional debt. For applicants with several existing debts, the impact on borrowing capacity can be significant, even when each individual loan seems manageable on its own.
A mortgage broker can review your position and help you compare your options.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Here is what to look at before taking up zero per cent car finance
Spring is one of the busiest periods for car sales, and zero per cent finance offers are common this time of year.
On the surface, borrowing money at no interest looks like a great opportunity. But the interest is only one component of the total cost of a car purchase, and focusing on it alone can lead to problems in the future.
Here are four things worth understanding before you commit to a zero per cent finance offer.
The interest cost has to come from somewhere
Lenders and manufacturers do not absorb the cost of providing zero per cent finance out of goodwill. The money they give up in interest typically gets recovered through other parts of the transaction.
This might include a higher vehicle price than what a cash buyer might negotiate, reduced scope to get a discount, higher fees embedded in the loan contract or a shorter repayment term that increases the monthly obligation. While the headline interest rate is zero, the total cost of the transaction may be a lot more.
The comparison rate is the number that matters most
Lenders are required to display a comparison rate alongside the advertised interest rate. The comparison rate factors in fees and charges as well as the interest rate, giving a more accurate picture of the true annual cost of the loan.
On a zero per cent loan that carries significant establishment or ongoing fees, the comparison rate may be considerably higher than zero. Comparing the comparison rate on a dealer finance offer against what an independent lender would charge on a standard car loan is a more reliable basis for assessing the real cost than the headline rate alone.
Zero per cent offers often come with restrictions
Zero per cent finance is rarely available across an entire vehicle range. Offers are typically limited to specific models, often those with slower turnover, previous year stock or demonstrator vehicles.
Eligibility requirements can also be more stringent than for a standard car loan, with some offers requiring a strong credit history, a substantial deposit or a short loan term that pushes monthly repayments higher than they would be on a longer-term standard loan. Understanding the specific conditions attached to an offer before you fall in love with the deal is an important first step.
Independent finance may work out more cost-effective overall
One of the tests worth running before accepting a zero per cent dealer offer is to get a finance quote and see what the same car would cost through a different lender.
A buyer who secures their own finance and then approaches the dealer as a cash buyer may also have more room to negotiate on the vehicle price, which can offset the interest cost on an independent loan. The total price paid for the car and the loan combined, rather than the interest rate in isolation, is the figure that determines which option is more cost-effective.
A finance broker can help you compare your options across a range of car loan products.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Sydney and Melbourne sellers withdraw stock as listings tighten
Sellers in Sydney and Melbourne are pulling properties from the market rather than accepting lower prices, creating a supply squeeze that contrasts sharply with conditions in Brisbane and Perth.
According to Ray White chief economist Nerida Conisbee, new listings fell 12.6 per cent in Sydney and 9.7 per cent in Melbourne between May and August, compared with a 6.8 per cent decline nationally. Canberra recorded an even steeper fall, down 14.7 per cent over the same period.
The pullback has flowed through to overall stock levels. Active listings have dropped 5.6 per cent in Sydney and 7.4 per cent in Melbourne since May. Canberra has followed a similar pattern, with active stock down 7.5 per cent.
Ms Conisbee said the trend reflects owners choosing not to sell when conditions are weaker, rather than a lift in buyer demand absorbing existing stock.
"Housing supply is highly responsive to market conditions. Unless an owner needs to sell, they can delay putting their property on the market when prices are weaker or buyers become more cautious," she said.
The picture in Brisbane and Perth is markedly different. New listings in those cities have also declined, down 2.7 per cent in Brisbane and 10.5 per cent in Perth since May.
However, active listings have moved sharply higher, up 27.5 per cent in Brisbane and 20.2 per cent in Perth, indicating that existing stock is taking longer to sell rather than owners rushing to list.
Adelaide is showing a milder version of the same pattern, with new listings up 2.4 per cent and active listings up 15.0 per cent.
For agents in Sydney and Melbourne, the shrinking pool of stock represents a buffer against further price weakness, tightening the balance between buyers and sellers at a time when demand has already softened on the back of Budget changes and higher interest rates.
Ms Conisbee cautioned the outlook remains fragile.
"A further interest rate rise would reduce borrowing capacity and weaken buyer demand again," she said.
Ms Conisbee said the divergence points to a housing market splitting into two distinct phases. Sydney and Melbourne, which experienced the earliest and largest weakness after the Budget, are now seeing sellers withdraw supply in response.
Brisbane and Perth, where conditions held up for longer, are instead grappling with a build-up of stock despite fewer new properties coming to market.
"After leading the initial downturn, Australia's two largest housing markets are moving into a very different phase," she said.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
4 things to think about before selecting an interest-only loan
With the cash rate tipped to rise, property investors are paying more attention to interest-only loans as a way to manage cash flow while rates remain elevated.
Interest-only lending is a specific product with some advantages in certain situations and risks in others.
Here are four things worth understanding before you decide whether it is the right structure for you.
How interest-only repayments actually work
On a standard principal and interest loan, each repayment reduces the outstanding loan balance while also covering the interest charged for that period. On an interest-only loan, repayments cover only the interest.
The principal balance does not get paid down during the interest-only period, which means the loan balance at the end of year five, for example, is the same as it was at the start. This keeps monthly repayments lower during the interest-only period but leaves the full principal to be repaid once that period ends.
Who interest-only loans tend to suit
Interest-only loans are most commonly used by property investors. Where the loan interest is tax-deductible, keeping repayments as interest-only maximises the deductible portion of each payment.
Investors may also prefer to direct surplus cash toward other investments rather than reducing a debt that is working in their favour from a tax perspective.
For owner-occupiers, interest-only loans are less common and typically used in specific circumstances.
Lenders assess these applications more conservatively, and the rationale needs to be clear.
What happens when the interest-only period ends
Interest-only periods are fixed in duration, typically between one and five years for investors and up to five years for owner-occupiers, subject to lender policy.
When the period ends, the loan reverts to principal and interest repayments calculated over the remaining loan term.
Because no principal has been repaid, the remaining loan term is shorter relative to the full balance, which pushes repayments up when the loan converts. On a $600,000 loan with a five-year interest-only period, the full balance remains to be repaid over the remaining 25 years. Planning for that repayment increase well in advance is important.
How lenders assess interest-only applications differently
Lenders apply stricter serviceability tests to interest-only loans than to principal and interest loans.
Because the borrower will eventually need to repay the full principal over a shorter remaining term, lenders typically assess the borrower's capacity to service the loan on principal and interest terms from the outset, even during the interest-only period. This can reduce the amount a borrower is able to access compared to a standard principal and interest structure.
Not all lenders offer interest-only terms to all borrower types, and the rate is typically slightly higher than an equivalent principal and interest loan, which is worth factoring into any comparison.
A mortgage broker can help you compare your options across lenders who offer interest-only products.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
5 things to think about before buying a property with someone else
With property prices remaining high across most of Australia co-purchasing has become an increasingly practical path into property ownership.
Buying with a partner, family member or friend can give buyers a larger deposit and greater borrowing power than either party could achieve alone.
But co-ownership is a significant financial and legal commitment, and the arrangement works better when everyone involved understands the key considerations before they sign anything. Here are five things worth thinking about.
Joint tenants and tenants in common are not the same thing
There are two ways to hold property with another person in Australia. Joint tenants own the property equally, and if one owner dies, their share automatically passes to the surviving owner regardless of what their will says.
Tenants in common each own a defined share of the property, which can be equal or unequal, and that share forms part of their estate and passes according to their will. Couples commonly choose joint tenancy, while friends or family co-purchasers often opt for tenants in common to reflect their individual contributions.
Lenders assess all borrowers on the loan jointly
When two or more people apply for a home loan together, lenders assess the combined income, expenses, debts and credit history of all applicants.
This can increase borrowing capacity compared to applying alone, but it also means that any issues on one applicant's credit file or financial position affect the entire application.
Each borrower is jointly liable for the full loan, meaning if one party stops making repayments, the other is responsible for the full debt.
What happens if one party wants to sell
This is one of the most common sources of tension in co-ownership arrangements and one that is worth planning for before it becomes an issue. If one owner wants to sell and the other does not, the options typically include one party buying out the other, agreeing to sell the property jointly, or in some cases, applying to a court to force a sale.
Having a co-ownership agreement prepared by a solicitor before settlement, setting out what happens in these circumstances, can prevent a difficult personal situation from becoming an expensive legal dispute.
Each party's financial position affects the other
Co-ownership creates an ongoing financial link between the parties that extends well beyond the initial purchase. If one co-owner falls into financial difficulty, misses repayments or has other debts called in, it can affect the shared property and the other owner's credit position. It is worth considering not just whether the arrangement works today but how it might hold up if one party's circumstances change significantly.
Get legal and financial advice before you commit
Co-purchasing works well for many people, but the arrangements that tend to go smoothly are the ones where both parties have taken independent legal advice and put a co-ownership agreement in place before settlement.
A mortgage broker can help you compare your options and understand how the process works.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Can you pay off your car loan early?
Paying off a car loan ahead of schedule is possible, but there are a few things worth understanding before you do.
Early exit fees may apply - Fixed rate loans in particular can attract break costs if you pay out early. Check your loan contract or contact your lender before committing to a payout.
Variable rate loans are generally more flexible - Variable rate car loans tend to have fewer restrictions on early repayments, though this varies between lenders.
Paying down the balance reduces interest - Interest is calculated on the outstanding balance daily, so any additional repayments or lump sum payments reduce the interest accruing from that point forward.
Factor in any balloon payment - If your loan includes a balloon payment, this needs to be included when calculating the full outstanding balance at payout.
Consider your cash position first - Paying out the loan may make sense, but it is worth weighing the cost of any exit fees against the benefit of clearing the debt before using savings to do so.
A finance broker can help you compare your options.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
4 signs your business could benefit from invoice finance
Invoice finance allows businesses to access funds tied up in unpaid invoices rather than waiting on clients to pay. Here are four signs it could be worth exploring.
Your clients take 30 to 60 days to pay - If extended payment terms are standard in your industry, invoice finance bridges the gap between completing work and receiving payment.
You are turning down work due to cash flow - If your business has the capacity to take on more clients or larger contracts but cash flow is holding you back, invoice finance could help.
You are struggling to meet payroll or supplier payments - When outgoings fall due before client payments arrive, invoice finance provides a way to manage that gap without taking on a traditional loan.
Your business is growing faster than your cash flow - Rapid growth often creates cash flow pressure before revenue catches up. Invoice finance scales with your invoicing volume, making it a flexible option for growing businesses.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
3 signs it might be time to refinance your business loan
Business lending has changed considerably over the past two years. If your loan has been in place for a while, it is worth checking whether it is still the right fit for your business.
Your business position has changed - If your business has grown, improved its cash flow or built a stronger track record since you first borrowed, it may be worth reviewing whether your current loan terms still reflect your business’s position.
The loan structure no longer suits how you operate - A loan that made sense when you took it out may not reflect your current cash flow patterns, repayment capacity or how the business has evolved.
You are approaching the end of a fixed term - The period before a fixed rate expires is a good time to review your options rather than rolling over automatically into whatever your lender offers next.
A finance broker can help you compare your options.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Data centre boom set to push industrial rents sharply higher
Australia is now the third-largest destination globally for data centre development, and the resulting competition for industrial land is beginning to have a significant impact on the commercial property market.
New JLL research suggests economic rents for a 20,000 square metre warehouse could double in some markets by 2028, as data centre developers continue to pay significant premiums for industrially zoned land.
JLL found that data centre developers paid premiums of between 20 and 63 per cent above average land values for industrial sites in outer suburban areas. In Sydney, economic rents are already between 30 and 43 per cent above current prime net face rents. In Melbourne’s west, they could exceed market rates by 130 per cent. Average land values for two to five hectare lots in Melbourne’s west grew 16.5 per cent in the 12 months to June 2026, with Sydney’s outer central west up 9.6 per cent.
Regional markets are also emerging as the next frontier, with Anthropic recently signing a deal to anchor a proposed $32 billion data centre hub in Queensland’s Western Downs, signalling growing confidence in locations beyond the major metropolitan fringe.
If industrial or commercial property is part of your investment strategy, a finance broker can help you compare your options across a range of commercial lending products.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Foreign investment fuelling Australia’s commercial property boom
Offshore buyers now account for 34 per cent of all Australian commercial property trading in 2026, up sharply from 23 per cent in 2025, according to Commonwealth Bank data. Total commercial property sales reached $48.4 billion in the year to 31 August, up 6 per cent on the same period last year, with offshore capital contributing $16.3 billion of that total.
Singapore and Canada together account for 70 per cent of offshore acquisitions. Queensland has emerged as the standout domestic mover, with investment up 39 per cent to $10.8 billion, overtaking Victoria to become the second largest state market nationally.
CommBank’s commercial property research director noted the budget’s proposed changes to residential negative gearing and CGT could prompt investors to look increasingly at commercial assets, where existing tax arrangements remain in place.
If commercial property is on your radar, a finance broker can help you compare your options across a range of commercial lending products.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
3 differences between owner-occupier and investor home loans
If you are considering buying an investment property, it is worth understanding how investor lending differs from the owner-occupier loan you may already have.
Deposit requirements can differ - Most lenders require a different deposit for an investment property compared to an owner-occupied home. Borrowing above 80 per cent of the property value on an investment loan may also attract different conditions to an owner-occupier loan.
Serviceability is assessed differently - Lenders factor in your existing mortgage commitments, living expenses and the expected rental income from the investment property when assessing how much you can borrow. Rental income is typically included at a discounted rate rather than its full value.
Loan structure options differ - Interest-only repayments are more commonly used on investment loans, as the interest component may be tax deductible. How this interacts with your broader tax position is worth discussing with your accountant before you choose a structure.
A mortgage broker can help you compare your options.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA
Rental yields hit their highest level since 2019
While much of the focus in the property market has been on falling values, one metric has been moving in a positive direction for investors. According to Cotality’s September 2026 Home Value Index, the national gross rental yield has risen to 3.79 per cent - its highest level since September 2019.
The improvement has been driven by rents continuing to rise, up 5.7 per cent nationally over the past 12 months, while dwelling values have softened.
The yield picture varies considerably by location. Darwin leads at 6.3 per cent, followed by Hobart at 4.4 per cent. Among the larger capitals, Melbourne sits at 4.0 per cent and Brisbane at 3.4 per cent. Units are outperforming houses on yield nationally at 4.6 per cent versus 3.5 per cent for houses.
Cotality’s Tim Lawless said that with proposed budget changes to property tax, investors are likely to place greater emphasis on higher-yielding opportunities. Yields would still need to rise further before rental income offsets holding costs at current interest rate levels.
A finance broker can help you compare your options across a range of investment property lending products.
#firstchoicehomeloans #fchl #mortgagebrokerlife #mortgageadvice #homeloans #mortgagespecialist #interestrates #reservebankofaustralia #rates #RBA