Nothing optimised. Net t after costs: 4 at t ≥ 2 in 2015–2021, 17 in Jan 2022–Oct 2026 vs ~23 expected by luck, overlap 0. 15 of 17 long-only, 11 MA; gold rose OOS. Dukascopy bid/ask + $0.10/oz slippage; no swap. https://t.co/Y132AP8Zky Educational only. Not financial advice.
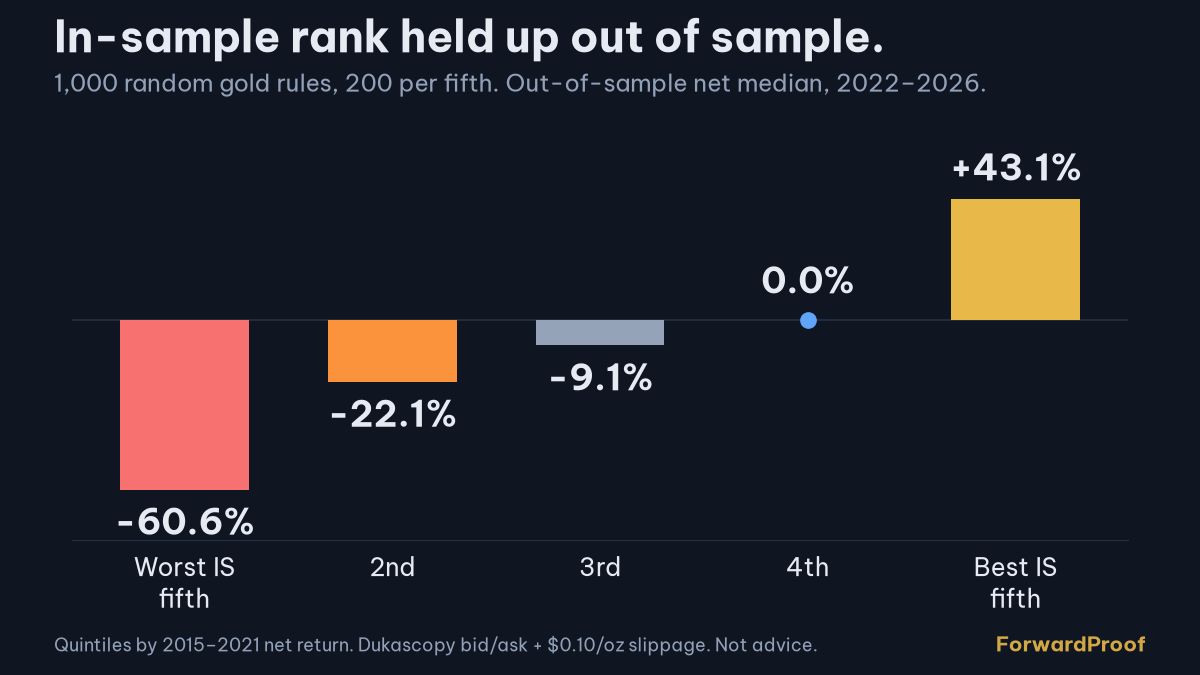
1,000 random XAUUSD rules, nothing optimised. Quintiles by IS net return (200 each). OOS net medians, Jan 2022–Oct 2026 (IS 2015–2021). Spearman ρ=0.809. Dukascopy bid/ask + $0.10/oz slippage; no swap. https://t.co/Y132AP8Zky Educational only. Not financial advice.
Dukascopy bid/ask + $0.10/oz slippage; no swap; sum of hourly %, no compounding. 1,000 random XAUUSD rules, OOS Jan 2022–Oct 2026. Buy-and-hold, same arithmetic: +90.5%. Nothing optimised. One market, 2015–2026. https://t.co/Y132AP8Zky Educational only. Not financial advice.
1,000 random rules on gold.
Out of sample, 350 made money.
0 beat simply holding it (+90.5%).
The best rule: +77.6%.
What does your backtest compare itself to?
Time-of-day gold rules lost 66.6 percentage points to costs.
Channel breakouts lost 4.1.
1,000 random rules. Median trades: ~3,612 vs ~160.
What's the cost drag in your last backtest?
Across 1,000 random rules on gold, out-of-sample net return correlated 0.70 with net long exposure.
In a strong 2022–2026 gold market, higher net long exposure tracked higher OOS results.
How much of your last backtest was exposure?
50 of 130 time-of-day rules on gold were profitable before costs.
After real spreads: 0.
Channel breakouts: 83 of 156 before, 68 after.
Median trades per rule: ~3,600 vs ~160.
How many trades does your strategy make a year?
Each is a fair coin (p = 0.5). One hits 60%+ in 20 trades 25.17% of the time; 10 independent tries: 1 − (1 − 0.2517)^10 ≈ 94.5%. Correlated variants change the math. And win rate isn't profit. https://t.co/cutyFGLBVR Educational only.
Test 10 zero-edge strategies, 20 trades each.
94.5% of the time, at least one shows a 60%+ win rate.
Same 10 at 300 trades each: 0.3%.
How many variants did you try before the backtest you kept?
1,000 random rules on gold.
40 looked significant before costs.
4 survived real costs.
0 stayed significant in the next ~4 years.
Backtest, then forward-test.
In-sample 2015-2021, hourly bid/ask data, spreads only (no commission/slippage). Luck figure is rough: rules overlap.
Most of the 40 traded a lot (median 3,611 position changes). After spreads, median return: +36.5% to -22.9%.
https://t.co/Y132AP8Zky
Educational only.
We tested 1,000 random trading rules on gold.
40 looked profitable and statistically significant. Pure luck would give about 23.
Then we added real bid/ask spreads. Only 4 still passed.
Do your "great" backtests include costs?
4 AIs + 1 simple 20-day-average rule. Each call is timestamped before the move and scored next day by fixed rules. Oct 23: all 5 agreed, so one view, not 5 wins.
40 trading days before any verdict. Full ledger: https://t.co/evRetSkIX6
Research, not trades. Not financial advice.
Most trading-bot videos only show wins. Here's our real scoreboard, misses included.
Day 2: 4 of our AIs said "wait". Gold fell 2.46%. Hit rate dropped to 50%.
As of Oct 26: 9 of 13 scored calls right. Far too few to prove anything.
Not financial advice.