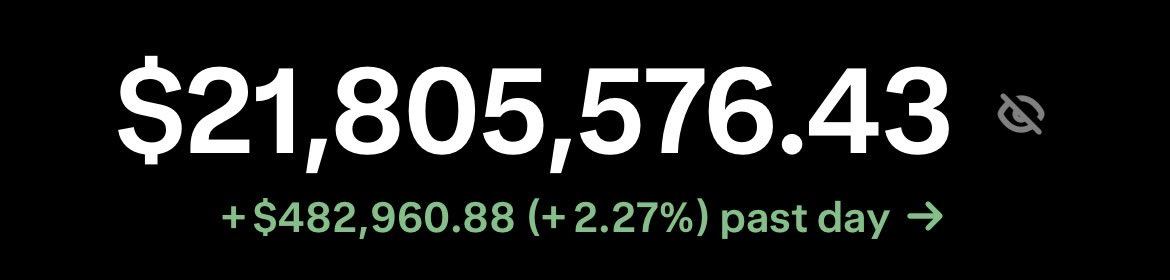
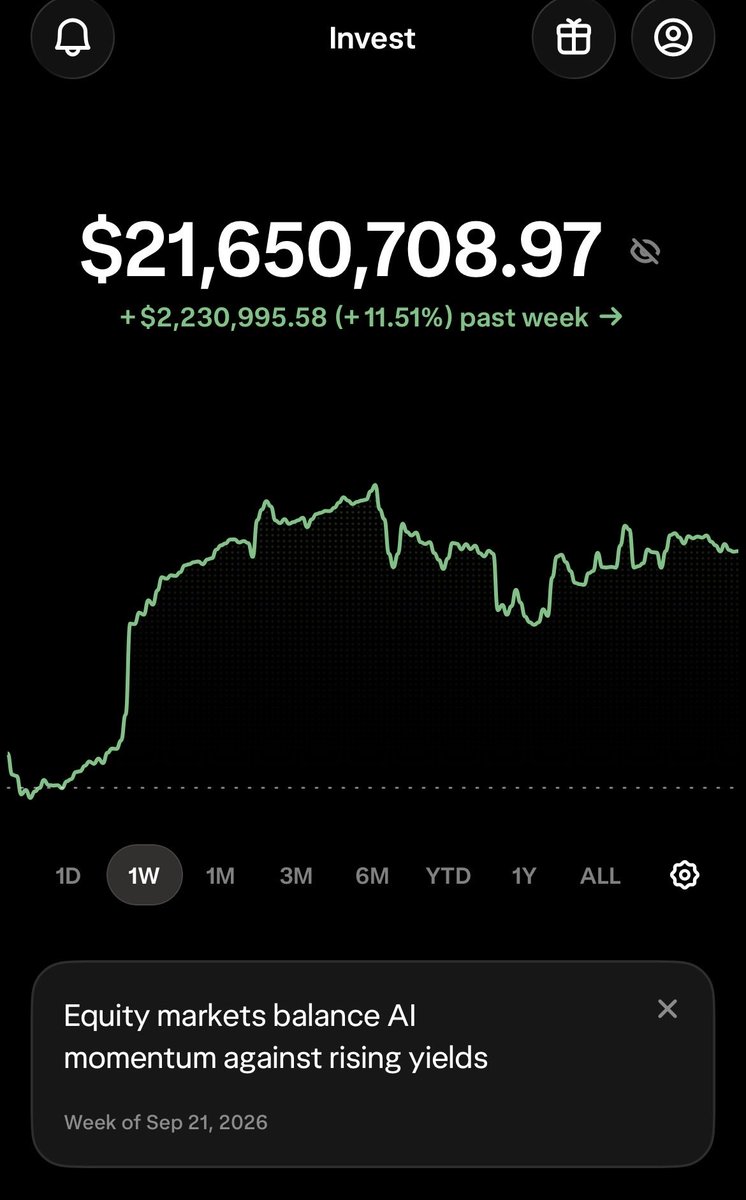
End of week update
Driven mostly by big tech. Data center stocks took a beating so rotation some into $HUT $CIFR $WULF $APLD. $NBIS performed surprisingly well this week, probably because it was rebounding from last week.
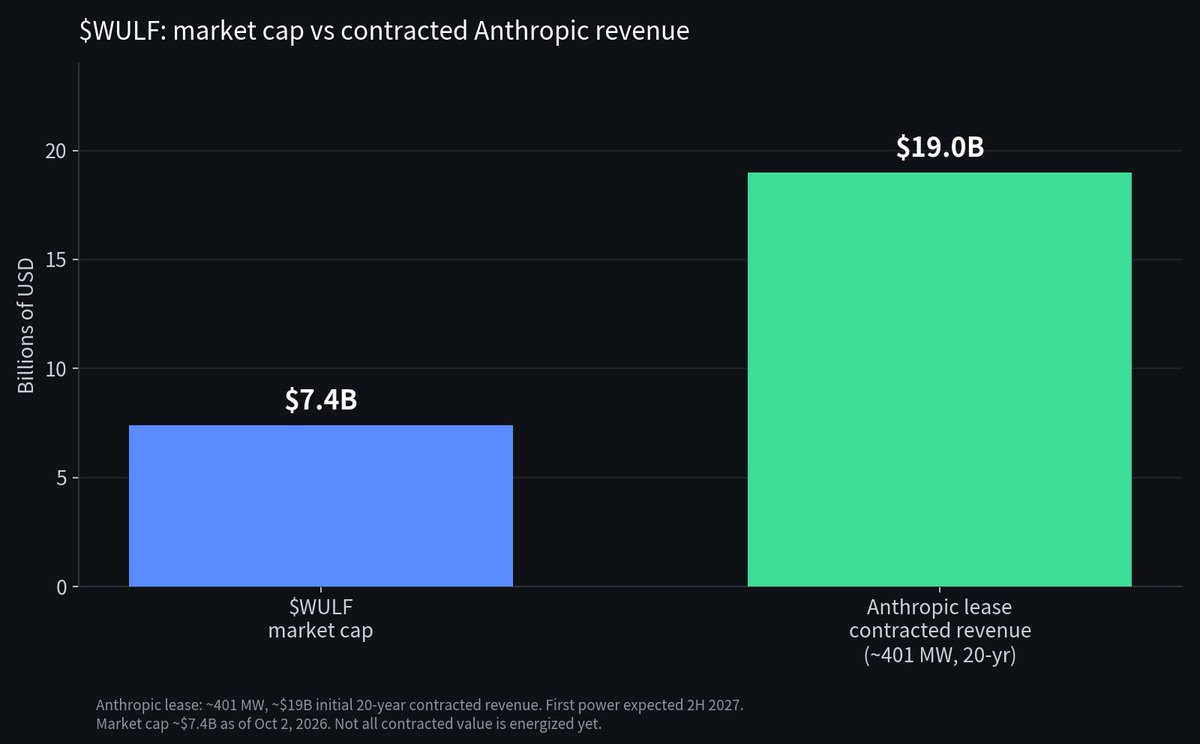
I have been waiting on this one. CB-4 in Q4, CB-5 in Q1 2027, and once CB-5 is live more than half of contracted megawatts are producing revenue. That is the part the $7.4B market cap still is not pricing. Anthropic is 20 years, ~401 MW, about $19B contracted, first power 2H 2027, and HPC lease revenue already went from $9.7M to $31.9M. He borrowed against 3 million shares to pay taxes instead of selling, and still holds more than 50 million. $MU just printed $54.23B with an 86.8% gross margin and still cannot fill demand. I am not trading the next quarter. I am long the megawatts.
This is the post I wanted. Execution is the whole argument for me.
CB-4 in Q4 and CB-5 in Q1 2027, and once CB-5 is on you said more than half of contracted megawatts are producing revenue. That is the gap the market is still pricing like a story. $WULF is about a $7.4B market cap, stock around $15. The Anthropic lease is 20 years, ~401 MW, about $19B of contracted revenue, first power second half of 2027. HPC lease revenue already went from $9.7M in Q4 2025 to $31.9M in Q2, about 71% of sales. I do not need Muskie or Morgantown to close tomorrow. I need CB-4 and CB-5 to show up when you said they would.
The Form 4 helps. Borrowing against 3 million collared shares to pay taxes instead of selling, and still holding more than 50 million shares, warrants and awards, is not what I see from most of the AI power group. COO, CFO and CTO paying tax out of pocket instead of dumping vesting shares is the same signal.
I am long because the semis just confirmed the demand. $MU printed $54.23B, up from $11.32B, gross margin 86.8%, and they still cannot fill it. That load has to land on leased megawatts. You are building for decades. I am holding it that way.
73% down to 15% just makes me more bullish on what I already own.
Semis are the tell. $MU printed $54.23B in the quarter, up from $11.32B a year ago. Adjusted EPS $33.42 vs about $3.03. Gross margin 86.8%. DRAM was $39.8B, 73% of sales, up 343%. Data center SSDs nearly $10B, more than 10x. Next quarter they guided $61.5B and $38.15. Full year was $133.2B, up 256%, non-GAAP EPS $75.52. Most of calendar 2027 HBM is already sold at higher prices. 26 strategic agreements, some out to 2031. Sanjay said they still cannot fill the demand. Stock around $1,098, about a $1.24T market cap, up roughly 500% in a year, and I still think the shortage is in front of us, not behind us.
That demand has to land somewhere with power. I am long $WULF into that. About a $7.4B market cap, stock around $15, against a 20-year Anthropic lease for ~401 MW and about $19B of contracted revenue. First power is second half of 2027. HPC lease revenue already went from $9.7M in Q4 2025 to $31.9M in Q2, about 71% of sales. $NBIS is the other one I want. Customer commitments over $40B, contracted power target raised to 5 GW, Microsoft about $17.4B, Meta $12B plus up to another $15B.
Cheaper money does not hurt a market that cannot get enough HBM or enough leased megawatts. I am not trimming. I want more of both.
Good morning.
I am still on the same two shortages.
$MU just printed $54.23B in the quarter, up 379% from $11.32B, adjusted EPS $33.42, gross margin about 87%. They guided the next quarter to roughly $61.5B and $38.15. Full year was $133.2B, up 256%. DRAM was $39.8B, 73% of the quarter. HBM grew faster than the company, and they already have most of calendar 2027 HBM bits contracted at higher prices. Sanjay still says they cannot fill all the demand. 26 strategic agreements, some out to 2031.
That only works if the megawatts exist. $WULF is about a $7.4B market cap against a 20-year Anthropic lease for ~401 MW that they have put at about $19B of contracted revenue. First power on that site is 2H 2027, so a lot of it is signed and not energized yet. $NBIS has raised its contracted-power target to 5 GW and customer commitments are over $40 B.
I do not need a green open. I need the leases and the HBM bits to stay sold.
$MU $WULF $NBIS $CIFR $HUT $APLD
I buy the demand side. I am not sure the price side shows up as fast as people think. Micron just said they still cannot fill customer demand even after the long-term agreements, and customers keep coming back for more. Q4 revenue $54.23B, gross margin ~87%, and they have agreements covering most of 2027 HBM supply at higher prices. Only three companies can actually ship HBM at scale. That is why I also own the power side. $WULF is about a $7.4B market cap against a 20-year Anthropic lease for ~401 MW that they have put at about $19B of contracted revenue, first power not until the second half of 2027. Memory can get cheaper later. The megawatts and the HBM bits that are already signed do not.
I had the same reaction. Q4 revenue was $54.23B, up 379% from $11.32B a year ago, adjusted EPS $33.42, gross margin about 87%. They guided the next quarter to roughly $61.5B and $38.15. Full-year fiscal 2026 was $133.2B, up 256%. Data-center DRAM and SSDs did the heavy lifting, DRAM was $39.8B and 73% of the quarter, and HBM grew faster than the company. They also said they have agreements covering most of calendar 2027 HBM bit supply at prices well above last year, and they are working with Nvidia on a custom HBM. Stock barely moved because it is already up huge and the question is what is left in the multiple. I still own it. Hynix is over half the HBM market and cheaper on forward numbers. I would rather hold the shortage than guess when the multiple compresses.
I keep coming back to the same thing on this. 1.77 MW per unit, four of those in a pod, and then you scale the pods from 5–20 MW up toward 50 MW. That is the part I actually care about. I have been in $NBIS since around 185 because the execution has been cleaner than $CRWV or $IREN, and this is the same pattern. They already raised the contracted-power target to 5 GW and customer commitments are over $40B. Microsoft was about $17.4B over five years, Meta was $12B committed plus up to another $15B. Modular at sites that already have power is how you turn those commitments into energized megawatts instead of waiting on a full campus build. I do not think the Palantir logo is the edge. The edge is that $NBIS can drop capacity where the interconnect already exists.
@lord_fed@lord_fed I think you're right. He was impressively at 10 and then 8M in 2021. Had he just stuck it in SPY he would be about $15 Million by now. @kevinxu did great in his run-up then dropped the ball.
@stevenfiorillo HBM growing faster than Micron is the only line that matters. Hynix owns over half that market and trades at 5x forward. Both $MU and $SKHY are situated for high growth in the next few months.
@wallstengine Altman funding a startup to route around HBM is actually the most bullish thing you can say about HBM. Nobody raises $88M to solve a shortage that isn't there. Photonics is a 2030 story. $SKHY and $MU gets paid now.
@TheSkayeth Good call with $NBIS. Ive been in since 185. They are in a league of their own with their execution. I'd place them miles ahead of their competitors $CRWV and $IREN.
@TheoSaurus9@MelissaLMRogers@grok That doesn't answer the question. I'm saying that all countries have suffered under these tariffs. Yes Canada's economy is not as strong as the US, but just appeasing. The president does not yield better results.