It's been almost 16 months since I started publishing my deep dives in public and 6 months since going paid.
I thought it would be a good moment to pause and express my gratitude for the community that has formed around this work.
When I first started writing, there were no expectations beyond wanting to think more clearly by documenting my process, and sharing ideas with like-minded individuals. The response since then has been far more encouraging than I could have imagined.
I also think it’s an appropriate time to take stock of how things have been going and provide some transparency around the performance of these deep dives so far.
I've published 13 deep dives to date, 10 bullish and 3 neutral. I have no interest in being bearish or short. If I don't like a business/stock, I simply don't buy it.
Of the 10 bullish picks, 9 are currently in the green while 1 is in the red. One of the green positions has been closed, while the others continue to be held.
Of the 3 bearish picks, all 3 are in the red as I write.
On average:
- Bullish picks: +38.7%
- Bearish picks: -26.7%
- SPY: +12.2% over the same period
I must also acknowledge that I’ve been fortunate to have started this blog in the middle of a bull market, and the performance to date is by no means a reliable indicator of long-term success.
I’m sector-agnostic, and these names span e-commerce, consumer discretionary, SaaS, infrastructure and more. It's still very early and I've thoroughly enjoyed the process thus far. There will definitely be drawdowns and mistakes ahead. As always, I'll stay transparent and share both the research and the outcomes, good and bad.
Thank you to everyone who has been part of the journey, in particular to paid subs who continue to place their trust in an anonymous person from a tiny country in Southeast Asia. I hope to continue rewarding that faith by producing high-quality research grounded in facts, not hyperbole. ❤️
$SE
One Shopee number that got little attention this quarter.
Value-added services revenue, mostly logistics fees, was flat YoY at $724M while orders grew 25.5%. That's ~20% less logistics revenue per order.
Lower free-shipping thresholds and the cheap shipping option, now more than half of Indonesian orders, show up as lower revenue, not marketing spend.
It is a second, less visible investment on top of the 60% jump in S&M.
Publishing my $SE Q3 2026 earnings review shortly at the usual place!
Quite a long one, and frankly haven't covered everything yet. Will share with subs more over the coming days.
For over a year now, people have been questioning why $NVDA was trading at low 20s earnings multiple while growing much much faster than peers.
Market always knows…
$SE
New monthly active buyers on Shopee grew more than 50% YoY in Q3, up from more than 35% in Q2, and total buyers grew 20%.
This supports the case for higher S&M spend.
If Shopee were buying growth that won't stick, the buyer numbers should start to show it. So far, they are accelerating.
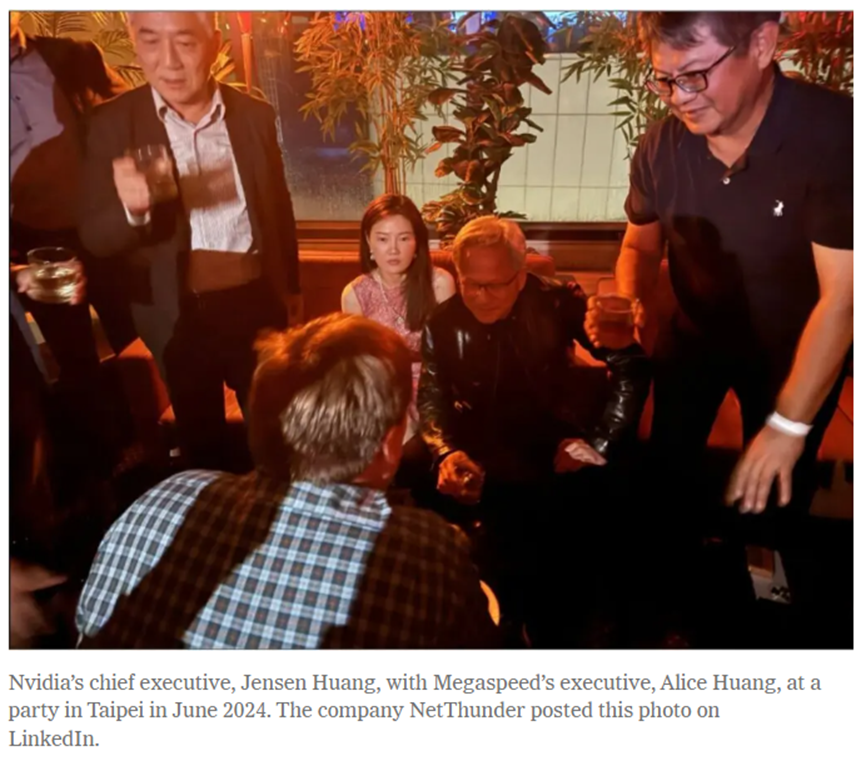
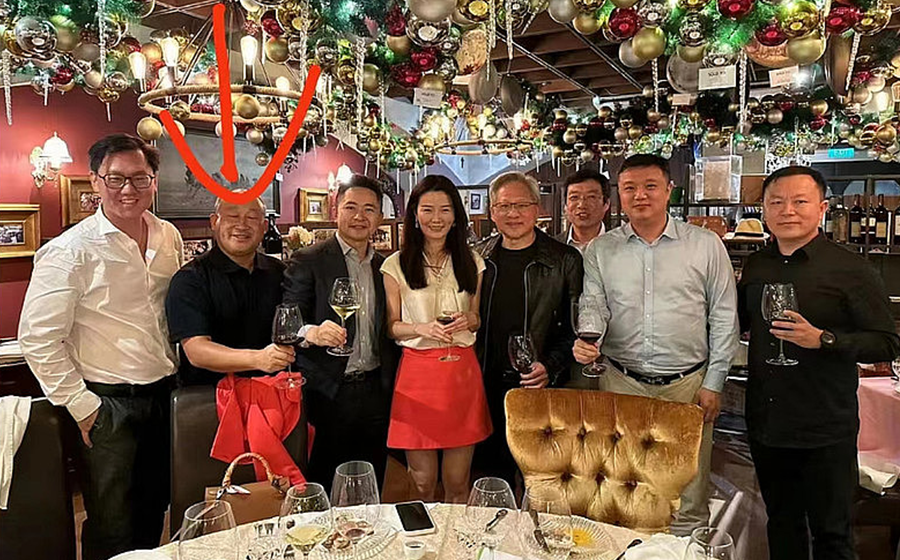
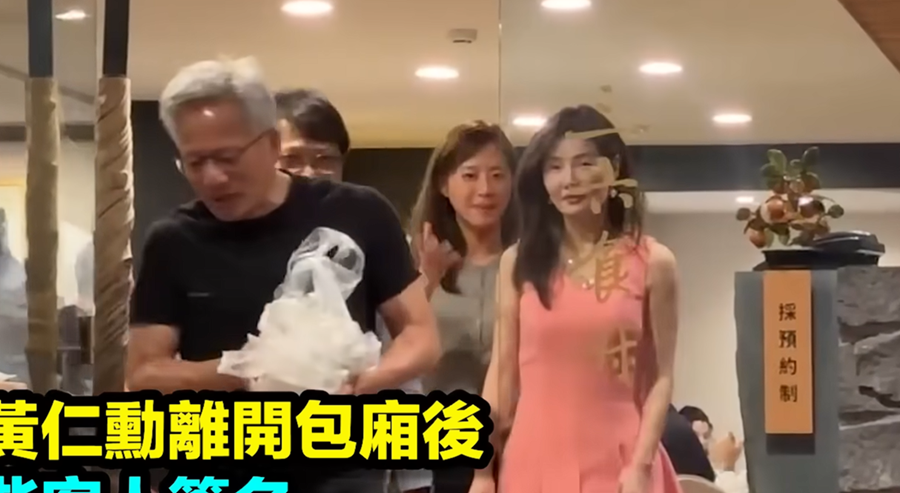
9) $NVDA CEO Huang has walked alongside Megaspeed at every step, and seems to have a close relationship with Megaspeed's Alice Huang. They partied together in June 2024 - same month as the Apex/Alibaba pledge, then dined together in May 2025 - just after U.S. trade restrictions.
NEW: We are short Nvidia $NVDA. We believe Nvidia has a significant China problem. Please see our full report and disclosures now available on our website, link in bio.
$SE reported Q3 earnings yesterday. It was down 10%, up 9% and closed the day down 1.5%.
I discuss the pros and cons below.
Pros:
• Revenue was a clear beat, which was to be expected, with analyst expectations of just 35%, a pretty low bar considering $SE grew 48% and 47% earlier this year.
• Shopee had its best quarter yet, especially in terms of monetisation. Adj. EBITDA rose 45% to $269M and was about 0.68% of GMV. Still far from management's long-term target of 2-3%, but a 10bps bump from last year nonetheless.
• ShopeeVIP continues to grow incredibly well. Now has over 21M members, up 40% QoQ and contributes 1/4 of Shopee GMV. For context, about 5% of buyers drive 25% of sales. That is incredible. Monthly retention rate of 80% continues to be impressive, largely due to Monee's credit cards.
• Monee's growth accelerated, up from 54%, 58% and 59% in the past 3Q's to 64% this Q. The loan book reached $12.6 billion, up 60% YoY, and active credit users rose about 28% to nearly 44 million, with nearly 6 million first-time borrowers.
• Sea repurchased $997M worth of shares, nearly exhausting its $1B buyback program and authorised another $1B buyback program on 9th Nov.
• Management highlighted their intention to run Sea Cloud as a "frugal" startup, and be absolutely confident about a strong ROI before investing capital.
• 9M diluted weighted shares were 633M vs 638M a year ago, share dilution has slowed for now.
• SBC fell to $132M from $154M, R&D rose only 5%.
• Shopee Mall GMV up 2.5x from a year ago and carried a basket size ~3x platform average. Management sees a lot of headroom to grow.
Cons:
• Shopee's S&M rose to 3.61% of GMV up from 2.78% of GMV in the same Q last year. This about offsets the 81bp gross profit gain. EBITDA/GMV only moved from 0.58% to 0.68%, and most of that came from overhead leverage.
• It appears monetisation gains will come slower than some expected as management stated some future monetisation gains may go back into growth instead of profit.
• Annualised provisions are about 21.5% of the loan book, up from about 19%, reflecting tougher conditions in Brazil.
• Cash loans and off-Shopee lending are now about 60% of the book, and Brazil plus off-Shopee SPayLater drove the NPL uptick. The book is shifting slightly more towards riskier products.
• In the first 9M, loans receivable grew $4.45B. Deposits ($1.82B) and other credit funding ($0.44B) only covered about half. This explains why Sea may decide to IPO Monee. It is currently consuming group cash.
• CAPEX roughly doubled, and this is likely the purchase of GPUs for the cloud business. Net PP&E rose 43% and lease assets 46% since December 2025. I believe this is the largest near-term risk for the stock.
Will share more thoughts in my full earnings review that I hope to publish in ~24h!
They have, of course, done this in China. The Chinese equivalent is Douyin Mall (抖音商城), launched in March 2024.
It started modestly, but has about 169M MAUs as of Sept 2026. During the peak October promotional period, daily active users were 55M, in comparison to 469M at Taobao and 216M at JD.
It will be interesting to see how much TikTok Shop cannibalises from its sister app, and whether it can maintain retention over time, which is the key.
TikTok Shop has launched a standalone shopping app in Singapore, Malaysia, Thailand and the Philippines.
They are attempting to move shoppers from entertainment to an intent-based app.
It will be interesting to see how this plays out.
I think it's too early to tell whether it is put to good use yet. A large majority of the S&M spend over the past 6 quarters have been on Shopee VIP and logistics.
Take rate has gone from 13.3% -> 15.3%. Of that 2 pts, about 0.8 pts went to S&M, 0.1 to Adj. EBITDA and the rest to "cost of revenue", largely logistics.
I believe most of the S&M spend has been directed towards ShopeeVIP, which perhaps has lifted ad revenue and take rate rather than GMV. On that note, I think revenue is a better measure (+41%).
ShopeeVIP is burning about $0.80-$1.65 per subscriber per month according to UBS, so they have likely spent ~$150-200M in the past 9M alone.
They are definitely feeling some weakness in GMV growth across key markets like Indonesia, if my guess is correct. Growth has also come down on TikTok Shop's end.
Definitely something to take note of.