GoldTrust is coming soon: an AI auto expert in the consumer's phone for the full car-buying journey. Research vehicles, plan realistic payments, compare offers, prepare for the dealership, and review quotes/contracts before signing. Built so buyers walk in prepared.
Auto-loan prequalification is an estimate—not final approval. Before you commit to a car, compare the vehicle-specific APR, term, amount financed, payment, total cost, and conditions in writing.
Independent checklist; no Chase affiliation:
https://t.co/42zjzYFoJx
Prepare at home. Walk in ready.
Try GoldTrust’s free Deal Tools. Activate ODIN when it’s time to go.
GoldTrust—AI on your side for every car decision.
2/2
https://t.co/bC41K7ctnf
Why wait until you’re sitting at the dealership to understand the deal?
Prepare from home. See the numbers behind the payment. Build your questions. Then bring ODIN.
Let ODIN handle the numbers. You make the decision.
AI-generated brand character. 1/2
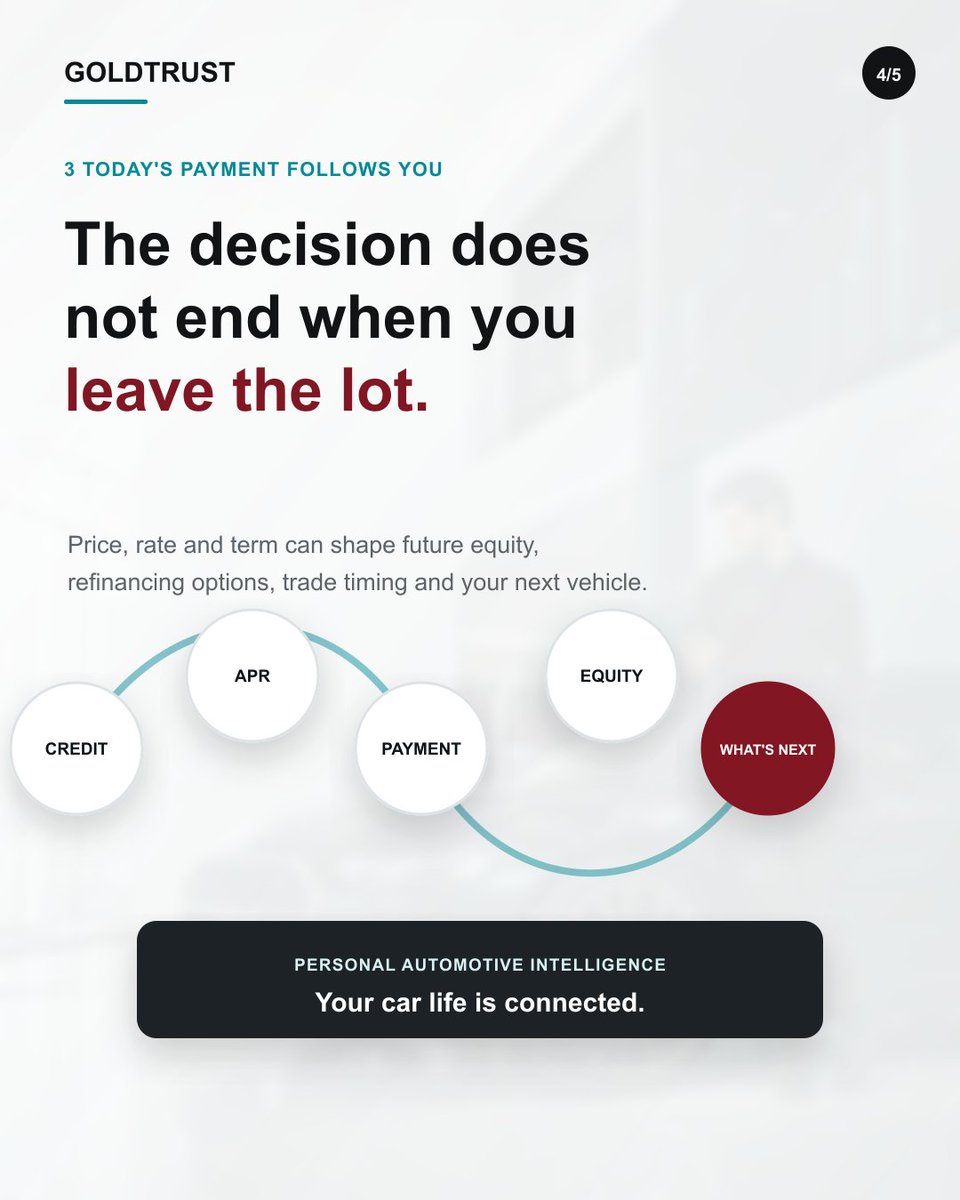
The deal follows you after the dealership.
Today’s financing shapes future equity, refinancing and trade timing.
GoldTrust is personal automotive intelligence—AI on your side for buying, financing, ownership and what comes next.
Ask better questions. Make better car decisions.
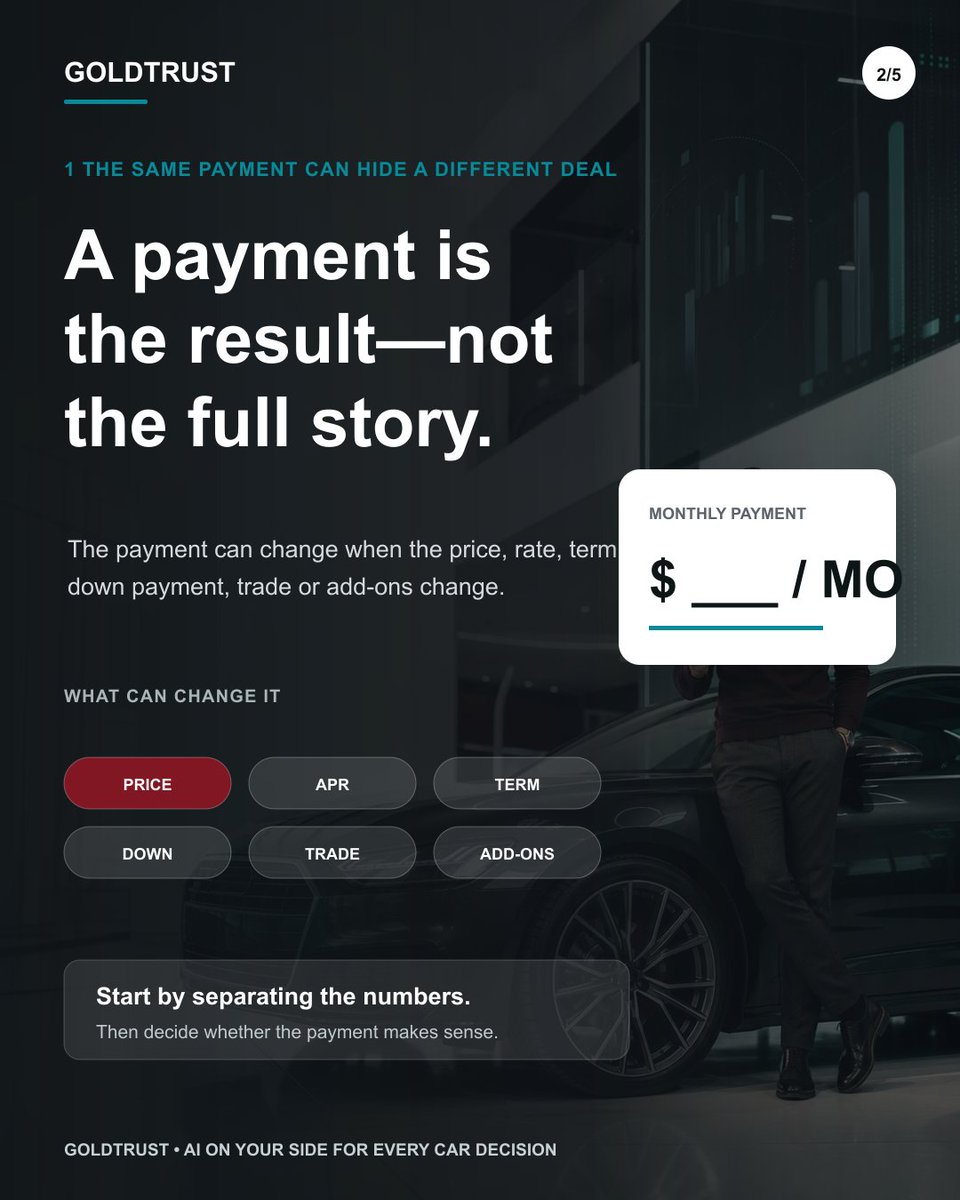
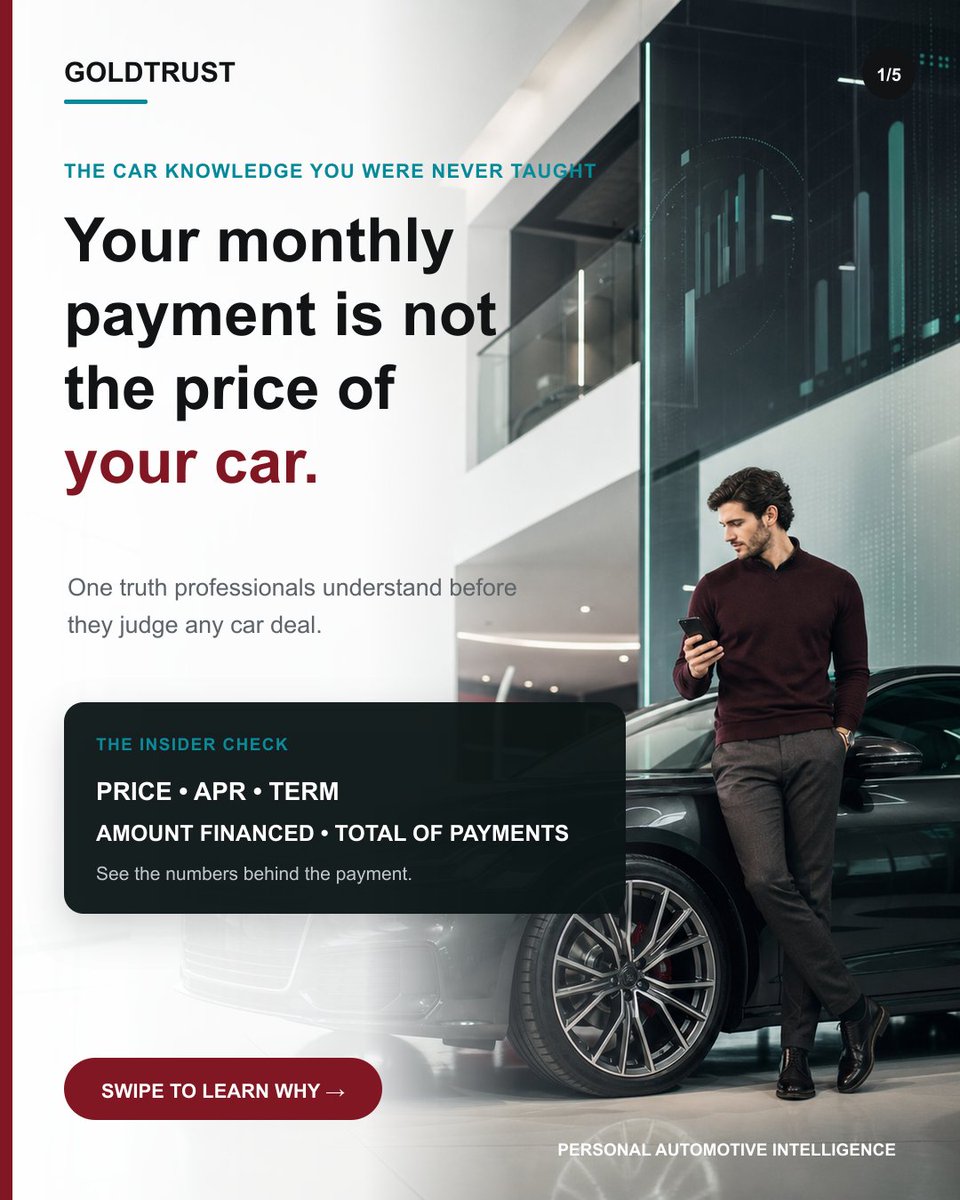
$650/month tells you almost nothing about whether the car is a good deal.
Your payment is the output—not the deal.
Before you sign, separate:
• out-the-door price
• APR
• term
• amount financed
• total of payments
Swipe. Save this for your next car decision. 🧵
@UtdDebtRelief@MoneyLion This is why buyers need more than a payment quote. A car decision should include total debt picture, loan term, interest cost, insurance, ownership horizon, and how it affects the next major financial move.
@thaiginoretired Negative equity is where a lot of buyers lose control of the deal. The key is seeing payoff, trade value, amount financed, term, APR, and total interest together before rolling anything into the next loan.
@MikeCalcara Exactly. Monthly payment is only one output. Buyers need the full deal: out-the-door price, APR, term, taxes/fees, add-ons, trade equity, and total interest before deciding if it actually works.
@asotu_ Dealer visibility matters, but the next layer is buyer trust. Traffic converts better when shoppers arrive with payment clarity, offer context, and paperwork confidence before the visit.
Building GoldTrust from 4+ years inside auto sales and F&I.
Mission: put an AI auto expert on the consumer’s phone before the lot.
Research vehicles, plan payments, compare offers, get guidance, review paperwork, and own with confidence.
https://t.co/JcWPwv9v5m
GoldTrust is building an AI auto expert that works for the consumer, not the dealership.
Research the vehicle. Plan the payment. Compare offers. Get real-time guidance. Review paperwork before you sign.
Request private access:
https://t.co/yfr6V9YtT2
@CARandDRIVER EV cost is really a full ownership math problem: price after incentives, APR and term, insurance, home/public charging, miles driven, depreciation, and how long the buyer plans to keep it. Monthly payment alone misses too much.
@CarWhereHQ A discount is only the first pass. Buyers still need the out-the-door price, taxes/fees, APR, term, add-ons, trade math, and ownership horizon in one place before they know if the deal actually fits.
@MTSInsights Easier approvals are useful only if buyers can see the tradeoff clearly. Longer terms may lower the monthly number, but they can raise total interest and negative-equity risk. The payment is just one input; amount financed, term, APR, equity, and ownership horizon all matter.
@CarBizToday The best AI in retail auto should reduce uncertainty for both sides. If buyers understand payment range, tradeoffs, documents, and quote changes before they sit down, dealers spend less time re-explaining and more time building trust.
@CarBizToday 84 months can make the payment feel easier, but buyers need to see the full picture: total interest, negative equity risk, warranty overlap, and how long they plan to keep the car. The right deal is not just affordable this month; it still has to make sense years later.
@CarBizToday This is where buyer preparation matters too. If the customer already understands payment range, amount financed, add-ons, documents, and what changed from quote to contract, F&I spends less time rebuilding trust and more time confirming the decision clearly.
@MikeCalcara Exactly. The highest-leverage move is helping the buyer understand the deal before emotion takes over: pre-approval, OTD price, APR, term, trade value, add-ons, and F&I docs. Prepared buyers make cleaner decisions and usually have better dealership visits.
@mattsdriven Good advice. First-time buyers should also compare the full deal, not just approval: amount financed, APR, term length, total interest, add-ons, and OTD price. A lower monthly payment can still be the more expensive loan if the term stretches too far.
@PaulMillerMazda The best store experiences usually start before the buyer walks in. When consumers understand payment range, OTD price, fees, tradeoffs, and docs ahead of time, the visit gets faster and trust goes up for both sides.