Es interesante mas allá de que para quienes usan pc alto rendimiento no hace la diferencia. Esta bien que sea inhouse aunque se corto internet en tu casa y no sirve de nada .. ahora GPT activó CLOUD entiendo que es la nube para que corra todo al 99%. Aunqueeee la data queda en sus servidores. (Al final igual ya tienen todos los datos)
The future of institutional DeFi won’t be oracle-based bridging, it will be private bank and credit union subnets over warp messaging on @MetalBlockchain with digital identity.
Daniel interesante tu charla. Algo que hablas del minuto 50/51 en adelante, seguramente podrás encontrar alguna respuesta si puedes hablar con Allan @Allanamientos , un estudioso de eso que creemos es la pieza perdida.
Sería interesante tener una charla en su grupo.
Muchas gracias por compartir tu conocimiento.
All 27 Credit Union stablecoin pilots are deployed on XPR testnet. Metalytiks now reads it directly, so a new coin shows up the day it lands.
🏦 20 issuers matched — Gesa, OneAZ, Bay Federal, KeyPoint, Mocse, Desert Financial + more
💰 $39B+ combined assets across the ones we can size
👥 1.8M+ members, 10 states
🆕 newest coin landed this week — issuer still undisclosed
Every match is labelled confirmed or probable on the page 👇
https://t.co/DioztUFkfF
Follow the data
$XPR $METAL $LOAN $MTL
If you run a regulated fintech, the lending infrastructure question is not which protocol has the deepest liquidity. It is who is allowed into the market.
Aave and Morpho run permissionless markets by design. Any address can participate, and that is the point of them. Both have institutional routes as well: Aave's Horizon is a permissioned market for tokenized real world assets like treasuries and money market funds, and Morpho sits behind Coinbase's verified, custodial loan product. Both are real, and both point somewhere specific.
What none of them serve is the case in the middle. A fintech that wants its own verified customers borrowing against the crypto those customers already hold, under its own brand, without handing them to a competitor.
That is what @LOAN_Protocol is built for. Identity is enforced at the contract layer on XPR Network. A user verifies once through Metal Identity, and the chain itself is queried before that user can participate. KYC is not bolted onto the front end. It is a condition of the market.
That single design decision is what makes it usable as backend infrastructure for a business that answers to a regulator.
What the markets actually look like:
Supply stablecoins and earn a variable, utilization-driven rate. Across all history USDC has averaged 7.1% APY and USDT 8.6%. Over the last seven days both sat near 5.4%. Rates move with utilization, so treat history as context, not a forecast.
Borrow against what your users already hold. BTC and ETH at up to 70% LTV, XRP, ADA, HBAR, DOGE, LTC and SOL at up to 60%. That second group matters: Aave, Compound, Spark and Euler are EVM-only, and ADA, XRP, XLM, HBAR, DOGE and LTC have no EVM representation to list. It is a structural limit, not a roadmap gap.
Alternatives exist and I will name them. Coinbase launched borrowing against XRP, ADA, DOGE and LTC in February, wrapped and routed through Morpho on Base, custodial, US only, capped near 49% LTV. Home-chain protocols like Liqwid, Blend and Bonzo do it natively, one chain and one wallet at a time, with no KYC at all.
What LOAN does is put all of it in one venue, gas free for the user, with identity enforced in the contract, and available to white label.
$30.1M TVL on DeFiLlama. Larger than Liqwid or Bonzo individually, and it covers both of those chains plus XRP, DOGE, LTC, SOL, BTC, ETH and stables in a single integration.
If you run a fintech, an exchange or a wallet, your users are already asking for this. Coinbase shipping it proves the demand. The question is whether you send them somewhere else to get it.
https://t.co/vGudHtmyKU
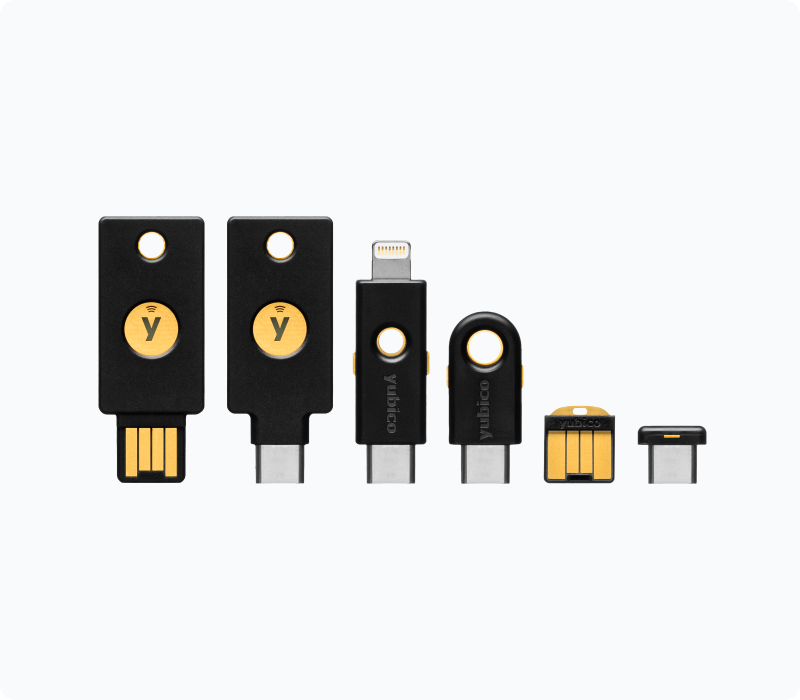
WebAuth Wallet & Chill - How to add a signing device 🔑
Imagine a crypto wallet you don't even need to install, where you can rock up to ANY computer and securely access your crypto without ever logging in?
All you need is your key or biometrics.
Here's how:
🚨 The new @MetallicusTDBN website is packed with signals most people will completely overlook.
🏦 30+ institutions in stablecoin pilots.
💰 $90B + institutional AUM.
👥 2.3M customers.
⚡ FedNow capabilities.
🤝 50 credit unions exploring digital financial infrastructure.
While others were selling narratives, Metallicus kept shipping.
https://t.co/i1nM2f69rH
Disclaimer: I am not employed by, sponsored by, or financially compensated by Metallicus. The opinions and content I share are based on my own independent research, analysis, and personal conviction regarding the technology and its ecosystem.
#KWYH #TDBN #XPRNetwork #FedNow #Stablecoins
Credit Unions will lead the way for America’s financial future. Money will begin to circulate locally again, empowering small business, and the common man. Blockchain is the permissionless rail that powers it.
Every bank will have its own blockchain, its own stablecoin in $XMD basket, and will run on $METAL L0, allowing communication without the need for bridges or costly/slow settlement. They interact on $XPR (A chain) to handle cross chain trading and lending. Goodbye ACH! 👋🤘🏽⚛️Ⓜ️
Cold wallets were the beginning of sovereignty over what you owned. Now that sovereignty is restricted. However, you have one of the best self-custody wallets, with no restrictions, no maintenance fees, and no limitations. @webauthwallet is the gateway to your sovereignty. 😎
🚀 ¡Para quienes siempre me preguntan cuándo damos un curso!
Esta vez, junto a la Universidad Sergio Arboleda de Colombia, vamos a brindar un webinar 100% gratuito sobre stablecoins. 🌎💸