📅 $TTAN reports earnings Tue, Sep 8.
Current signal: bullish Inverse Head and Shoulders (12-month window) detected at 93% confidence.
🤖 Automated post — shape-based signal; earnings are separate. Not financial advice.
https://t.co/PlcxBsxst2
$IREN | New Multi-Year Contract with Leading Frontier AI Lab $4bn Contracted ARR for 2026 Capacity; $1bn Operating ARR Today(1,)(2)$2.8bn GPU Financings Fund 90% of Associated GPU Capex
’Twas the night before $IREN earnings, and all through the Street,
Not a trader was resting, not one bull asleep;
The charts were all pulled up with tender care,
In hopes that strong guidance soon would be there;
The bears were all nestled, all snug in their shorts,
While visions of squeezes danced through their thoughts;
And degens in hoodies, and analysts too,
Had settled their models for one final review,
When out on the ticker there arose such a clatter,
Everyone refreshed to see what was the matter;
Away to the filing they flew like a flash,
Tore open the print and searched for the cash;
The glow of the datacenters lit up the night,
Gave the luster of midday to megawatts bright;
More rapid than eagles the headlines they came,
As traders all whistled and shouted its name:
“Now AI! Now GPUs! Now capacity deployed!
Now backlog! Now contracts! Now guidance enjoyed!”
He spoke not a word, went straight to the tape,
And numbers rolled out in beautiful shape;
Then rising up quietly, out of sight —
“Happy earnings to IREN, and to all a good night!”
$IREN Q2 earnings preview:
First, the (for now) least important number:
Bloomberg revenue consensus: $138.6M
Q2 revenue will be made up from three components:
1. Bitcoin mining
2. AI GPUs already billing at the end of Q1
3. AI GPUs commissioned during Q2
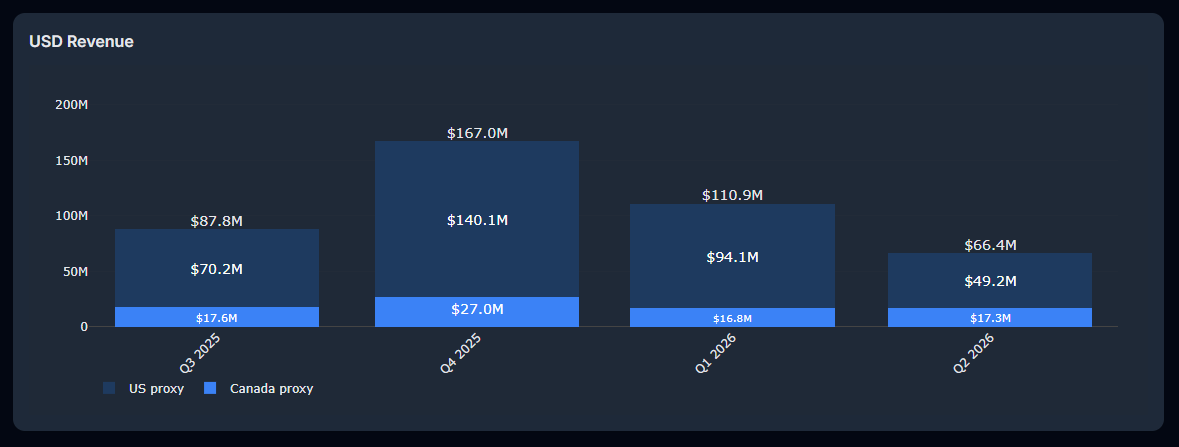
1. Bitcoin revenue: ~$66.4M
IREN’s Bitcoin wallet activity provides a close proxy for mining revenue. For Q2, I tracked approximately $66.4M.
2. Existing AI revenue: ~$77M
At the end of Q1, IREN reported $307.95M of remaining performance obligations expected to be recognized within 12 months.
Because contracts enter RPO once they commence, this is also a reasonable proxy for the ARR already billing at quarter end.
Assuming that revenue is recognized evenly because of yearly contracts:
$308M / 4 = $77M in Q2
3. Newly commissioned AI revenue: ~$0–24M
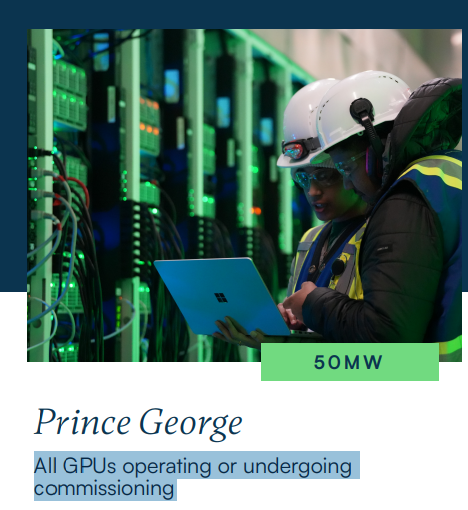
IREN has said Prince George will generate approximately $500M of ARR.
If roughly $308M was already live at the end of Q1, that leaves approximately $192M of ARR still commissioning.
On May 7 (earnings), management said all Prince George GPUs were either operational or being commissioned:
Quote:
“At Prince George, all air cool GPUs have now been delivered and are either operating or undergoing commissioning across the 50 megawatt site.”
The key question is when that remaining $192M began billing:
If:
No Q2 billing: $0M revenue
Mid-June start: $8M revenue
June 1 start: $16M revenue
Mid-May start: $24M revenue
Because these GPUs were already installed and commissioning as of May 7th, my base case assumes billing began in June, producing $16M ($192M/12) in revenue.
That puts my Q2 revenue estimate at:
$66.4M + $77M + $16M = $159.4M
Versus Bloomberg consensus of $138.6M.
(EPS will be impacted by the non-cash hit by bitcoin miner impairments from the miners they've disconnected)
@DudeWhoInvests 1. Market oversold software for AI
2. Software is now NOT competing against AI but are now leveraging it
3. $CRM is still undervalued in comparison to what they’re doing
4. $CRM bottomed out
From $380 to the 52 week low of $190. $CRM almost doubled their EPS. 13% gain is just the start! Agentforce + Claudeforce will dominate the market. Everyone uses $CRM, Claudeforce & Agentforce just leverages users data and is bigger than most people realize. Zoom out!!
Markets overreacted to $KLARN
KLARNA has grown beyond BnPL
- Mobile Prepaid Service (AT&T)
- BNPL
- Credit Card
As cost of living rises, $KLARN is well positioned to boom. If the Market crashes and there’s an economic downturn, Klarna also benefits. This one is common sense IMO
$KLAR at $15 way too cheap. Makes sense to be down on the guidance, but this is an overreaction in my opinion. With the pending lawsuit payout from Google, giving close to 0 value to the actual business, which is insane.