🚨 Another crypto neobank reportedly hacked, just like i said.
More than $600K has reportedly been drained from user accounts at @avici, a Solana-based neobank.
And this is exactly why I keep saying:
Don’t choose a crypto card just because an influencer is promoting it.
The crypto card/neobank market is moving insanely fast.
New cards launch
Influencers promote them
Users deposit money
Everyone talks about cashback, rewards, FX rates and perks
But the most important question is often the one nobody asks:
How safe is my money?
Who actually holds the funds?
What security infrastructure is being used?
Has the company been battle-tested?
What happens if the platform gets hacked?
Is there insurance or any protection?
Who is ultimately responsible when something goes wrong?
A 5% cashback rate means nothing if you lose 100% of your funds.
As more people start using stablecoins as everyday money, security, custody and trust need to become first-class metrics when comparing crypto cards and neobanks.
Don’t blindly trust the hype.
Do your own research before putting serious money into a new platform.
The most underrated crypto card right now might be @BitgetWallet
A few numbers caught my attention (latest on-chain data, 7-day average):
• ~$165,500 in daily card volume
• ~3,900 daily active card users
• ~$35 average daily spend per active user
#5 among named crypto cards by daily active users
RedotPay leads with ~17,600 DAU.
What’s interesting is the usage pattern.
This isn't just a card with users signing up for rewards. There is recurring retail spending happening every day
Bitget Wallet also has 100M+ users.
If even 1% of that user base eventually used the card, that's 1M card users.
That would put it in a completely different league.
The product itself is also interesting:
• Up to 3% cashback
• Cashback can be paid in BTC or Gold
• Tokenized stocks like NVIDIA (NVDA) and Tesla (TSLA)
• Built into the Bitget Wallet ecosystem
That cashback structure is still pretty unusual among crypto cards.
My take:
Safety: 5/5
Risk of closure: 1/5
The interesting part isn't where Bitget Wallet Card is today, It's the distribution behind it.
100M+ wallet users + a card with real daily usage is a pretty powerful combination if they can convert even a small percentage of that base.
One of the crypto card ecosystems I'm watching closely over the next few years
Never tried a crypto card before? Start with a $0 card
Meet @Nexo Card
No monthly fee
No annual fee
No inactivity fee
Yes you read it right
You can sign up, activate a virtual card, and use it for
→ Online shopping
→ Netflix & subscriptions
→ Everyday purchases
→ Apple Pay & Google Pay
And it costs:
$0/month
$0/year
$0 inactivity fee
You just need $50 in your Nexo account to activate it.
And that $50 is still yours. You can spend it.
You can also use the card with Apple Pay and Google Pay.
If you've been curious about crypto cards but never actually tried one..
This is a pretty damn easy place to start
Nexo is one of the oldest crypto card company operating since 2018 with 7+ billion in asset management
90% of crypto cards & neobanks will die
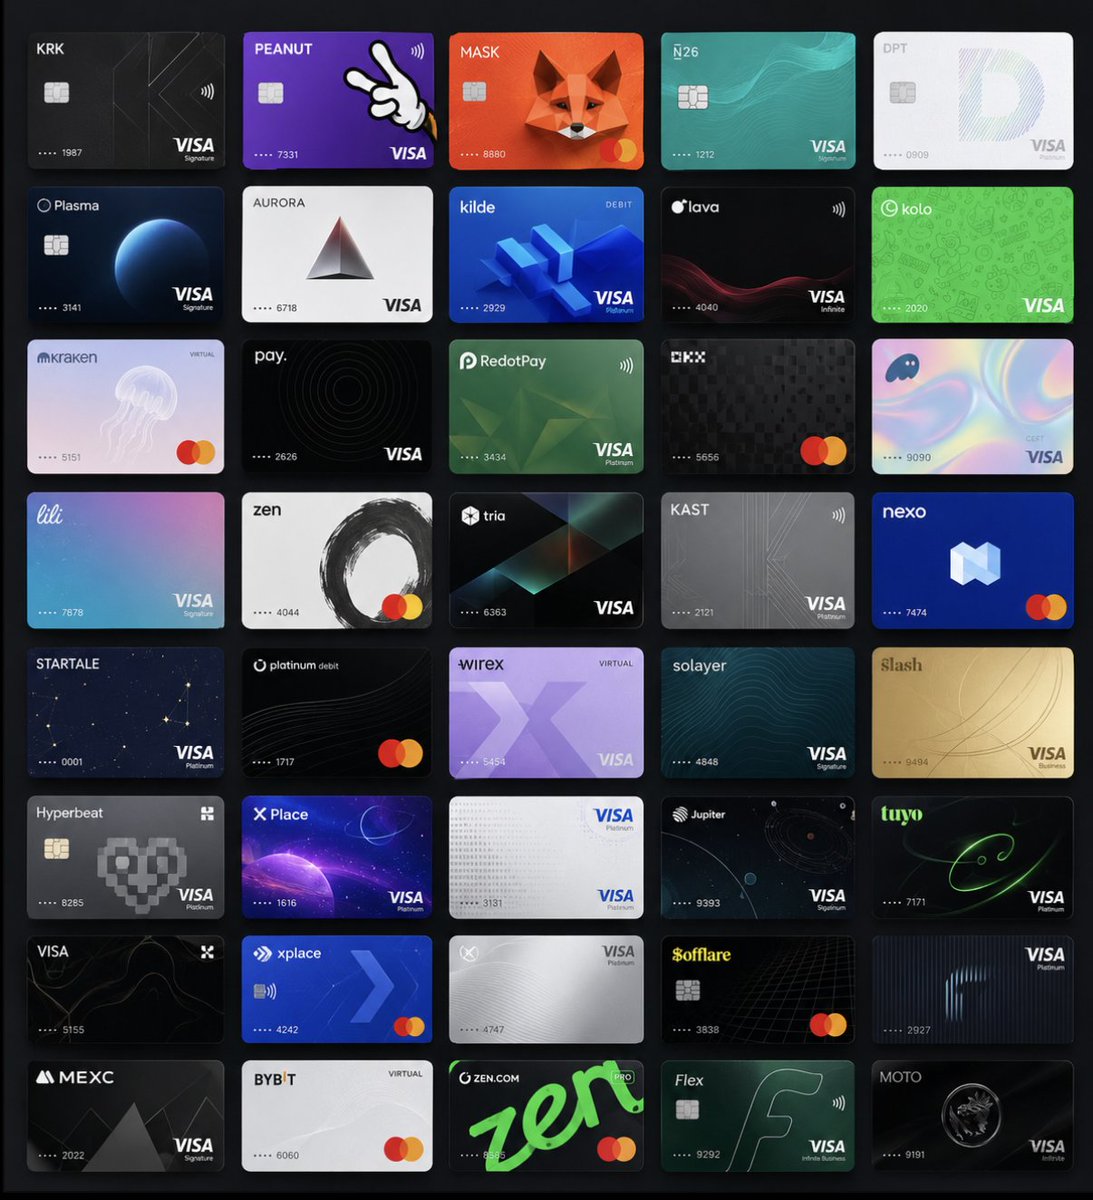
Recently, @0xVishnya posted a list of ~250 crypto cards.
My bet: over the next 2–3 years, 90% of them will either:
A. Die, shut down or disappear
B. Get hacked or suffer a serious data/KYC breach
C. Change their terms, fees or rewards dramatically
And honestly, you don't want to treat your bank like a crypto app
You shouldn't move your money to a new card just because it offers 1% more cashback when you don't even know how the company handles your funds
Stick with the OGs
A few I personally keep an eye on:
@ether_fi — One of the strongest crypto-native cards, especially for users who want to borrow and spend.
@Nexo — 8+ years in the market. Established, mature and high quality. You could call it the AMEX of crypto.
@KASTxyz — Strong retail-focused crypto card
@BitgetWallet — Massive user base and significant transaction volume. One of the more established names in the space.
@wirexapp — One of the oldest players in crypto cards, with competitive rates and a long operating history.
And I'll say this again:
Don't chase 1% extra cashback from a company you don't trust with your money.
When it comes to financial products, trust > cashback.
Keep your money where the company makes you feel safe.
Hardware wallets were never safe, that why i never used one
If you ever try asking claude / Chatgpt, he will push for it & even a lot of websites call it "SAFEST way " to keep crypto
But I still prefer cold storage, with a private key or keystore password, over anything else
Once you connect your wallet to a computer, website, or hardware device, it’s no longer truly safe
the trading discourse around ogs and plumbers can be summed as:
trading with the benefit of hindsight is easier than trading against an unknown future
yeah eth was 90 dollars but were u buying any?
oh 2022? sol hit 8 dollars did u full stack?
oh 2023? hype hit 3 dollars post tge did u full stack?
the past is for learning u make money on what happens next not complaining about what happened before.
🇺🇸 This is the Tesla Model Y in full self-driving mode on the roads of Austin.
But the interesting part isn't the car; it's what FSD could eventually do to our concept of distance.
Imagine living 200 miles from your office and barely caring about the commute because the car handles most of the driving.
Imagine being able to cross states overnight while you relax, work, or eventually sleep, turning journeys that once required flights, hotels, and careful planning into something approaching a very long elevator ride.
For more than a century, cars gave us freedom of movement.
Autonomy could give us freedom from the driving itself.
Writers: Mhedi, Ian
One of the worst ways to get cashback:
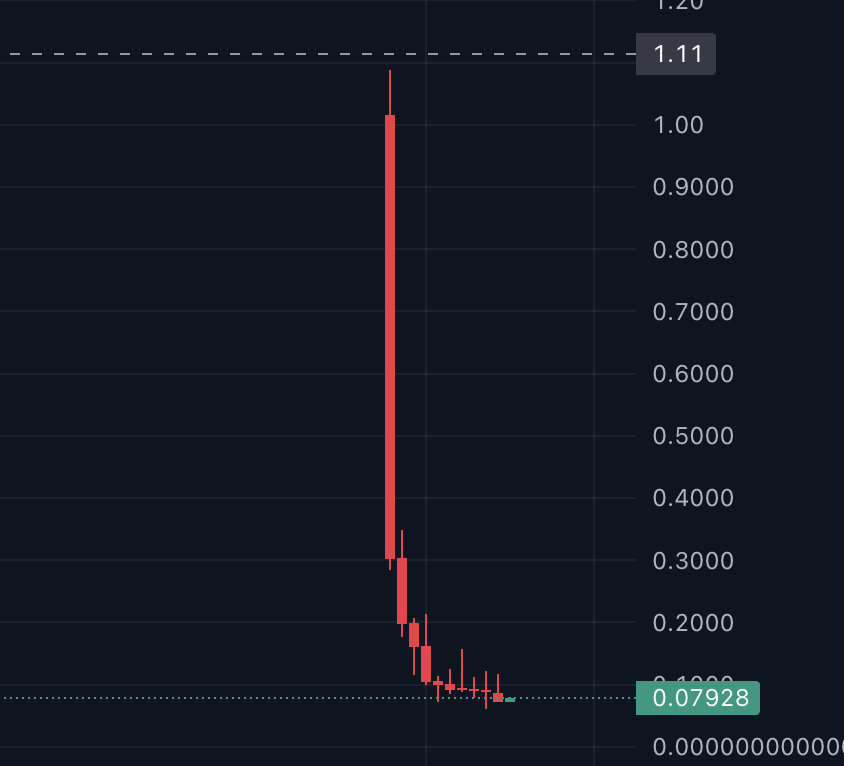
Getting paid in the token of the company that looks like this
If plasma:native keeps going down, your “cashback” is literally losing value
45% of the user in @plasma are not selling it to usdt, this is the only use case of plasma:native
Honestly, getting cashback in USDT is still better than this
But the best model is asset-back cashback
Get cash back in BTC, SPX or GLD
Your cashback stays in an asset that actually goes up
This is one thing I think @Bitget is doing this right
Most people are using crypto cards wrong
After tracking 100,000+ whale wallets, one pattern stands out
Whales rarely sell their BTC or ETH when they need cash
They borrow against it instead
This is why you see a lot of whales using "Borrow against crypto" on @ether_fi
Every time you sell, you give up the upside
If BTC doubles next year, you already sold it
Borrowing unlocks liquidity without giving up your position, you keep your coins, keep the upside, & repay when it suits you
Atm i am using @Nexo to borrow against my crypto
Paying around 1.9% APR
IMO, this is the biggest use case of crypto cards
Which platform do you use to borrow against your crypto?
🇺🇸🇮🇷 Trump may have promised to carry out one of the biggest strikes on Iran so far, but military logistics may have indicated it was never going to happen.
Fmr U.S. Navy Malcolm Nance argued there were glaring inconsistencies between what Trump threatened and what the U.S. was positioned to do.
"The B-1 bombers in England weren't staging.
There was no mass of in-flight refueling tankers arrayed across the Atlantic and across southern Europe."
@MalcolmNance
To the Neobank & Crypto Card community:
I see a lot of people promoting hundreds of crypto cards, almost like collecting Pokémon cards
The reality is that 90% of them probably won't exist in the next 2 years
We all have seen what have happened to @Cypher_HQ_@KulipaXYZ@ready_co
A lot of them will either shut down or will close services, or maybe get hacked, or will have KYC data leaked
If we're onboarding people into crypto, we have a responsibility to recommend products we genuinely trust
If you're moving serious money, not just paying for a coffee or an AI subscription, here's what I look for
1. Be in the top 5-10 by users and volume
Volume can be faked. Users can't
2. Strong backing
Ideally backed by hundreds of millions in funding with enough runway to survive
3. Time in the market.
I rarely trust brand new companies with my money
4. Proven founders and team - A strong track record matters
Few of my fav and safest ones
Borrow Against Crypto
• @ether_fi
• @nexo
Crypto Cards
• @RedotPay
• @wirexapp
• @BitgetWallet
Crypto cards just did their first $1.1B traced month
That's the highest monthly volume we've tracked so far
Next goal $10B/month
To add the next $8.9B in monthly volume, I think the industry needs to focus on a few things:
• Let users use crypto, stocks, and gold as collateral while spending
• Make it possible to pay bills directly through mini apps built into the card experience
• Clearly show where the card works, country by country, inside the app and on the website
• Give people more reasons to keep their money inside the card instead of constantly moving it back to a bank - Very important - APY
The winners won't be the cards with the most features
They'll be the ones that become the default place where people store, spend, and manage their wealth