Cheers to a happy & healthy 2026! Below are all timestamped Long/Short ideas for 2025 and vs respective benchmarks. Appreciate everyone's support.
Our average return per idea (active & closed ideas) is 16%. 76% hit rate. Short ideas accounted for 41% of all ideas.
For tech research subscription, see below. We're adding a new product in 2026, geared for traders. Stay tuned.
https://t.co/QtC6ld4U4Y
$NVDA $CRWV $NBIS $SE $BABA $TCEHY $AAPL $POET $ONTO https://t.co/sbBK0aBoWN $MU $DIDIY $SITM $MNSO $WYFI $MPNGY $XIACY $VRT $VRNS $PDD $AMAT
I still think Ian Buck is a strong option at NVDA. But here’s a crazy thought: I wonder if Lisa $AMD could be offered the $NVDA job - NVDA acquires AMD. Regulators would probably block it so this is only a dream 💭
It's almost 1:30am in London - I will be on Bloomberg TV to talk $NVDA and Jensen @BloombergTV . Tune in. I doubt many investors are sleeping much tonight.
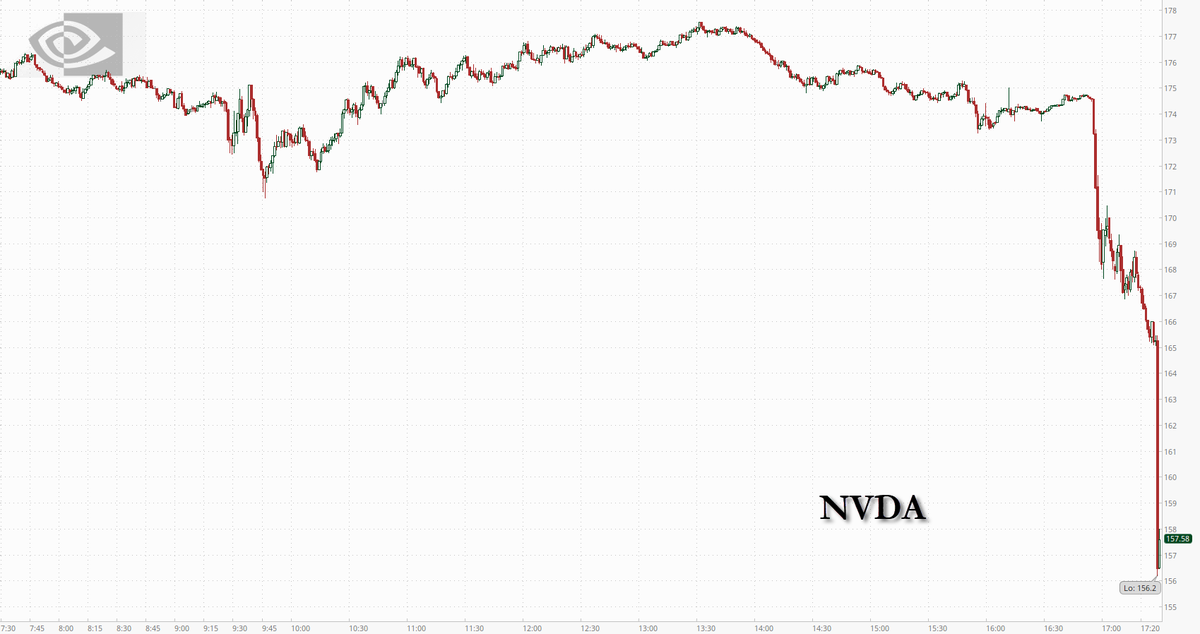
Good thing we got out of $NVDA 2 weeks ago before it started cracking. Embarrassing day for Jensen. If he is out of his own company, it will have ramifications for the entire global supply chain and export controls.
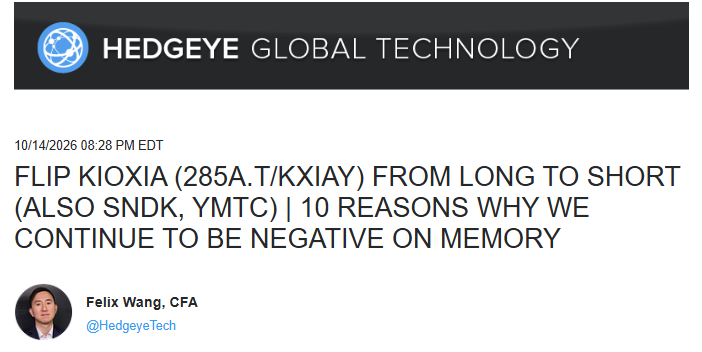
We continue to be defensive. We exited $NVDA Long on a Rubin issue. Last week, we flipped one of the hottest stocks in the world - Kioxia - from Long to Short.
$KXIAY $285A.T has been a big winner for us this year - up ~115% since our Bull call in March 2026. But the next 6-12 months will be a different game.
For access:
https://t.co/QtC6ld4mfq
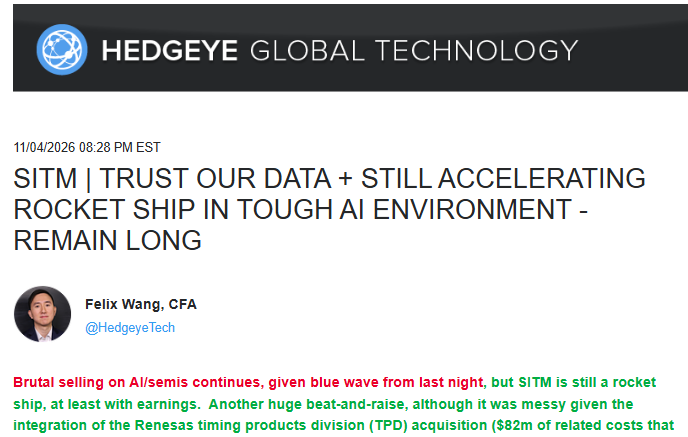
We have good data on $SITM - despite brutal selling in AI, this is still an accelerating rocket ship - we remain Long
Sign up here: https://t.co/vRMxG5xtjH
Comprehensive list of hedge funds blowing up this week, getting large redemptions, or shutting down PMs:
- Axebrook
- Walleye
- Engineers Gate
- Lone Pine
- Millennium internal pods
- Verition pods
- Samlyn
Letter from Walleye closing internal funds below
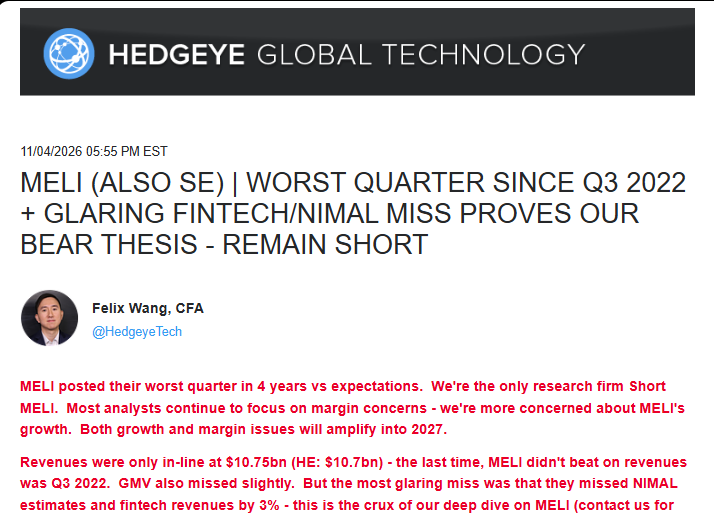
Non-AI stocks are soaring... how about a non-AI name that is plunging, instead of soaring in this market? $MELI. We're the only research firm Short MELI.
$MELI posted their worst quarter in 4 years vs expectations. Most analysts continue to focus on margin concerns - we're more concerned about MELI's growth. Both growth and margin issues will amplify into 2027.
Revenues were only in-line at $10.75bn (HE: $10.7bn) - the last time, MELI didn't beat on revenues was Q3 2022. GMV also missed slightly. But the most glaring miss was that they missed NIMAL estimates and fintech revenues by 3% - this is the crux of our deep dive on MELI (contact us for our deep dive presentation from Sept 2026). This also means MELI reported its first miss on fintech revenues since Q3 2024.
The question now is how bad will competitor $SE's report be next week?
Sign up here: https://t.co/QtC6ld4mfq