A dedicated planning-first fiduciary financial advisor who specializes in medical professionals and real estate investors. DM for a free consultation call.
I fell in love with financial planning back in 2011, and I fell hard, just a few days into my first week at the firm in Markham.
I walked by my manager's corner office where he was catching up with one of the branch's top advisors. He introduced us, and I asked for his secret sauce.
He grabbed a pen and a sheet of paper.
Then he sketched his whole process in under a minute.
Four quadrants.
Cash went in the top left, and living benefits went in the bottom left.
Retirement took the top right, and financial security at death took the bottom right.
Then he drew a big circle around the square and wrote estate on top.
I was convinced.
That one sketch covered more than all of the conversations I had in my life up until that point.
And I had already spent 2.5 years at RBC by then.
He never earned his CFP designation.
Yet he did more planning, and got more families to take action, than 90% of the advisors I came across in those first five years.
So months later, I taught that sketch to two new advisors I recruited.
The first helped a young professional buy term life insurance and critical illness coverage.
After seeing a needs analysis and a clear recommendation summary, that client also transferred their bank RRSP account over.
The second secured a meeting with his aunt and uncle.
Using some basic tools available at the time, he showed them a retirement projection.
He also showed them how past performance would have differed with a portfolio that matched their risk tolerance and minimized downside risk.
They got clarity for the first time, and agreed to switch.
I eventually helped many other advisors with their own planning needs.
Three come to mind right away, each preparing for their own transition to more time with their significant others and families (transition planning works for advisors too).
All three are really enjoying their time away from this ever-changing business.
So what is real financial planning?
It's getting a clearer picture of your entire financial life and realizing what's possible with your money.
Watch this clip.
And if your financial house needs some remodeling or a major renovation, check out https://t.co/nFFYHLo8w7 and book a call with Crimson Financial today.
#CrimsonFinancial
#CrimsonCarePlan
#CertifiedFinancialPlanner
#FinancialPlanning
#WealthManagement
I caught up with a friend yesterday, and we got talking about why those in client facing advisory roles should be able to defend their homework.
He told me about a tax specialist he chatted with recently.
That specialist will only use a piece of software if he understands exactly how it arrives at its numbers.
I think about this all the time.
When I sit down with a client, I want to lay out my analysis, my recommendation and the benefits in plain language.
A former manager gave me a test for this years ago.
Could you defend your advice if a reporter put you in front of a camera on the 6 o'clock news?
It still works.
So I also encourage clients to read the websites, reports and whitepapers I cite.
Then they can see for themselves that the advice comes from reputable sources.
As a financial planner who has taken a fiduciary pledge, I have two duties that go together.
I have to put the client's interests first, and I have to be completely transparent about how I reached my conclusions.
Think about the other professionals you trust.
Would you want your lawyer to explain the fee breakdown and the case precedents behind their strategy?
Would it help to hear your accountant describe how clients in similar situations benefited from their advice?
Most of us would say yes.
And the same goes for decisions about your compensation, RRSP, TFSA, non-registered accounts and insurance, where one wrong turn can cost you thousands or more over a lifetime.
You should know what is being recommended, why it fits your plan, and how it will actually be put into motion.
Is your financial advisor showing you the what, the why and the how?
If not, you may want to look for a planning-first one who does.
That is what builds trust over time.
When you understand your advice, you can actually act on it.
#CrimsonFinancial
#CrimsonCarePlan
#FinancialPlanning
#WealthManagement
#PhysicianFinance
#RealEstateInvestors
Happy @AnthropicAI IPO day!
Just watched the latest "Artificial" movie trailer too.
It's about Altman and OpenAI.
Today, Claude goes public.
We should all be worried right?
I recently had a conversation with a millennial DIY investor who is all in on the S&P 500.
I get it.
America has the most diversified economy in the world, and it has done very well since COVID hit in March 2026 (up 148%).
Canada, on the other hand, makes up only 3% of the global stock market.
Our market is mostly financial, energy and materials companies, and it is still up 121% over the same stretch.
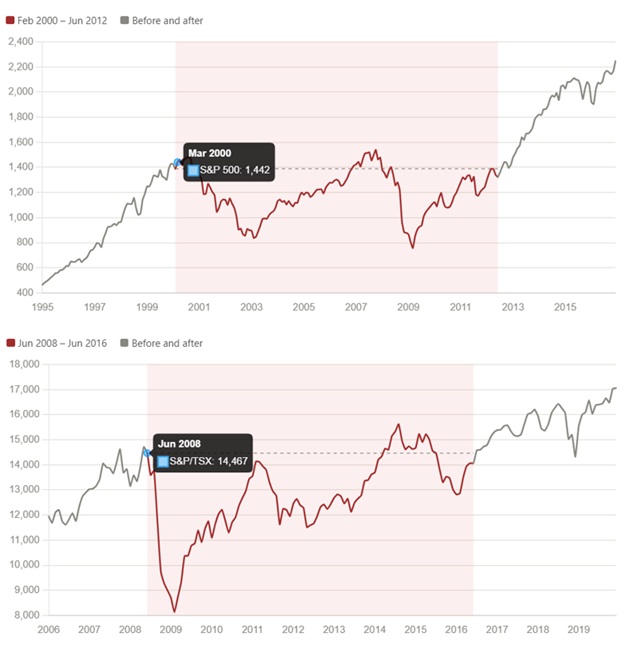
But has the S&P 500 always gone up?
No.
Between February 2000 and June 2012, the index did not grow for 12 long years, excluding dividends.
Holding only the S&P 500 in your RRSP and retiring right before that would have been a challenging scenario.
It happened in Canada too.
From June 2008, the TSX dropped almost 45% into 2009, stayed flat for 8 years, and did not really climb until early 2017.
For a recent international example of volatility, even in index investing, look at South Korea.
The KOSPI rose 70% last year, then shot up another 96% by June, and it has fallen 45% since.
It was the highest performing country last year, and it is still #2 year to date.
So what does that tell you?
Markets work in the long run, and so does diversifying across geography and company size.
Add regular saving and staying invested through the flat years in the right tax-sheltered accounts, and you are more likely to have investing success.
Do you know how much of your portfolio sits in one country?
A comprehensive financial plan can show you, and a client-first advisor can help you stay invested when markets test you.
Diversify, invest regularly, and stay the course.
#CrimsonFinancial
#CrimsonCarePlan
#FinancialPlanning
#WealthManagement
#RetirementPlanning
#PhysicianFinance
#RealEstateInvesting
Did anyone predict how the AI bubble may burst due to leadership risk?
Is that the type of risk this Jensen scandal is called?
#Indexing#PassiveInvesting#RiskManagement
.@JensenHuang hope you read this. I convinced my Dad to buy your first video card when nobody knew what NVIDIA was back in 1996 for our new family computer.
Then I built one again in 2020 a few months into COVID, and bought another NVIDIA card again.
Thank you for the gaming, and more recently AI memories.
Keep your head up.
#AI
#Technology
#Loyalty
On Tuesday morning I stood in a room full of fintech and entrepreneurship students at @YorkU_Markham, which is not where most mid-40s journalism and history grads end up.
How did I get there?
The school and their professor gave me a chance to explain why I created an independent, planning-focused firm.
I also shared my processes, the technology I use, and why I left corporate to become an incorporated business owner myself.
I connected my laptop, and my slides appeared on two large screens.
Then I walked them through a typical consultation call.
After that, I showed them a real plan delivery meeting presentation, the same one a client would see across the screen from me.
Clients book themselves through a self-booking system.
Every video call has an AI notetaker that captures everything said and gives me unbiased coaching feedback (it is tougher on me than I was on any advisor I used to coach).
Onboarding and file sharing run through a secure Canadian digital platform.
My portfolio analytics tool generates report cards, and a York University professor created it, though nobody in the room had heard of her.
A Canadian-built CRM syncs with my email and my AI transcriber.
I also reference an industry bible (IYKYK) now in digital format too.
I build and use slide decks for every plan.
And I use AI a lot.
Have you ever wondered what happens behind the scenes before your advisor recommends anything?
For me, this kind of coordination helps a hard-working couple see their current situation, net worth, issues, solutions and an action plan in an easy to digest format.
I love educating people on personal finance, whether they are 21-year-old students, doctors considering their transition, or landlords who want to know their options to sell or pass on their properties.
The industry is crowded, and agentic AI is changing how everything gets done.
I am grateful there is still a place for me to make a difference.
Real connections are still best made in person, like in a classroom.
If you want financial clarity and results, visit https://t.co/nFFYHLo8w7 and book your call today.
#CrimsonFinancial
#CrimsonCares
#FinancialPlanning
#WealthManagement
#PhysicianFinance
I want to stay positive with this one, but it is hard after co-hosting a webinar last week and reflecting on my messaging and examples.
One comparison I made was how fragmented and uncoordinated health care is in Canada.
For patients, it looks a lot like the financial industry does for clients.
Apparently, doctors are now reaching out to other doctors on Facebook and WhatsApp to find out who has a shorter wait time for a specialist.
That is the workaround.
It is sad to know that the public system will sometimes react to your health situation, but it will never be proactive.
Back to the financial industry.
To me, the public health care system is a lot like getting financial advice at your local bank or credit union branch.
Most of it is reactive, and you usually walk in when something has already happened.
Is your personal and corporate cash flow situation coordinated with your retirement strategy?
Have you ever thought about what would happen if you got really sick or hurt and couldn't work full time for 1 to 4 years?
Does your accountant ever speak with your financial advisor?
For most busy professionals, the answer is no, and those gaps can potentially cost hundreds of thousands or more over time.
Coordination is what protects income and family stability over the long run.
That is what I saw and felt during a recent visit to a private health clinic in downtown Toronto.
The team explained how they take their time, assign a coordinator and a doctor, use the latest screening technology, and even follow up year round.
If this sounds appealing to you, it may be time to take a closer look.
Visit https://t.co/nFFYHLoGlF to learn how we serve busy professionals and deliver proactive wealth and health.
#CrimsonFinancial
#CrimsonCarePlan
#CrimsonCarePlanPlus
#BusinessOwners
#FinancialPlanning
#WealthManagement
#MedicalProfessionals
#PhysicianFinance
Core, balance, and stretch is a class I tried earlier this year, and I finally went back on Saturday morning to see if my body still remembered it.
Have any of you tried a class like this lately?
Julia, the instructor, said my body (especially my spine) would thank me.
It was a challenge.
We balanced on a cork brick and lifted one leg slowly, then the other leg.
She made us do pistol squats too.
Then we got down on one knee, stretched one arm out, then stretched our legs and twirled them one at a time.
To finish, we lifted both arms above our heads and tried to control our breathing while tightening our core at the same time.
The class description said it was about body awareness.
So now I turn to you.
How aware are you of your personal financial situation?
Does everything feel fine, or are there some aches and pains you keep ignoring?
Are you getting a good night's rest every night?
Are your investments overlapping or are they diversified?
Do your insurance policies cover your current lifestyle?
Do you see yourself working for another 15 to 20 years?
Fitness experts stress how important a strong core is for balance, movement, and avoiding injury.
As a fiduciary-pledged financial planner, I recommend the same for your finances.
For me, that core is steady cash flowing into the right accounts, the right coverage, and a plan that matches when you want work to become optional.
When the core is strong, a health scare, a market crash, or a bad tenant is much less likely to knock you over.
If you would like a check-up, visit https://t.co/nFFYHLoGlF and book your review call, so your plan can carry you comfortably through the next few decades.
#FinancialPlanning
#WealthManagement
#RetirementPlanning
#MedicalProfessionals
#RealEstateInvesting
I attended the latest @sickkids Foundation Professional Advisors Network breakfast last week, and left even more motivated to help than when I walked in that morning.
The topic of the day was tax-efficient giving, but the speech from Chris Marshall, a SickKids parent and fellow financial advisor, stayed with everyone in the room.
He told the story of his baby boy Lucas, who developed heart problems soon after birth a few years ago.
They rushed him to SickKids a few times because of complications, and eventually Lucas received a heart transplant.
I did not even know this was possible at such a young age.
A few days later, the cost of giving birth in the US came up in my friends' group chat.
Apparently, costs range from $15K to $50K USD, which is up to about $68K in Canadian dollars.
What about an organ transplant and post-surgery care for a baby?
Over $2M USD.
At SickKids, families like Lucas's are covered.
Newsweek and Statista recently named SickKids the best children's hospital in the world for a second year in a row, and Lucas's care is a prime example of the work they do.
But they cannot help babies like him, and many more children across Ontario and beyond, without support from the community.
If the federal government can hand our hard-earned tax dollars to other countries, we can lead by example and give to organizations here that make a real impact on the next generation.
Giving well also takes planning, because some strategies can lower your after-tax cost by much more than you would expect.
Crimson Financial can help you give more now and later, with lower after-tax costs and a plan your family understands.
Visit https://t.co/nFFYHLo8w7 and book your free consultation call.
#CrimsonFinancial
#CrimsonCares
#FinancialPlanning
#TaxPlanning
#CharitableGiving
We're now 4 hours away from Crimson Financial's first webinar for busy doctors with physician/researcher/author Dr. Ketan Kulkarni!
Two fiduciaries with one mission.
Can I stop working in 8 years?
How much can I spend without running out?
Am I paying too much in taxes?
Will I be OK?
If you got 45 minutes to learn, we're ready to educate.
Come join us at 4pm EST!
Registration link in the comments.
#CrimsonFinancial
#CrimsonCarePlan
#TheSavvyPhysician
#PhysicianFinance
#MedProfessionals
#FinancialPlanning
#FinancialFreedom
#FinancialLiteracyMonth
#TalkMoney
#FLM2026
@sam_barber_ifa I've had a client sell their company 10 years later, another get outsized returns since switching from their bank advisor duo, and another buy a bigger house, became a father and a landlord all in the same year.
It's really cool to play a part in people achieving their goals.
I fell in love with financial planning back in 2011, and I fell hard, just a few days into my first week at the firm in Markham.
I walked by my manager's corner office where he was catching up with one of the branch's top advisors. He introduced us, and I asked for his secret sauce.
He grabbed a pen and a sheet of paper.
Then he sketched his whole process in under a minute.
Four quadrants.
Cash went in the top left, and living benefits went in the bottom left.
Retirement took the top right, and financial security at death took the bottom right.
Then he drew a big circle around the square and wrote estate on top.
I was convinced.
That one sketch covered more than all of the conversations I had in my life up until that point.
And I had already spent 2.5 years at RBC by then.
He never earned his CFP designation.
Yet he did more planning, and got more families to take action, than 90% of the advisors I came across in those first five years.
So months later, I taught that sketch to two new advisors I recruited.
The first helped a young professional buy term life insurance and critical illness coverage.
After seeing a needs analysis and a clear recommendation summary, that client also transferred their bank RRSP account over.
The second secured a meeting with his aunt and uncle.
Using some basic tools available at the time, he showed them a retirement projection.
He also showed them how past performance would have differed with a portfolio that matched their risk tolerance and minimized downside risk.
They got clarity for the first time, and agreed to switch.
I eventually helped many other advisors with their own planning needs.
Three come to mind right away, each preparing for their own transition to more time with their significant others and families (transition planning works for advisors too).
All three are really enjoying their time away from this ever-changing business.
So what is real financial planning?
It's getting a clearer picture of your entire financial life and realizing what's possible with your money.
Watch this clip.
And if your financial house needs some remodeling or a major renovation, check out https://t.co/nFFYHLo8w7 and book a call with Crimson Financial today.
#CrimsonFinancial
#CrimsonCarePlan
#CertifiedFinancialPlanner
#FinancialPlanning
#WealthManagement
I knew it would be a sunny Fall day in central Ontario, so I planned a drive up to the Blue Mountains with my kids and my partner.
I had not been there with my kids in ages, and it would be my first time there with my partner.
We hopped in the car and picked an unhealthy spot for lunch.
Then we got tickets to the Ridge Runner Mountain Coaster, which I highly recommend.
After that, it was time for a hike.
There was a big sign at the base of the trail.
Halfway up, though, there were no clear directions on where to go.
You could hike back down the way you came, keep going up, or cut across to the side.
So I loaded the AllTrails map on my phone, turned on the GPS, and followed the dotted line.
My partner did not want to.
She insisted there must be another way to go up and back down.
I convinced everyone to follow me, even though the dotted line meant hiking way further up and over before we could descend.
Some parts were quite steep too.
Between the map, the GPS, and my understanding of how the two work together, I got all of us back down safely.
They all said it was a good hike.
And I agreed.
Financial planning and advising work the same way.
Many professional families start with a big sign at the base, like an old term life insurance policy, a TFSA full of cash, or a growing non-registered account with a mix of securities inside a corporation.
Then, halfway through life, the directions get less clear.
And it is human to take the easier path.
Should you keep paying yourself dividends, or take more salary?
Should you buy more coverage, and if so, what type, how much, and for how long?
When can I stop working if I want to?
AI can answer questions about products and strategies in less than a minute.
But the map it creates is only as good as the questions you ask, and the path is smoother when an experienced guide is right there with you.
I have spent many years guiding people through those steep parts.
That is how I use technology, experience, and human intuition in my work.
If your financial trail has a few unmarked turns right now, visit https://t.co/nFFYHLo8w7 and book a call so we can map the way down together.
#CrimsonFinancial
#CrimsonCarePlan
#CertifiedFinancialPlanner
#FinancialPlanning
#WealthManagement
#RetirementPlanning
#FinancialFreedom
#RiskManagement
#PhysicianFinance
I saw a post recently from a friend of a friend of a GoFundMe page for a doctor in his 40s who left behind a spouse and three kids.
The fundraising target would have covered two months of expenses at most.
The surviving spouse now has about six months covered, thanks to their community.
Is that enough?
Then yesterday morning, I heard on the radio that a fire broke out a 15-minute drive from my house.
It started as a vehicle fire, then spread to two homes.
A father in one of the houses died.
Both stories made me reflect on what I did when I became a father for the first time 16 years ago.
Review my risks. Buy life insurance.
Recently, I booked a visit to Pumpkinville at Sherway Gardens with my kids.
I did not check the weather when I booked it, and it rained the whole time we were there.
The point is good people pass away way too young, and rain happens.
We still had a brief, but good time taking photos like this one.
And you can't see it, but you're looking at over $2.4M of life insurance coverage.
$2M of it is on me, for their mother.
The other $400K covers my two children (more than most adults I come across carry).
Why do my kids have their own policies?
I'll save that for a future post.
Now back to my own protection, and why I put it in place as a new father.
When did you last review who depends on your income, and what they would have if you were gone tomorrow?
Group coverage through work rarely answers that question for a family of four.
And if you're an incorporated business owner with a family and staff, it's up to you.
After 179+ years of existence in this country, life insurance still gets a bad rap.
Death is one of the two guarantees in life.
But here's a friendly reminder, life insurance is all about love.
It's for the people you care deeply about, so that if you're gone too soon one day, they can cherish the memories and still have the means to make new ones without you.
Crimson Financial is contracted with 12 insurers to help you get the right coverage at the right price.
Check out https://t.co/nFFYHLo8w7 and book your free consultation call today.
#CrimsonFinancial
#CrimsonCarePlan
#BusinessOwners
#CertifiedFinancialPlanner
#FinancialPlanning
#WealthManagement
#LifeInsurance
#RiskManagement
As a fiduciary financial planner who guides both full-service clients and those who prefer to DIY, I need to know what is out there in the investing universe.
And for me, one of the best ways to learn is in person.
On Saturday, I attended a wealth management conference, and the exhibit floor was full of products.
Some that caught my eye:
☑️ Covered call ETFs from a Big 6 bank
☑️ Income streams from Canadian student housing
☑️ Double-leveraged single-ticker funds, including SpaceX and Palantir
☑️ Triple-leveraged bets on Canadian gold miners and US-based semiconductor companies
There was even a new AI fund co-founded by Amazon's Jeff Bezos, presented as already worth $41B!
If you have never heard of these, there is a very small chance you are missing out.
But that depends on where you are already investing.
Many Canadians with a diversified portfolio in their RRSP, TFSA and non-registered accounts may already hold some of the same exposure (just packaged differently).
And leverage works in both directions.
If the underlying stock falls 33% in a single day, a triple-leveraged fund on it can be close to wiped out.
Do you know what's in your portfolio and their roles in it?
If you already own real estate in addition to your primary residence, do you really need more rentals?
Or maybe you're an experienced real estate investor, who's had enough of being the landlord and looking for an alternative?
These questions deserve answers, and a financial planner can help you find them.
For most people, double-digit returns every year are only a means to an end.
What they actually want is to reach their goals on time or ahead of schedule, without taking unnecessary risks.
And to have access to their money when life calls for it.
More often than not, it's the plan that's next on the shopping list, not another exciting investment product.
#CrimsonFinancial
#CrimsonCarePlan
#CertifiedFinancialPlanner
#FinancialPlanning
#WealthManagement
#InvestmentManagement
Since the start of January, I have been going to the gym three mornings a week, right after I wake up.
Most days, I am awake and ready before my feet hit the floor.
Yesterday was tougher.
Then, mid workout and after a trip to the water fountain, I saw a quote on the wall that got me through my last two sets.
(Ignore the misspelling of the author though. Should I tell the manager it should read Liane Cordes?)
I've been working out consistently to strengthen my muscles and bones, and I am building Crimson Financial the same way, brick by brick.
Canadians can build their financial houses with that same patience so they stand the test of time.
That usually means a few seasons of work:
☑️Build a foundation of steady cash flow and automated investing
☑️Declutter or consolidate old accounts, insurance, and debt that no longer fit
☑️Reorganize the plan as careers, kids and health change
☑️Pass it on to the next generation, eventually
And you don't need a winning Lotto Max ticket, a FanDuel 8-leg parlay or an AI agent daytrading for you.
Consistent investing, proper risk management, a diversified lower-fee portfolio, and time do the heavy lifting.
Just like at my gym, some people learn from a trainer after a handful of sessions and then carry on with confidence.
Others need that ongoing guidance to keep their form right and stay on track for decades.
Both are fine, as long as you know which one you are.
If you want that ongoing guidance with your finances, please reach out to learn more about how Crimson Financial can help you build a house that lasts.
#CrimsonFinancial
#CrimsonCarePlan
#CertifiedFinancialPlanner
#FinancialPlanning
#WealthManagement
#FinancialFreedom