SellTower CEO | Telecom infrastructure & spectrum valuation, M&A, tower due diligence | 25+ years
Army veteran • Christian • Family man • MBA Professor & Author
I’m Thomas Dolislager.
I’ve spent decades in business, telecommunications, emerging technology, and complex transactions.
I’m also a Christian who believes faith should stand up to serious questions—and that truth matters more than political or cultural tribes.
Here I write about faith, culture, economics, technology, leadership, and current events through that lens.
No slogans for the sake of slogans. No changing the facts to protect a preferred conclusion.
Just an honest worldview.
All Veterans the only way to get this noticed is to make it go viral to where Elon will see it. I am a small account, we need the big accounts to share
@elonmusk@X@XDevelopers@x please look into putting an option for a Active Duty/Veteran checkmark to verify those who served.
Proud to have served, and looking to connect with fellow veterans—follow along🫡
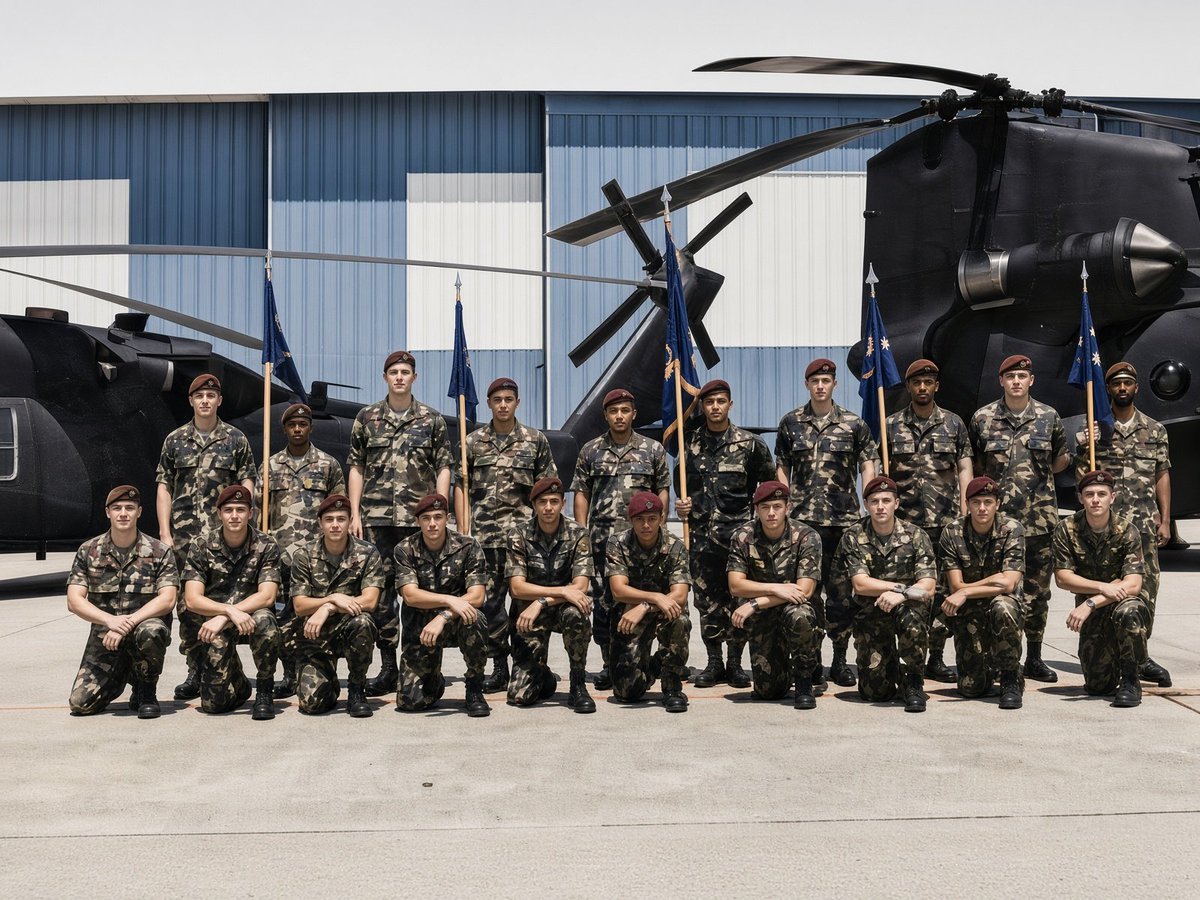
Army ROTC at Wheaton College led to active duty with the 160th SOAR(A) (1991-1995), then the Army Reserves.
The 160th Nightstalkers were all about precision aviation, high-stakes missions, and people I'd trust with my life. N.S.D.Q.
#VeteransUnite #ArmyVeteran #Nightstalkers #160thSOAR
Proud to have served.
Army ROTC at Wheaton College led to active duty with the 160th SOAR(A) (1991-1995), then the Army Reserves.
The 160th Nightstalkers were all about precision aviation, high-stakes missions, and people I'd trust with my life. N.S.D.Q.
Looking to connect with fellow veterans—follow along.
#VeteransUnite #ArmyVeteran #Nightstalkers #160thSOAR
Hi again, Senator Whitehouse.
You have opinions. But I have come with facts.
Wanna go another round with me? 🥊
Let's do a little thought experiment and think outside the box. This may require crayons, so I brought the 24-pack box with me. 🖍️
Here we go:
First, a 24% increase in home insurance costs over three years is not evidence that extreme weather has become more frequent or intense.
Insurance premiums are influenced by numerous factors, including construction and replacement costs, property values, reinsurance expenses, changes in insured exposure and, yes, the expected risk of weather-related losses.
But you cannot point to an increase in premiums and attribute it to man-made climate change without first separating these factors.
I want you to take a close look at the two side-by-side photographs of Miami Beach, Florida shown below in the first image I attached.
🛩️ Left photo: Miami Beach near 63rd Street in 1925, taken from an airplane.
🛰️ Right photo: Approximately the same shot from Google Earth's 3D satellite imagery in 2019.
Expand the images, Sheldon. Go on, look at them very closely. Don't strain your eyes, though. 👀
Do ya notice anything important? Does anything jump out at ya?
It should.
You might notice that there are dozens of 20–40-story high-rise apartments, condos, and resorts along Miami Beach's coastline that were not there during the 1970s or 1980s, much less a century ago when the photograph on the left was taken.
In 1925, the Greater Miami area was largely undeveloped. Today, hundreds of billions of dollars in real estate, infrastructure, and personal property occupy that land.
So, Senator, here's a question for you.
If a category two or three hurricane struck the Miami area today, do you think it would inflict more OR less damage than a hurricane of equal strength striking the same area in 1925?
Well, if you had an IQ approximately higher than an ice cream sandwich (which you apparently don't), you'd know a hurricane striking the Miami area today would cause more damage than one would have in 1925, not because storms are stronger (they're not either way), but because there is a lot more stuff for Mother Nature to destroy.
What's more, depending on the track, hurricane size (and by extension, the magnitude of storm surge), a category one or two could easily inflict more nominal damage today than a category five would have caused hitting the same area a century or more ago.
And this situation isn't unique to Miami Beach.
Urban sprawl and population growth over the last few decades have transformed many rural and suburban landscapes into major metropolitan areas. As a result, the same weather event can produce substantially greater economic losses today than it would have had it occurred decades ago.
Even in a hypothetical static, non-changing climate counterfactual, this pattern would still emerge.
Since words might be too difficult for your first grade reading level, let's use those crayons to draw you an emoji equation. This may explain it better for your pea-sized brain:
⬆️🏗️🏘️ + 🌪️ = ⬆️🏚️ = ⬆️💰
More development + the same natural hazard = more property damage = greater economic losses.
This isn't magic, Senator. 🪄🎩
It's basic arithmetic.
Now, let's discuss the difference between a natural disaster and extreme weather, because apparently this distinction is lost on a surprisingly large number of people, including you.
A hurricane, as an example, is what you would call a “meteorological phenomenon.” Just like a tornado. Or hailstorm. Or a flood. Drought. Wildfire.
Its maximum sustained winds, barometric pressure, storm surge magnitude are physical measurements of its intensity. We can calculate how those parameters change over time. That's climatology.
But the dollar value of the buildings it destroys is not a climate-related measurement.
Natural disasters are socioeconomic outcomes, not evidence of human-caused, let alone natural climate change.
You have absolutely no clue what you're talking about.
@MinutemanPrep01 Impressive. I am following and adding fellow veteran followers, but it has been one by one by one. I am not clever or funny enough to go viral.
I was active duty Army (1991-1995) in 160th SOAR. N.S.D.Q.
@mitchellvii Maybe. Or maybe that is just what the final numbers look like after a 15% shift. Without a true audit, matching paper to machine totals, we won't know the truth.