HOT ROCKS INVESTMENTS PLC
Launch of New Corporate Website
https://t.co/S9xutIi4R0
"We are pleased to launch a redesigned website as our first step in raising the profile of the Company.”
https://t.co/obYCfShmp9
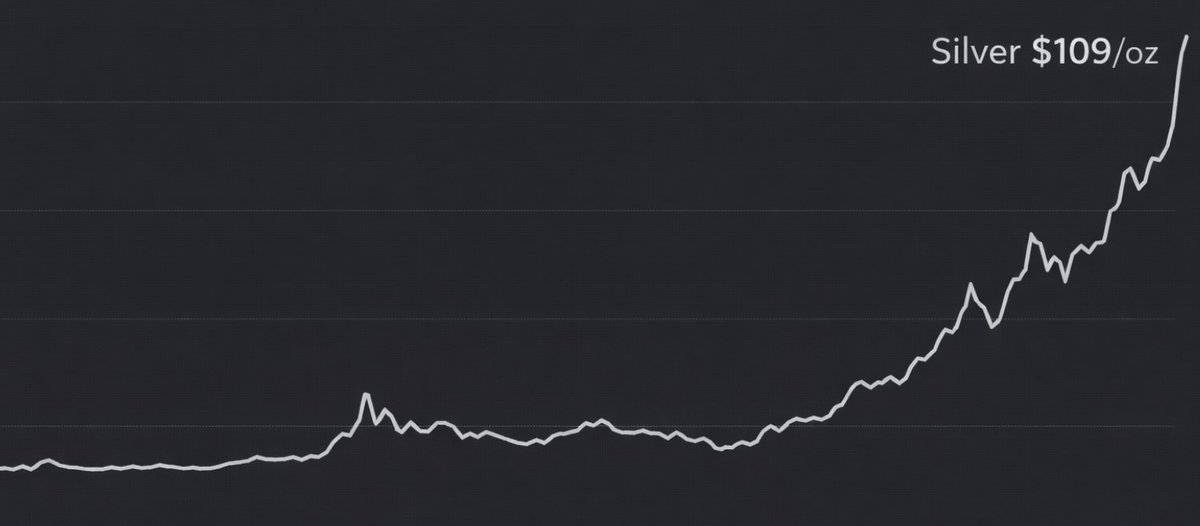
Silver at $109/oz isn’t a side-show to gold.
It sits where three forces meet:
• monetary demand
• industrial demand
• tight supply
When all three pull together, silver rarely moves quietly.
Do you see silver as a monetary metal or an industrial one?
Gold at $5,080/oz.
Silver at $109/oz.
Big numbers get attention.
What matters more is what these prices change:
• project economics
• capital allocation
• jurisdictional behaviour
Price is the messenger.
Structure is the message.
#PreciousMetals#Commodities
COMPANY ANNOUNCEMENT:
IMC Exploration Group Public Limited Company announces the successful renewal of its mining licence to Assat LLC, IMC's 100% owned subsidiary, for the Karaberd Mine, located in Lori Marz province, Republic of Armenia. #gold#mining
https://t.co/6lk0rScj6U
Real investing edge rarely looks exciting in real time.
It looks boring.
It looks slow.
It looks like saying “no” repeatedly.
By the time it looks obvious,
the re-rating has already happened.
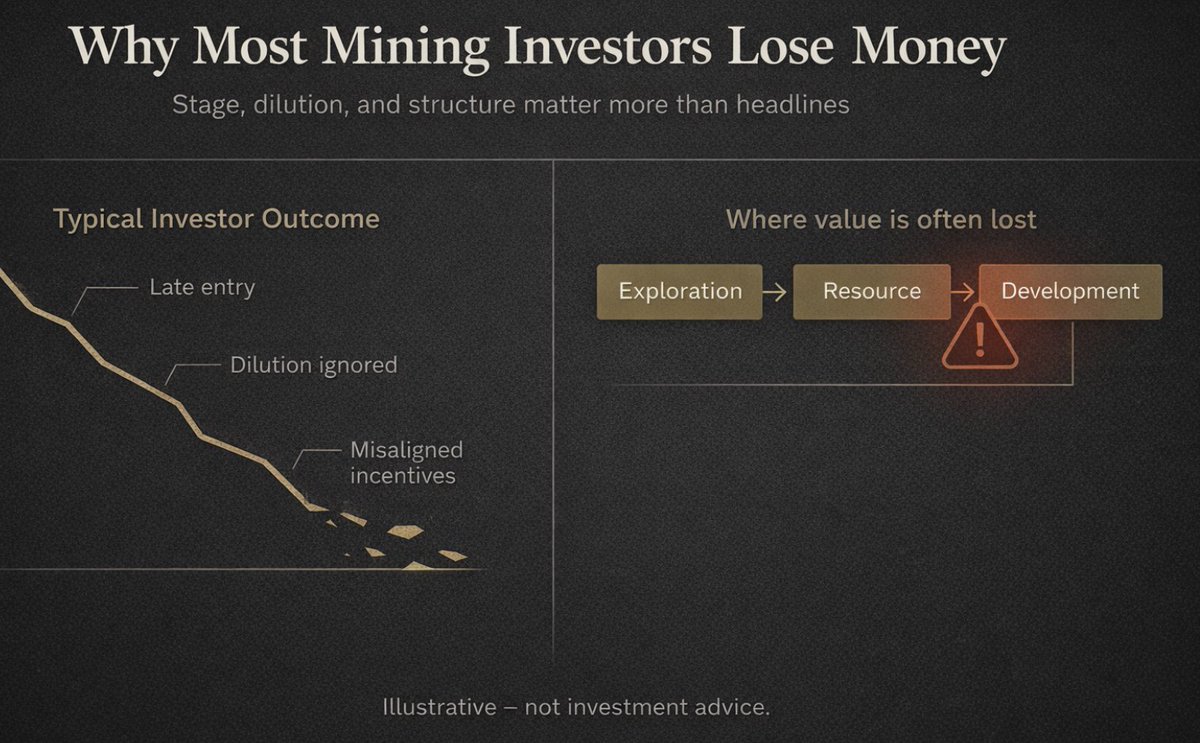
Most mining investors don’t lose money because commodities fall.
They lose money because:
• they enter too late
• they ignore dilution
• they trust incentives that don’t align
Geology matters.
Capital structure matters more.
One reason public markets feel broken:
Too much value creation now happens before listing.
By IPO, risk is lower and upside is too.
Early-stage access matters more than ticker symbols.
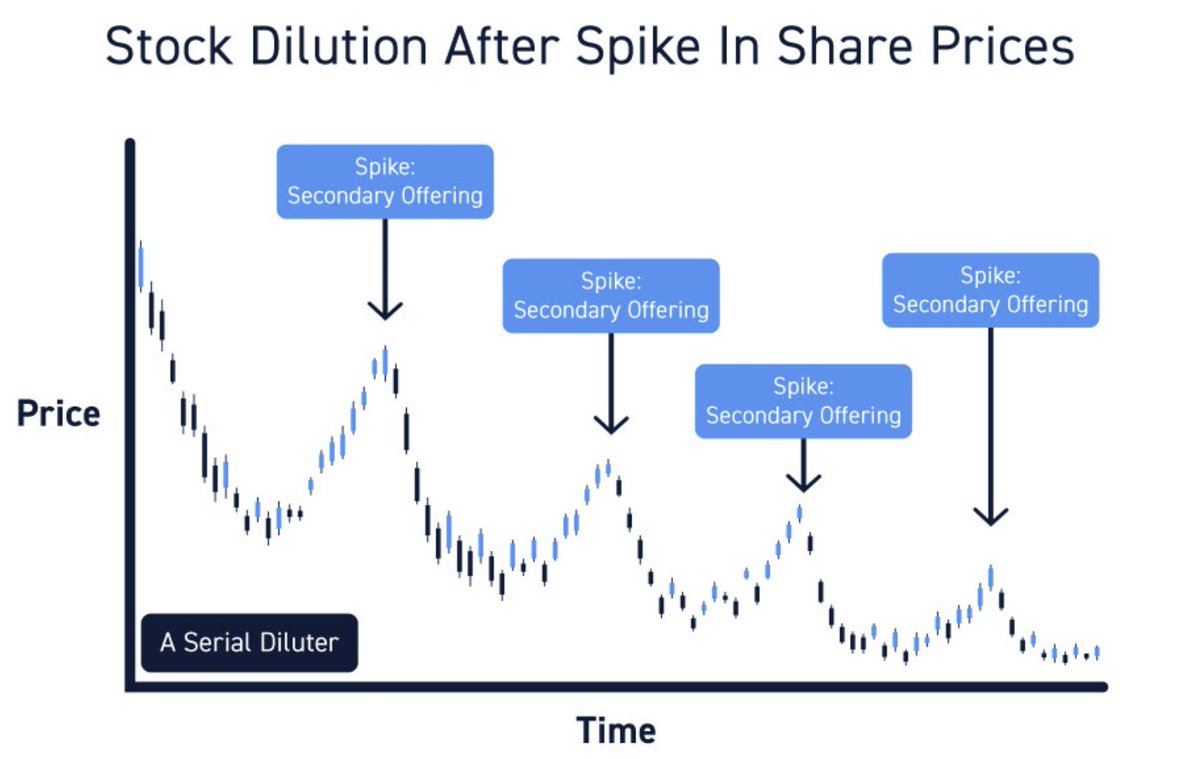
The biggest risk in early-stage investing isn’t geology.
It’s dilution.
Great assets + bad capital structures still destroy value.
Most people don’t model dilution.
They should.
“Africa is risky” is not an investment view.
It’s a lack of one.
Botswana ≠ Ethiopia ≠ Zambia ≠ DRC.
Mining outcomes are driven by jurisdiction + people + structure — not continents.
Gold closing at all-time highs isn’t the story.
The story is how many assets are still priced as if it won’t last.
Re-ratings don’t happen in candles.
They happen as beliefs break.
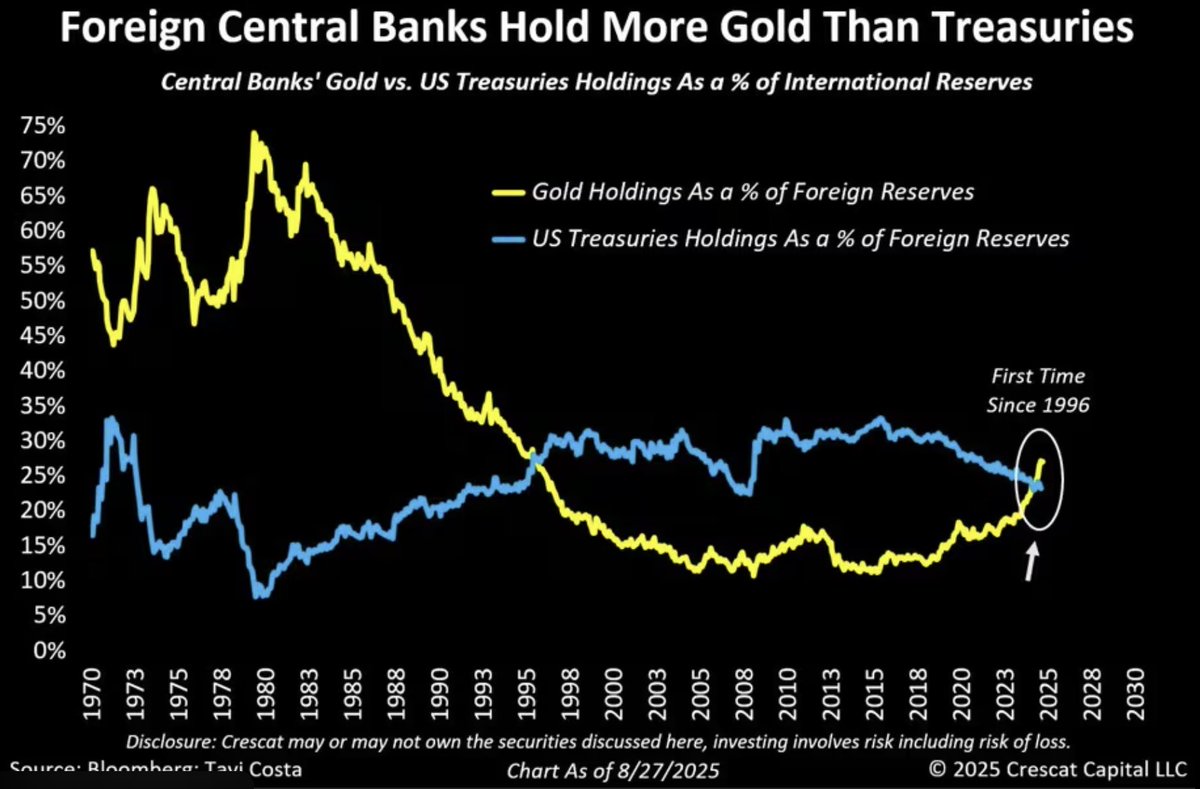
Retail didn’t push gold to all-time highs.
Central banks did.
When the most conservative capital on earth reallocates, it’s not a trade.
It’s a signal.
Gold at ATHs and everyone rushes to producers.
Historically, the biggest % re-ratings happen earlier, when gold changes project economics, not margins.
The market always shows up late to the highest convexity.
The market still prices African gold like gold is $2,500.
Same metal.
Same price.
Deeply different valuations.
That’s not “risk aversion.”
That’s lazy capital allocation.
Gold at all-time highs is being framed as a “safe-haven trade.”
That’s lazy analysis.
This is a confidence crisis trade, in currencies, debt, and political stability.
Safe havens don’t usually make new highs.
Re-pricing does.
When gold hits ATHs, investors rush to producers.
Historically, the largest percentage re-rates occur earlier:
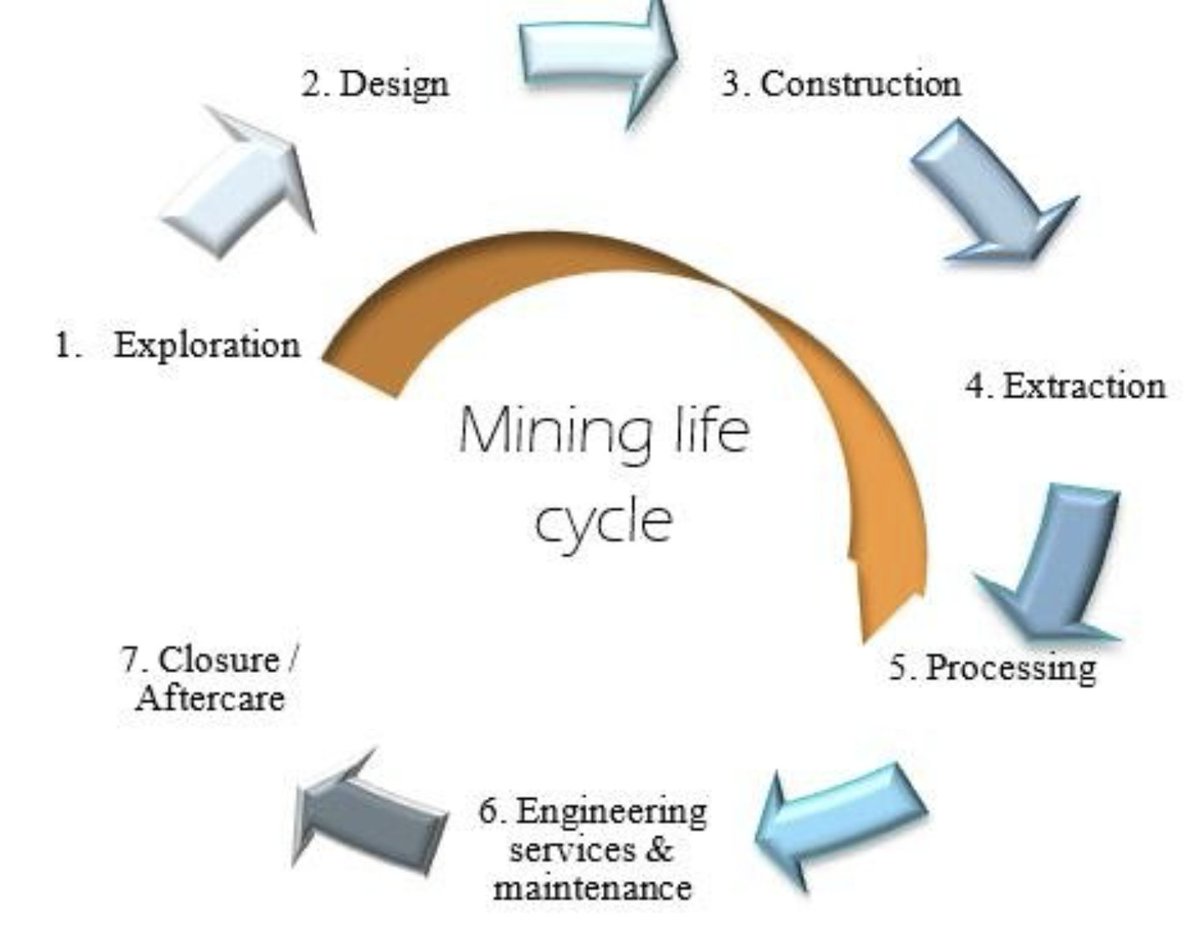
Exploration → Resource definition → Development
Our portfolio is positioned where price changes behaviour, not headlines.
Unpopular take:
Gold at all-time highs doesn’t mean it’s “late.”
It means assumptions were wrong.
Inflation wasn’t transitory.
Confidence wasn’t permanent.
Supply wasn’t infinite.
The repricing is the signal ,not the end.
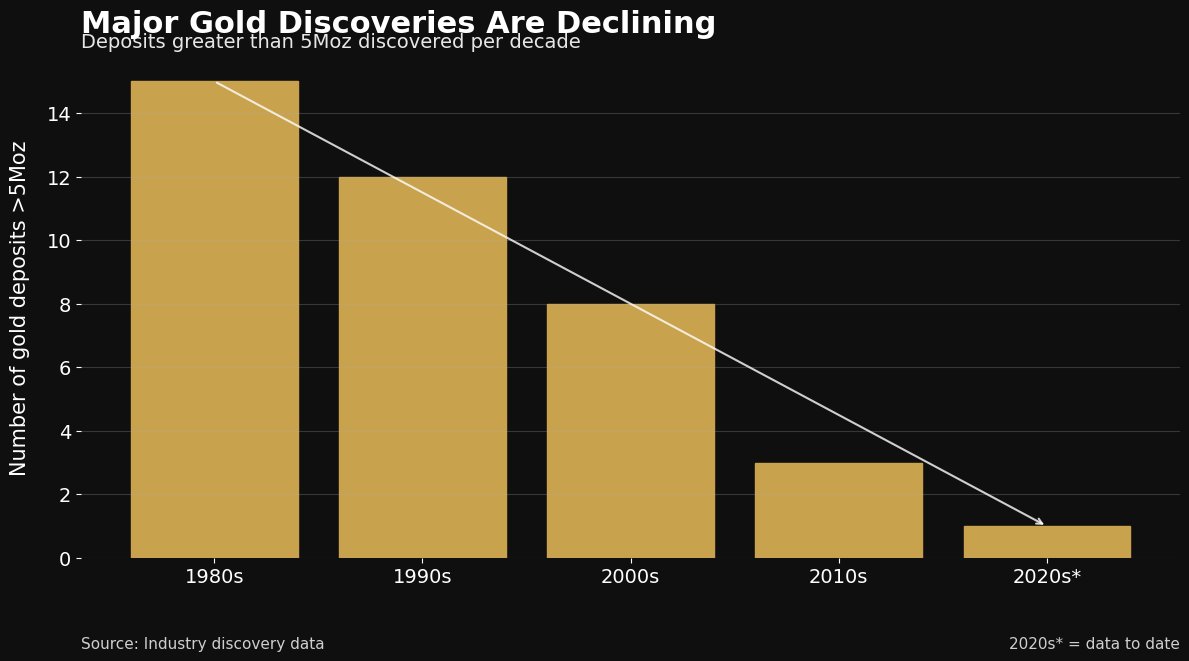
Gold discoveries are getting rarer.
Time to production is getting longer.
Capital intensity is rising.
Yet early-stage valuations haven’t adjusted.
That mismatch doesn’t last forever.
Gold discoveries are getting rarer.
Time to production is getting longer.
Capital intensity is rising.
Yet early-stage valuations haven’t adjusted.
That mismatch doesn’t last forever.
Gold doesn’t sleep.
$4,600/oz on a weekend.
Most junior gold equities are priced like gold is $2,000.
That disconnect is where early-stage capital gets paid.
What’s the market still missing?