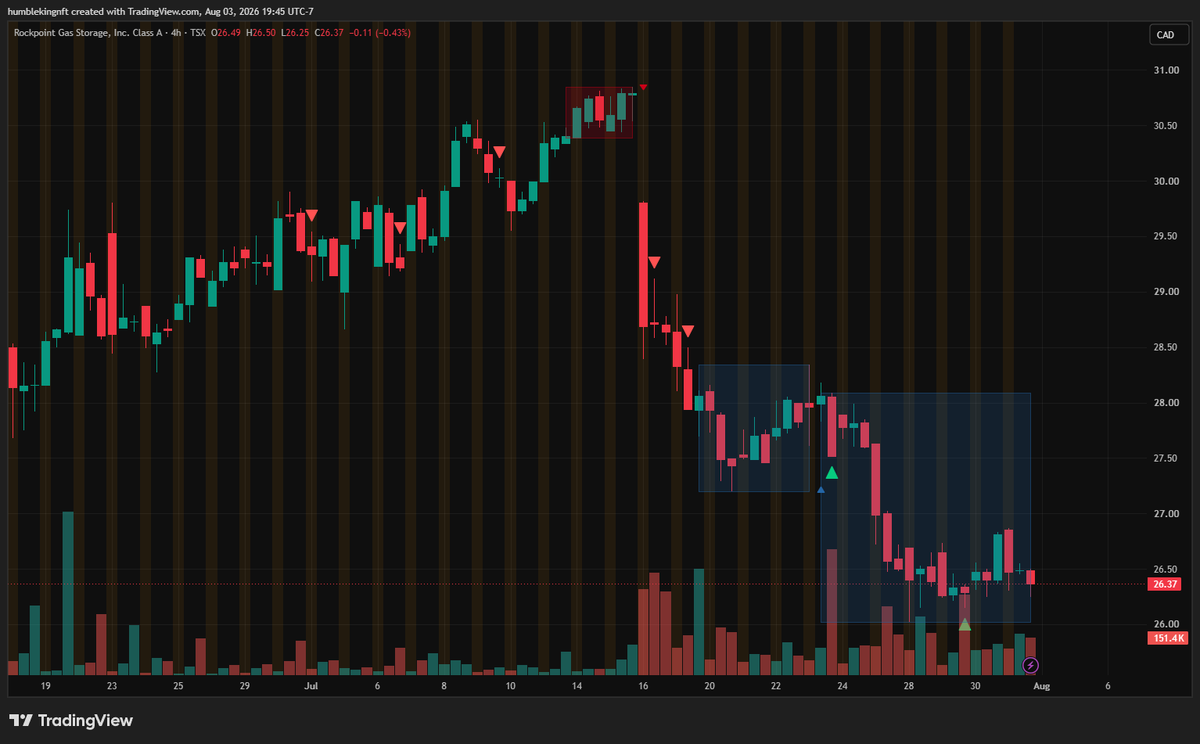
$RGSI.TO sitting at $26.37 right on that July support level after the pullback from $31~. Thinking entry now or add after earnings drop this week.
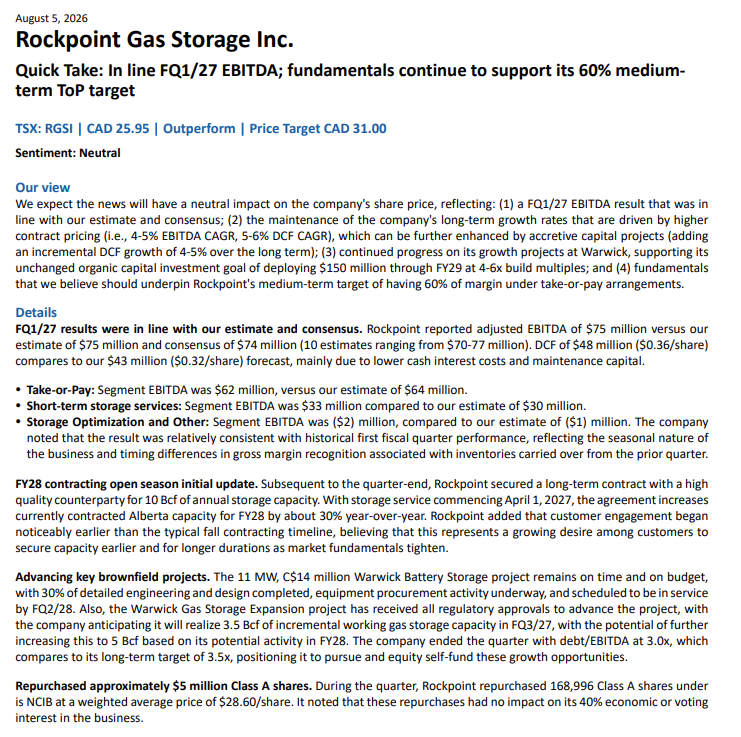
Brookfield-controlled gas storage, ~280 Bcf across Alberta and California. Just put up a record year, revenue up 31%, DCF up to $252M, close to 5% yield here.
@commonsenseplay This stock has been directionally incorrect for so long. I hope you are right and make money. Not for me personally, feels like I would be hoping to get bailed out with this holding.
Took small position in $MTY.TO MTY Food Group yesterday.
Franchise model, 90+ banners, collects royalties and owns few corporate locations - minimal operational risk.
TTM FCF ~$116M vs $834M market cap → 14% FCF yield, ~7x cash flow. Dividend yield ~3.7%, payout ratio only ~20% of cash flow
Potential Buyout angle, but speculative and not confirmed.
Board confirmed a strategic review back in Nov 2025, exploring a possible sale of all or part of the company and still ongoing per the latest earnings call.
Online rumours naming Serruya Private Equity and Recipe Unlimited as bidders, with prices climbing from $52 up to $60/share
Risk: casual dining/QSR industry is facing real headwinds right now — soft consumer spending, negative same-store sales, US segment especially weak. This is a sector problem, not just an MTY problem, and it could persist for a while.
Cheap free cash flow machine with a free option on a sale. +100M FCF/year to service debt/buyback shares/growth puts a floor on this in my opinion
What happens when a power fleet that runs 25% of the time starts getting contracted at 90%? We're about to find out with $TA $TAC
The market still sees TransAlta as a cyclical Alberta merchant generator, and honestly, 2025 gave it every reason to. Prices were soft, volatility died, and the gas fleet mostly sat there.
But in the last 7 months they've signed three deals that quietly change what this company is.
They tolled 700 MW at Centralia to Puget Sound Energy through 2044. They bought 318 MW of Colorado peakers contracted for 25+ years. And the big one: an MOU with CPP and Brookfield for a data centre at Keephills, starting at 230 MW and scaling to a full gigawatt, with TA as the exclusive power provider.
Here's the part people miss on Keephills. Alberta only opened up 1,200 MW of grid capacity for data centres. Dozens of projects wanted in. Two got picked. One is reportedly Meta's. The other is TransAlta's.
The whole trade lives in that fleet math. Idle merchant capacity earns almost nothing in a flat market. Contract it to a data centre running around the clock and it earns fixed margin every hour of the year. The full Keephills gigawatt, call it $300M+ of EBITDA, mostly from steel they already own.
Stack everything announced and EBITDA could go from ~$1B today to $1.6B+ as it ramps into the early 2030s, most of it under 15-25 year contracts. Put a contracted-infrastructure multiple on that instead of a merchant one and I'm looking to $40.
The risk is simple: the MOU has to become signed PPAs, and Alberta could stay oversupplied for a while. But two of the three deals are already inked, the base business prints cash at today's prices, and the dividend just went up.
Merchant price, infrastructure future. Long. Not advice.
Started a position in $TPZ.TO today.
Topaz is a Canadian royalty company — they own land rights across 9M acres in the WCSB, operators like Tourmaline drill on it, and Topaz collects a cut of every barrel and mcf. No capex, no operational risk. ~80% FCF margins.
Tourmaline has 15-20yr LNG export contracts to fulfill. They're drilling regardless of where gas prices sit on any given day.
65% of the acreage is still undeveloped so the growth runway is long. Management guides 8-10% production growth annually through 2031 — all funded by operators, not Topaz.
Dividend has grown 11% a year since IPO and stays covered even at $0 AECO.
Canadian LNG exports are ramping hard through 2030 which could close the AECO basis discount.
Entering around $30. Not a deep value play but a fair price for something that compounds quietly in the background. Adding on dips.
@3liXBT@intodotspace I think this is a winner, market sleeping on it. The UX design and Leveraged markets are very appealing. Their marketing videos also next level, probably the one category to bet on in these market conditions.
@VanIsleInvestor Seems like the prudent thing to do. Prefer $BCE over $T but will review/consider buy position if Telus cuts dividend. $HR.UN and $REI.UN became much more attractive investments imo after they cut dividend during covid. 50-60%~ payout ratio is comfortable
@cabenX My view coming from Tradfi, if you ignore the token price (whole market down). The dividends/airdrops for holding +5k skaito have been very generous given the amount of time.