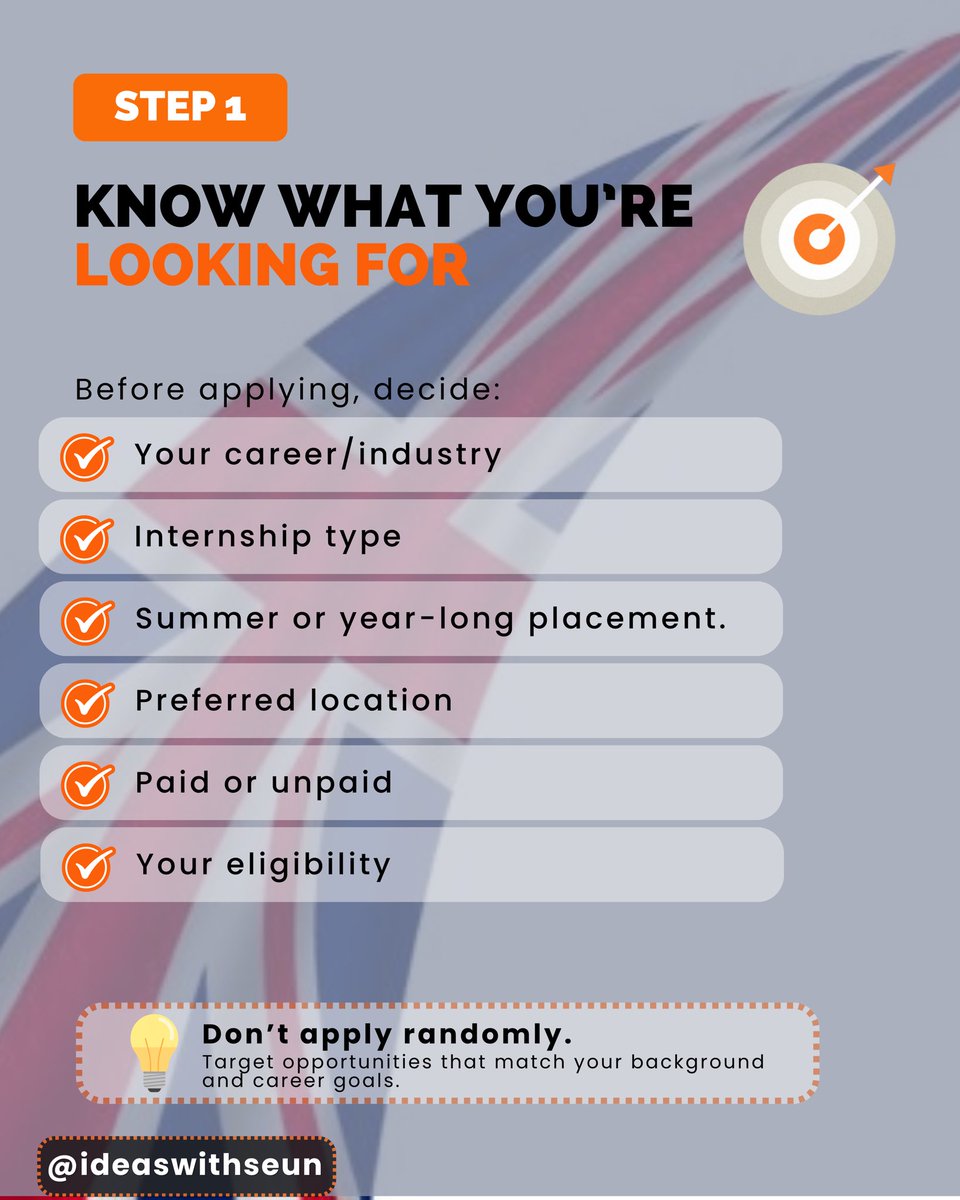
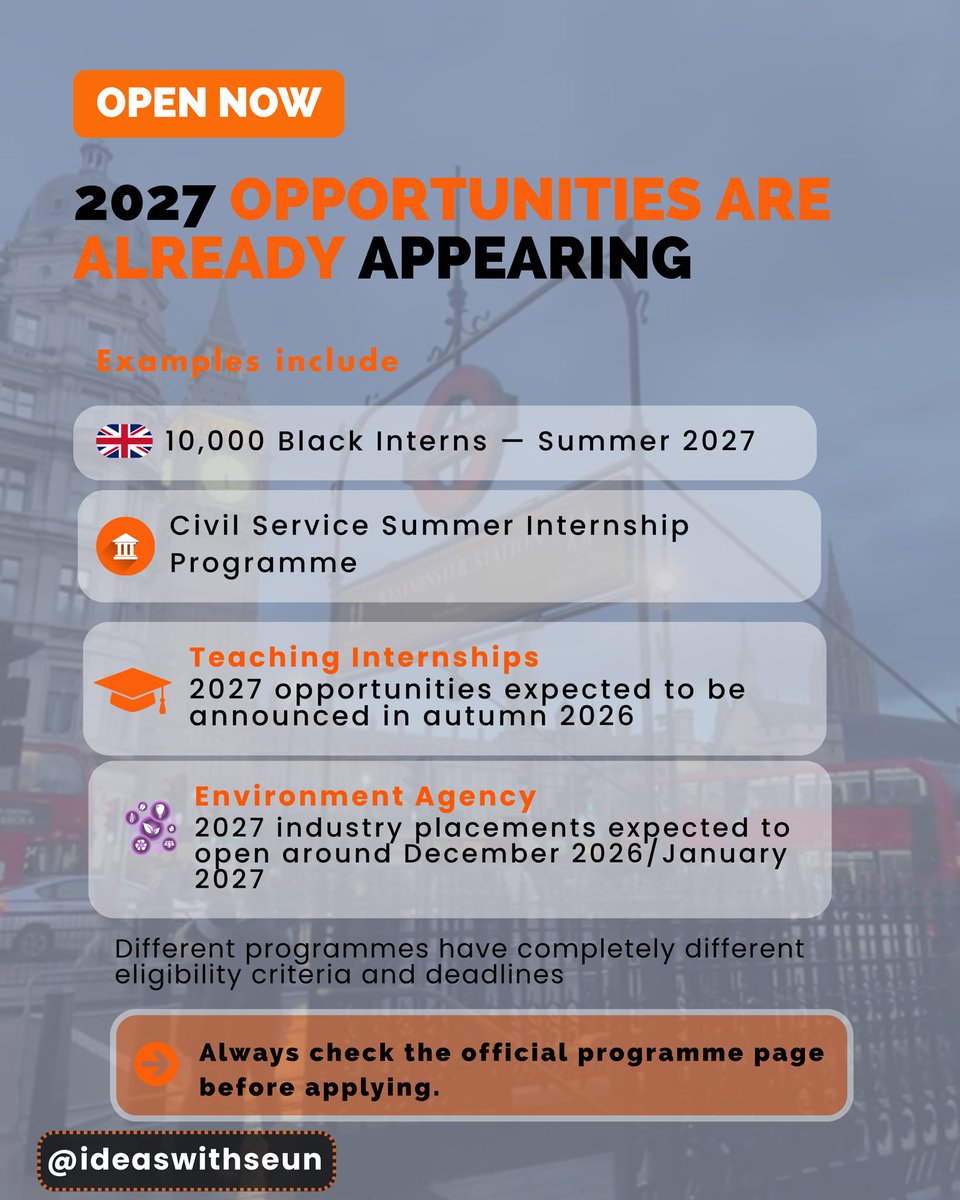
UK 2027 INTERNSHIPS ARE STARTING TO OPEN! 🇬🇧🎓
If you’re a student, recent graduate or someone looking to gain UK work experience, NOW is the time to start preparing.
Some 2027 programmes are already accepting applications, while others will open later in 2026 or in early 2027.
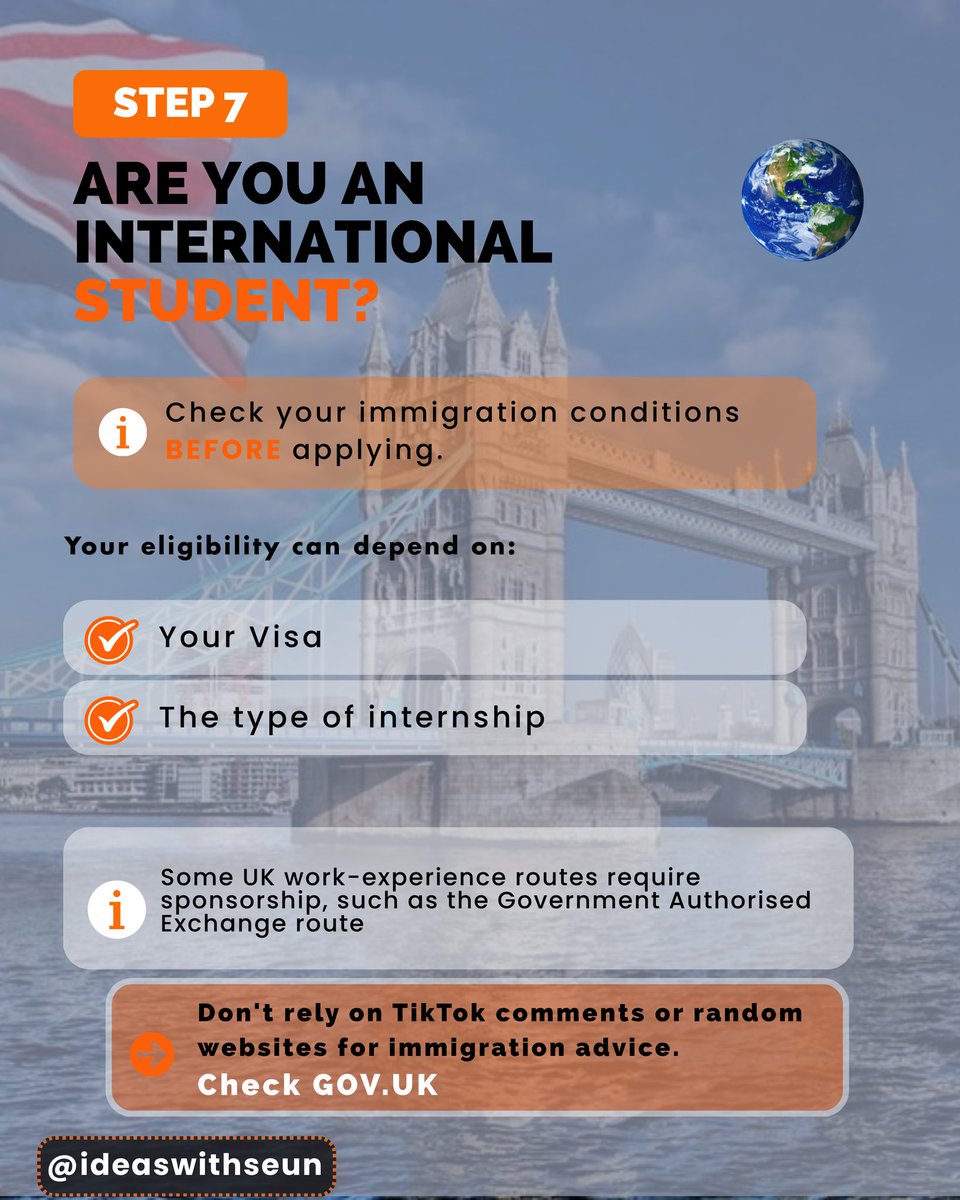
Always verify the details directly with the employer or official programme website.
https://t.co/XdY8Kjk4iM also provides guidance on internships, employment rights and right-to-work requirements.
Moving abroad can be a fresh start.
But don't carry old financial obligations into your new chapter without
understanding them.
Know what you owe. Know your rights. Know your options.
Your future wealth deserves a clean plan.
This doesn't mean your investments will automatically be taken because you have a debt.
The circumstances matter, including the type of debt, creditor, account structure, GSI mandate and applicable recovery process.
And most importantly:
Get documentation.
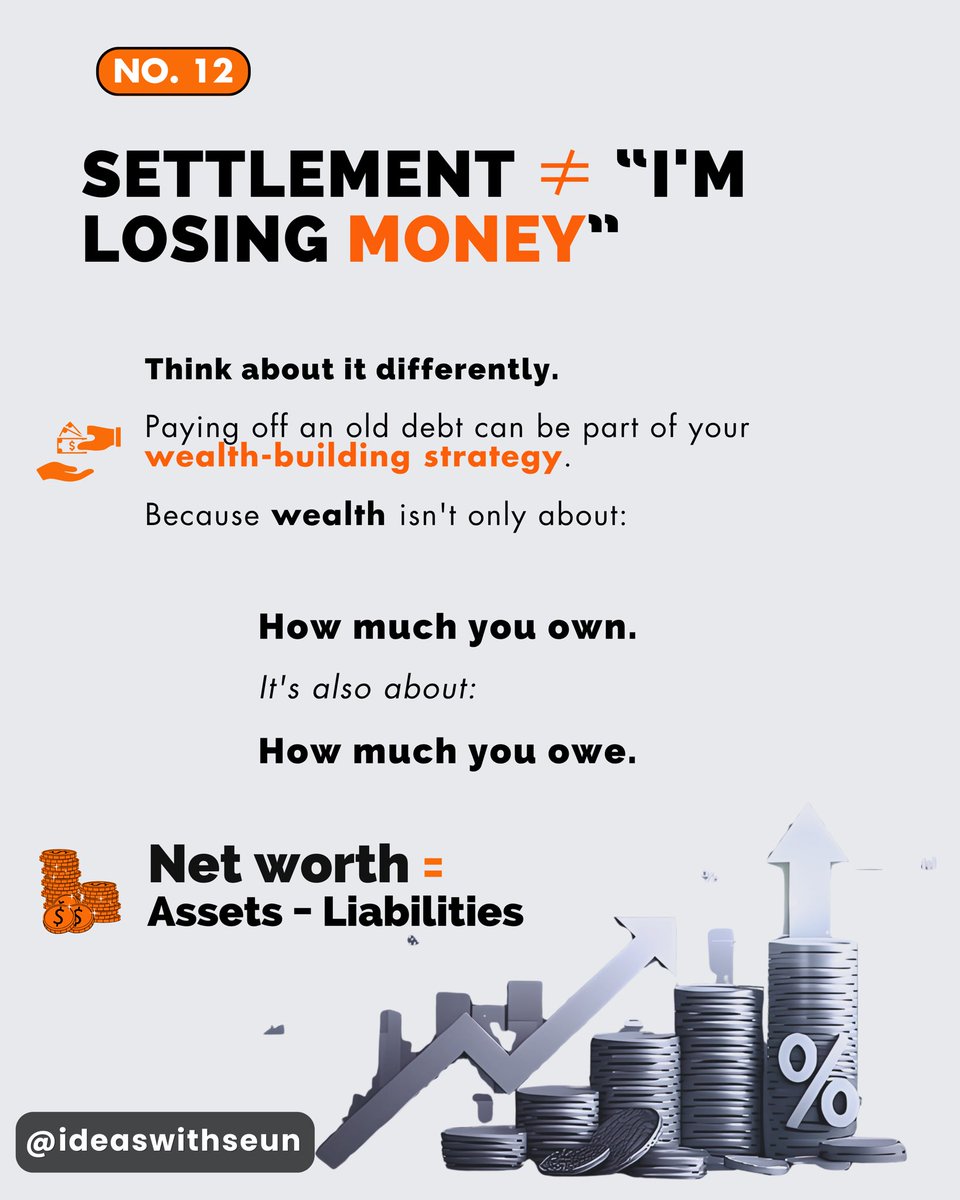
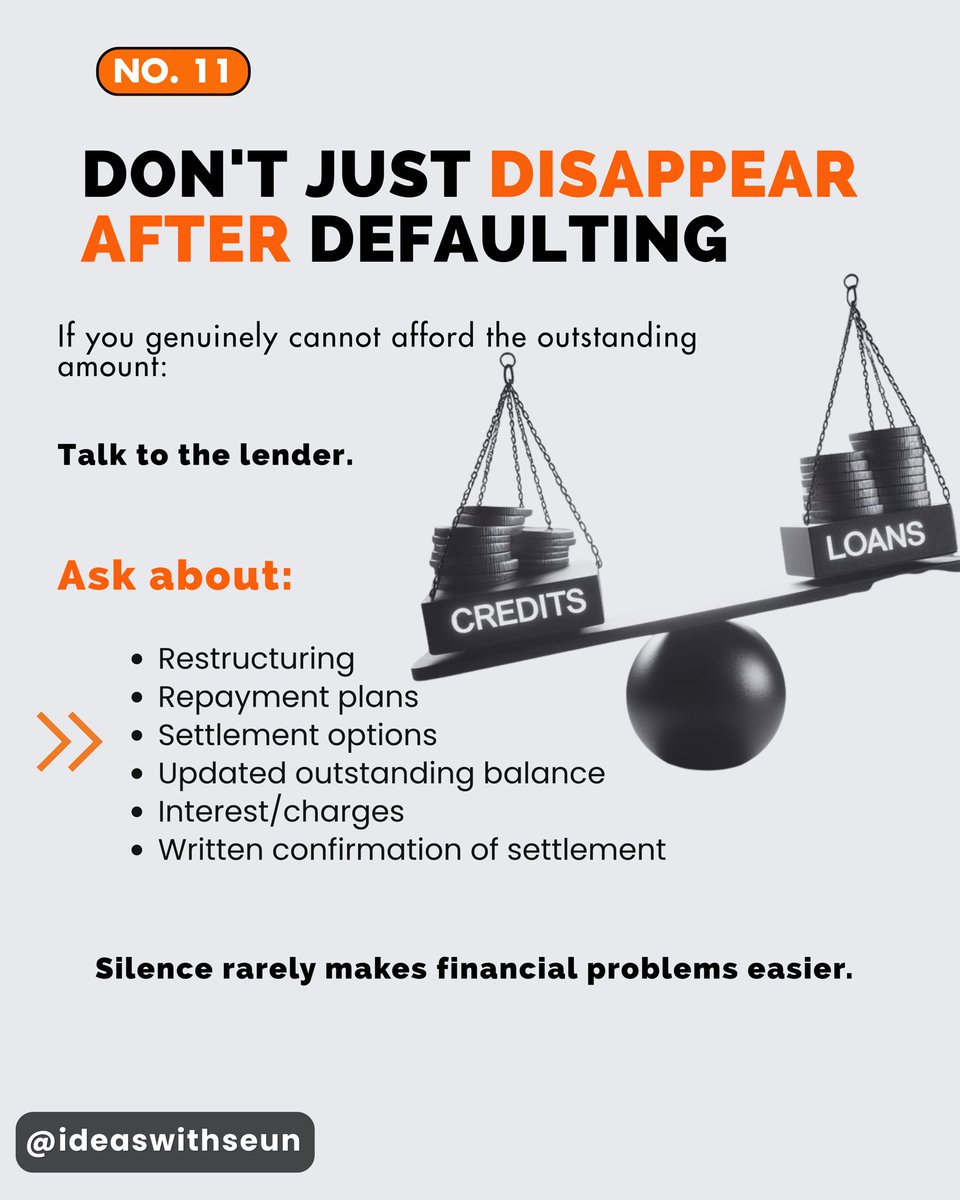
If you settle or restructure the debt, keep evidence of the arrangement and obtain the appropriate confirmation from the lender.
Eligible account types under the GSI framework can include:
• Savings accounts • Current accounts • Domiciliary accounts • Investment/deposit accounts • Electronic wallets
So don't assume moving abroad makes your Nigerian accounts irrelevant.
Your Nigerian financial footprint can still matter.
The CBN's Global Standing Instruction (GSI) framework provides a mechanism for recovery of qualifying past-due obligations from eligible accounts held with participating financial institutions.
You may no longer live in Nigeria, but relocation doesn't automatically cancel a financial obligation.
If you borrowed from a Nigerian financial institution, the debt generally remains until it is settled, restructured or otherwise resolved.
You got the visa, moved abroad and started earning in pounds, dollars or euros.
But that loan you left in Nigeria?
It didn't disappear.
Here’s what you should know before building wealth abroad. 👇
So, when the next iPhone drops
Are you choosing the phone or the investment?
Follow @ideaswithseun for more ideas
Illustrative example only. Investment returns aren’t guaranteed, & an 8% annual return is an assumption, not a forecast. Always do your own research b4 investing.
THE £1,300 MISTAKE YOU’RE ABOUT TO MAKE
The next iPhone is coming.
And if you’re thinking about dropping £1,300+ on the latest Pro Max, pause for a second.
Because the real question isn’t:
“Can I afford the phone?”
And here’s the important part:
If the device directly helps you generate income-content creation, client work, business operations. it can be a productive tool.
But if you’re upgrading mainly for better scrolling, clearer photos & bragging rights.
You might want to think twice