SoSoValue Flash: Fed Officials Warn AI Capex Drives Inflation, Global Bond Sell-off Intensifies, Microsoft Jumps 3.7% on Copilot Upgrade
💥 Core Catalyst:
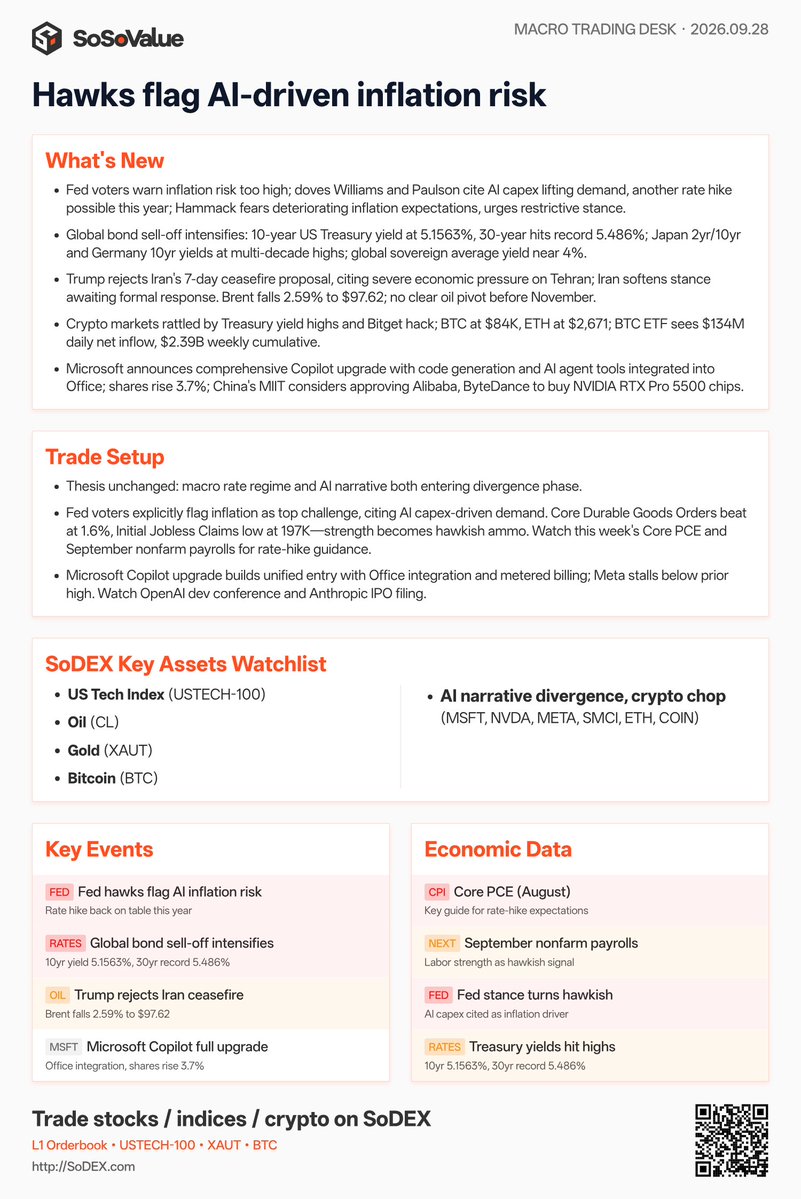
In Macro & Rates, hawkish signals escalated across the Federal Reserve as dovish voters Williams and Paulson noted that robust AI capex is elevating total demand, keeping a 2026 rate hike on the table. Solid economic data (Core Durable Goods Orders +1.6% MoM, Initial Jobless Claims at 197K) fueled hawkish narrative momentum. The global bond sell-off accelerated, pushing the 10-year US Treasury yield to 5.1563% and the 30-year yield to a record 5.486%, while Japanese and German benchmark yields hit multi-decade highs.
In Geopolitics & Tech, President Trump rejected Iran's 7-day ceasefire proposal, pointing to economic strains on Tehran, pulling Brent crude down 2.59% to $97.62/bbl. China's MIIT is reportedly reviewing applications from Alibaba and ByteDance to acquire NVIDIA RTX Pro 5500 GPUs. In enterprise software, Microsoft announced a major Copilot overhaul, integrating code generation and autonomous AI agent tools across Office with metered pricing, driving MSFT stock up 3.7%.
In Crypto, elevated Treasury yields and a security exploit at Bitget weighed on market momentum, leaving BTC at $84K and ETH at $2,671. However, structural institutional demand remained intact, with BTC ETFs logging $134M in daily net inflows ($2.39B weekly cumulative).
🔍 Key Logic Shifts:
1️⃣ "AI Demand = Persistent Inflation" Framework Drives Global Yield Spikes: Fed policymakers re-framed record AI capex as an aggregate demand catalyst, prompting markets to reprice rate hike risks and pushing 30-year Treasuries to record highs.
2️⃣ Trump Rejection of Short Ceasefire Flattens Crude Premium: Oil dropped to $97.62/bbl as diplomatic posturing reduced near-term supply disruption fears.
3️⃣ Enterprise AI ROI Advances as Crypto Absorbs Macro Yield Drag: Microsoft's Copilot upgrade sets a clear commercial monetization benchmark, while crypto markets demonstrated underlying resilience through strong weekly ETF accumulation despite macro headwind pressures.
📊 SoDEX Key Assets Watchlist:
Core: $USTECH-100 · $CL · ethereum:0x68749665ff8d2d112fa859aa293f07a622782f38 · $BTC
AI ROI & Crypto Macro Divergence: $MSFT · $NVDA · $META · $SMCI · $ETH · $COIN
YneraX One Early User Giveaway
The YneraX One Early User Campaign is live, featuring a total reward pool of $150,000 USDT and 4,000,000 $YNX tokens.
Reward allocation
$50,000 USDT for the top 2,000 leaderboard participants.
$100,000 USDT distributed to 20,000 randomly selected winners.
4,000,000 $YNX allocated across leaderboard rewards, community rewards, and special bonuses.
How to participate
Sign in with X, complete tasks, and invite friends to earn more entries. Your entries determine your leaderboard rank.
Participate: https://t.co/6BuLomn8oZ
Full details and rules: https://t.co/bGWmzFww3M
Campaign closes: October 15, 2026, at 14:44 UTC.
SoSoValue Flash: CFTC/SEC Exemptions Spark Crypto Rally to $81K, BOJ Raises Rates to 31-Year High, Iran Proposes Ceasefire Terms
💥 Core Catalyst:
In Crypto & Regulation, parallel innovation exemptions issued by the CFTC and SEC provided a major structural catalyst, sparking a broad DeFi rally. BTC reclaimed $81K, ETH rose to $2,650, CME futures basis ticked up to 0.12%, and spot BTC ETFs recorded $433M in daily net inflows.
In Geopolitics & Macro, regional tensions showed diplomatic movement: while Houthis struck targets in Saudi Arabia, Iran submitted 7 ceasefire conditions via Qatari mediators. President Trump labeled the moment a "decision phase," pulling Brent crude down 1.08% to $98.85/bbl. Meanwhile, the Bank of Japan hiked rates by 25bps to 1.25% (a 31-year high), with Governor Ueda keeping the door open for further hikes. The BOJ move alongside lingering geopolitical friction pushed the 10-year US Treasury yield toward 5%, sustaining valuation pressure across equities. Additionally, US-China officials met in New York on AI, tariffs, and critical minerals ahead of the September 24 summit, while Sam Altman is scheduled to brief the UN Security Council on AI safety next week.
In Tech & AI, market consensus firmly re-anchored on AI safety rules acting as a hardware demand accelerator rather than an R&D speed bump. Requirements for rigorous AI alignment directly fueled a continued bounce across semiconductor equities.
🔍 Key Logic Shifts:
1️⃣ Regulatory Relief Unlocks Institutional Inflows for Digital Assets: CFTC/SEC innovation exemptions removed developer friction, driving a resurgence in DeFi and strong spot ETF accumulation ($433M).
2️⃣ BOJ Tightening Meets Easing Crude Premiums: A 31-year high in Japanese interest rates reinforces tight global monetary conditions, but Iran's ceasefire proposal eased energy supply fears, dragging Brent below $99/bbl.
3️⃣ AI Alignment Consensus Directly Benefits Semi Hardware: Re-framing regulatory safety testing as a compute-intensive process continues to convert policy updates into a structural tailwind for semiconductor hardware.
📊 SoDEX Key Assets Watchlist:
Core: $USTECH-100 · $CL · ethereum:0x68749665ff8d2d112fa859aa293f07a622782f38 · $BTC
DeFi Exemptions & AI Compute: $ETH · $UNI · $CRCL · $COIN · $NVDA · $AMD
SoSoValue Flash: Brent Nears $110 & 10Y Yield Tops 5% in Macro Drag, Trump Backs AI Amid Sector Rotation, Senate Advances CLARITY Act
💥 Core Catalyst:
In Geopolitics & Macro, Houthi strikes on a Saudi airbase pushed Brent crude near $110/bbl before easing slightly on Trump's comments that Russia and Ukraine agreed to refrain from targeting energy facilities. Geopolitical risk and persistent inflation fears drove the 10-year US Treasury yield past 5%, establishing a severe valuation drag across risk assets. In Asia, China's August Total Social Financing (CNY 1,661.9B) and new RMB loans (CNY 600B) missed consensus, pointing to muted private credit demand while markets digest potential Q3 monetary easing.
In Tech & Crypto, narrative divergence deepened. Trump doubled down on AI support at the All-In Summit, dismissing safety warnings as political maneuvering while calling Nvidia CEO Jensen Huang live on stage. Nevertheless, mounting Capex-to-ROI mismatch concerns caused semiconductors to pull back, driving fund rotation into big tech platforms (Meta, Google). In regulation, the US Senate released a revised CLARITY Act draft featuring 126 amendments—including a ban on political officials profiting from crypto—facing a tense 60-vote cloture threshold on Tuesday amid bank opposition. Crypto held stable, with BTC at ~$78.1K and ETH at $2,538.
🔍 Key Logic Shifts:
1️⃣ Oil Near $110 & 10Y Yield Beyond 5% Form a Dual Macro Anchor: Geopolitical supply threats and sticky long-end yields present an active headwind for broader equities, overriding temporary diplomatic headlines.
2️⃣ AI Capital Rotates from Hardware Capex to Software Platform ROI: Market focus has pivoted from pure compute expansion to revenue monetization, prompting a tactical shift from semiconductors to platform leaders with strong distribution moats.
3️⃣ Crypto Regulators Approach Key Vote Amid High-Yield Drag: As the Senate prepares for the CLARITY Act cloture vote, regulatory policy friction and 5%+ Treasury yields keep digital assets range-bound.
📊 SoDEX Key Assets Watchlist:
Core: $USTECH-100 · $CL · ethereum:0x68749665ff8d2d112fa859aa293f07a622782f38 · $BTC
AI Divergence & Crypto Regulation: $NVDA · $GOOGL · $META · $COIN · $CRCL · $ETH