📝 𝐔𝐋𝐓𝐈𝐌𝐀𝐓𝐄 𝐓𝐇𝐑𝐄𝐀𝐃 : 𝐀 𝐒𝐭𝐞𝐩-𝐛𝐲-𝐒𝐭𝐞𝐩 𝐆𝐮𝐢𝐝𝐞 𝐭𝐨 𝐑𝐞𝐢𝐦𝐛𝐮𝐫𝐬𝐞𝐦𝐞𝐧𝐭 𝐒𝐮𝐜𝐜𝐞𝐬𝐬
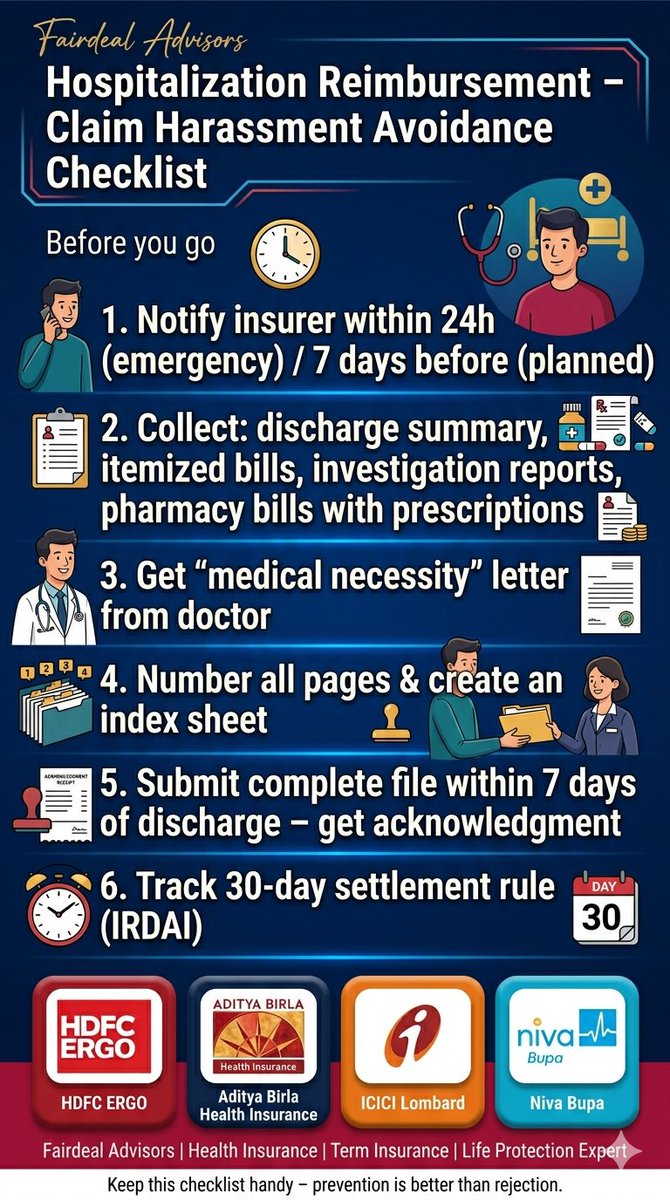
The journey to a successful reimbursement starts the moment you or a family member is admitted. Follow this sequence to avoid missteps:
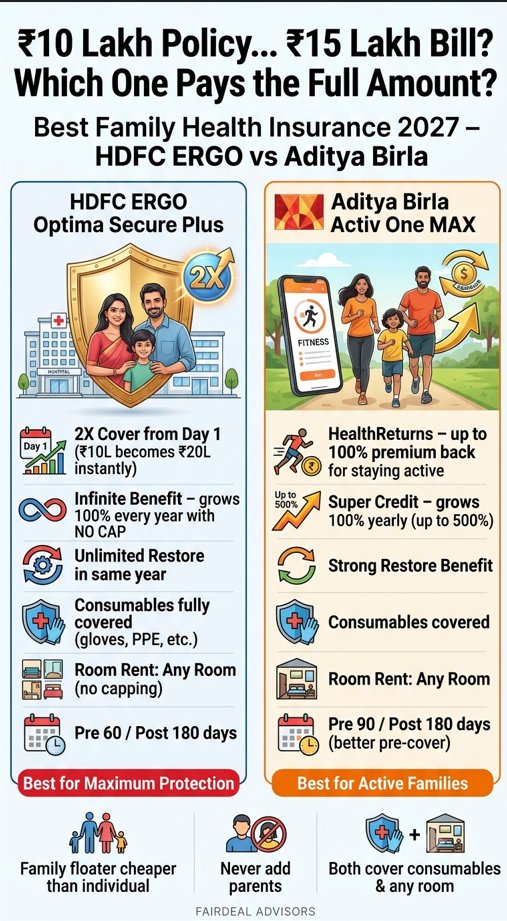
₹𝟏𝟎 𝐋𝐚𝐤𝐡 𝐏𝐨𝐥𝐢𝐜𝐲 𝐛𝐮𝐭 ₹𝟏𝟓 𝐋𝐚𝐤𝐡 𝐁𝐢𝐥𝐥? 𝐎𝐧𝐞 𝐏𝐥𝐚𝐧 𝐏𝐚𝐲𝐬 𝐈𝐭 𝐀𝐥𝐥
@HDFCERGOGIC 𝐄𝐑𝐆𝐎 – 𝐎𝐩𝐭𝐢𝐦𝐚 𝐒𝐞𝐜𝐮𝐫𝐞 𝐏𝐥𝐮𝐬
# 2X Cover from Day 1 → ₹10L base becomes ₹20L instantly
# Infinite Benefit → Grows 100% every year with NO CAP
# Unlimited Restore in the same year
# Consumables fully covered (gloves, PPE, masks etc.)
# Room Rent: Any Room (no capping)
# Pre 60 days | Post 180 days
# Best for: Maximum protection & long-term cover growth
@abhealthin 𝐀𝐝𝐢𝐭𝐲𝐚 𝐁𝐢𝐫𝐥𝐚 – 𝐀𝐜𝐭𝐢𝐯 𝐎𝐧𝐞 𝐌𝐀𝐗
# HealthReturns → Up to 100% premium back for staying active
# Super Credit → Grows 100% yearly (up to 500%)
# Strong Restore Benefit
# Consumables covered
# Room Rent: Any Room (no capping)
# Pre 90 days | Post 180 days (better pre-cover)
# Best for: Active families who want fitness rewards
@policybazaar@Niva_Bupa
#healthinsurance #mediclaim
𝐙𝐞𝐫𝐨 𝐖𝐚𝐢𝐭𝐢𝐧𝐠 𝐏𝐞𝐫𝐢𝐨𝐝 𝐢𝐬 𝐡𝐞𝐫𝐞.
@ManipalCigna Sarvah Param covers your PEDs from Day 1. No more 3-year wait.
Here is the exact cheat sheet for ManipalCigna's Sarvah series broken down into 3 distinct plans, unique features, and riders.
1️⃣ 𝐒𝐚𝐫𝐯𝐚𝐡 𝐏𝐫𝐚𝐭𝐡𝐚𝐦 (The Budget & Critical Shield)
Best for: Young individuals or as a high-severity top-up policy.
𝐂𝐨𝐫𝐞 𝐅𝐨𝐜𝐮𝐬: Cancer, heart conditions, stroke, major organ transplants, and accidents.
• Up to ₹3 Cr cover for 4 critical problems
• Best as starter or top-up
• Lower premium
.Optional Sarathi (PED from Day 31)
Why buy: Lowest base premium starting at just a few hundred rupees for lower sum insured.
The Catch: Broader standard hospitalisation features are limited or require add-ons.
#insurance #healthinsurance #policybazaar
🚀 𝐆𝐚𝐦𝐞-𝐂𝐡𝐚𝐧𝐠𝐢𝐧𝐠 𝐔𝐧𝐢𝐯𝐞𝐫𝐬𝐚𝐥 𝐏𝐞𝐫𝐤𝐬 & 𝐑𝐢𝐝𝐞𝐫𝐬
Gullak Advantage: 100% base SI added every year (up to 10x–15x) even if you make a claim.
Surplus Benefit: Extra 100% of base SI for your very first claim of the year, starting Day 1.
No Zonal Co-Pay: Treat anywhere in India without location-based penalty deductions.
Top Riders Available: Personal accident (up to ₹3Cr), non-medical expenses (NMME), durable medical equipment (DME), and room rent modifications.
“𝐀𝐚𝐩 𝐊𝐚𝐧𝐩𝐮𝐫 𝐦𝐞𝐢𝐧 𝐛𝐚𝐢𝐭𝐡𝐤𝐚𝐫 𝐆𝐮𝐫𝐠𝐚𝐨𝐧 𝐦𝐞𝐢𝐧 𝐜𝐥𝐚𝐢𝐦 𝐤𝐚𝐢𝐬𝐞 𝐦𝐚𝐧𝐚𝐠𝐞 𝐤𝐚𝐫𝐨𝐠𝐞?”
This is one question almost every new client asks me.
And honestly, I understand their concern.
When a family member is hospitalised, the last thing anyone wants is to run around for insurance approvals, documents and follow-ups.
𝐋𝐞𝐭 𝐦𝐞 𝐬𝐡𝐚𝐫𝐞 𝐚 𝐫𝐞𝐚𝐥 𝐞𝐱𝐩𝐞𝐫𝐢𝐞𝐧𝐜𝐞.
Just a few days ago, a family who trusted me with their
@HDFCERGOGIC
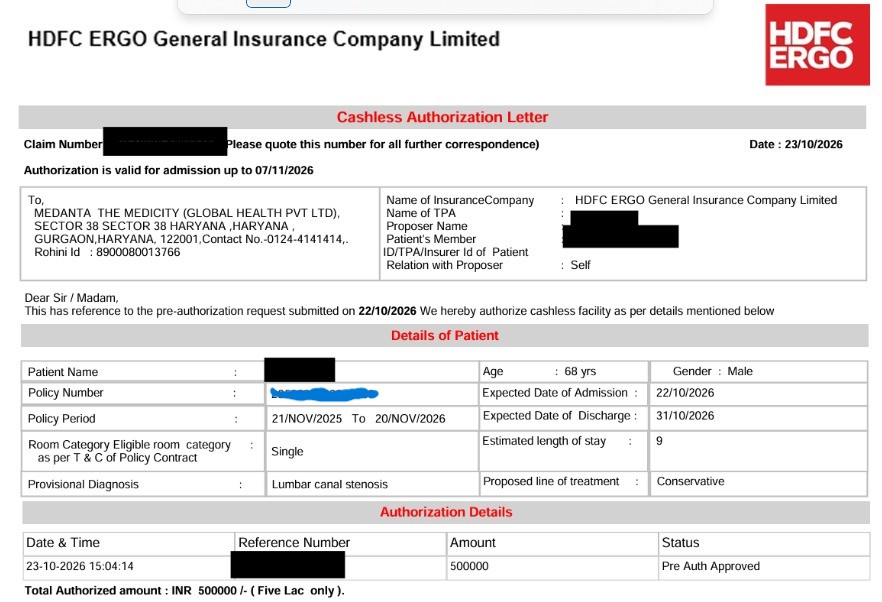
health policy two years ago faced a stressful time. Their 68-year-old father was diagnosed with lumbar canal stenosis and needed urgent hospitalization at Medanta The Medicity, Gurgaon.
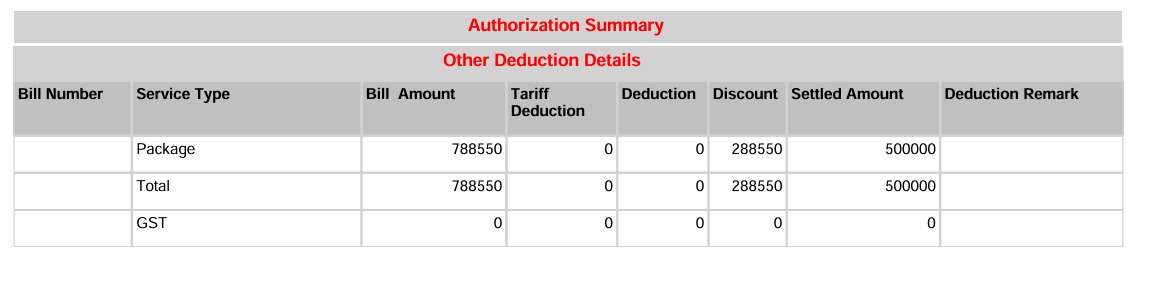
Anxiety was naturally high. But sitting right here in Kanpur, I coordinated the entire process online. Total cashless pre-authorization of ₹5,00,000 for his 9-day treatment plan was smoothly approved!
People often ask me: “𝐀𝐚𝐩 𝐊𝐚𝐧𝐩𝐮𝐫 𝐦𝐞𝐢𝐧 𝐛𝐚𝐢𝐭𝐡𝐞 𝐡𝐮𝐲𝐞 𝐩𝐨𝐨𝐫𝐞 𝐈𝐧𝐝𝐢𝐚 𝐤𝐞 𝐜𝐥𝐚𝐢𝐦𝐬 𝐤𝐚𝐢𝐬𝐞 𝐦𝐚𝐧𝐚𝐠𝐞 𝐤𝐚𝐫𝐞𝐧𝐠𝐞?”
Simple answer: We don’t need to be physically present. Everything happens online. Coordination is 24×7. Most pre-auths get done in a few minutes to a few hours. Sometimes it takes a little longer — I’m not going to lie and say everything is always instantaneous.
When you have the right policy and a dedicated advisor standing behind you, distance vanishes.
But what I can proudly say is : 𝐍𝐨 𝐠𝐞𝐧𝐮𝐢𝐧𝐞 𝐜𝐥𝐚𝐢𝐦 𝐨𝐟 𝐦𝐲 𝐜𝐥𝐢𝐞𝐧𝐭 𝐰𝐢𝐥𝐥 𝐬𝐮𝐟𝐟𝐞𝐫 𝐛𝐞𝐜𝐚𝐮𝐬𝐞 𝐨𝐟 𝐝𝐞𝐥𝐚𝐲 𝐨𝐫 𝐥𝐚𝐜𝐤 𝐨𝐟 𝐬𝐮𝐩𝐩𝐨𝐫𝐭.
Have questions about cashless claims? My DMs are always open.
Drop your questions in the comments or DM me to review your policy today! 🩺🤝
#Claim #mediclaim #insurance
@AKKANKARIYA29@HDFCERGOGIC Always buy insurance from an advisor.
Happy to assist you, in case you need any help!
No sales obligation, No misselling. Just genuine discussion.
𝟕𝟎% 𝐨𝐟 𝐈𝐧𝐝𝐢𝐚𝐧 𝐟𝐚𝐦𝐢𝐥𝐢𝐞𝐬 𝐚𝐫𝐞 𝐣𝐮𝐬𝐭 𝐎𝐍𝐄 𝐦𝐚𝐣𝐨𝐫 𝐡𝐨𝐬𝐩𝐢𝐭𝐚𝐥 𝐛𝐢𝐥𝐥 𝐚𝐰𝐚𝐲 𝐟𝐫𝐨𝐦 𝐟𝐢𝐧𝐚𝐧𝐜𝐢𝐚𝐥 𝐫𝐮𝐢𝐧.
Medical inflation in India is running wild at ~14% a year. That means hospital costs literally DOUBLE every 4 to 5 years.
If you think your savings or corporate policy will save you, you need to read this thread 🧵
#insurance #mediclaim
Please send this to your parents, your spouse, or that one friend who thinks they are "too healthy" for insurance.
It takes 2 minutes to read, but it can save someone’s life savings.