Update: Over the last five trading days, the #SOFR futures curve has retraced as much as 85% of the dovish repricing seen during the prior six weeks (Sep 28 to Nov 5).
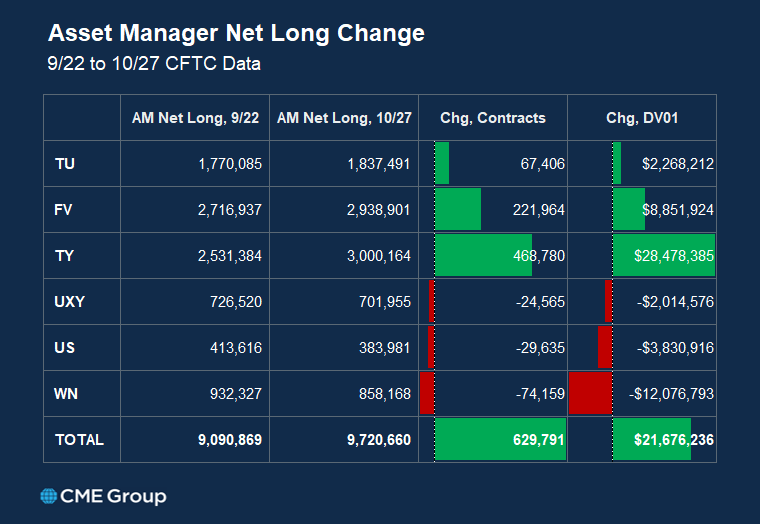
Asset managers shift risk to the belly, extend record net long in TY.
From 9/22 to 10/27, asset managers extended their net long position in Treasury futures by $21.6m DV01, shifting risk from the long end to the belly, where they have built a substantial record net long in TY.
Asset managers shift risk to the belly, extend record net long in TY.
From 9/22 to 10/27, asset managers extended their net long position in Treasury futures by $21.6m DV01, shifting risk from the long end to the belly, where they have built a substantial record net long in TY.
Synchronized global rate hikes tell us something bigger is happening: shared inflationary pressure, tightening financial conditions everywhere at once, and a global economy moving in the same direction. The question is what comes next. 💬 #AskTheEconomist breaks it down.
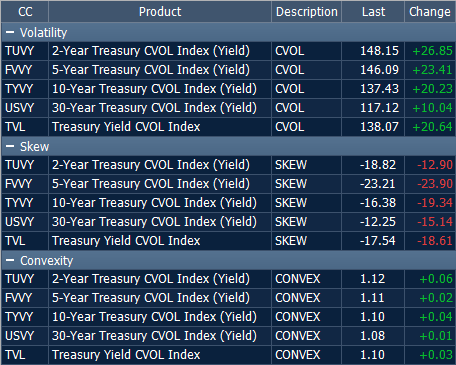
Treasury yield volatility surging across the curve.
Skew sharply lower, convexity higher, suggesting rising demand for protection against lower yields and extreme moves.
CME-FICC Cross-Margining
🔹Opened to clients and end-users in April
🔹Delivers up to 80% margin offsets between CME-cleared Treasury futures and FICC-cleared UST cash and repo
🔹Average daily savings grew from $1B earlier this year to $2.3B in September
Unrivaled liquidity 🤝 unmatched capital efficiency
Demand for balance sheet efficiency continues to be met at CME Group, where portfolio margining and CME-FICC cross-margining helped clients optimize margins across interest rate positions to the tune of $15B/day last month.
Portfolio Margining (Cleared IRS vs. futures & options)
🔹Record average daily savings of $13B in September
🔹Daily savings climbing towards $15B in October
🔹USD IRS notional volume +75% YoY as clients increasingly opt to clear at CME Group to take advantage of this program