The geometry of markets predicts the following.
The most precious thing in markets right now is distilled US and Japanese duration.
There will be an increasing shortage of both.
- Yield Curve flattening, inversion & duration: The US currently has an increasing glut of savings (negative duration).
- The 2 curves, the "FIGHT" (5-to-10-year) and "NOB" (10-to-30-year) —both began flattening over a year ago on September 2, 2025.
- The flattening of those curves will accelerate their through inversion and will exceed the inversion level that triggered the failure of Silicon Valley Bank in Q1 2023 and that Powell transitorily reversed in Q3 2023 by prematurely ending rate hikes prior to achieving his 2% inflation target.
- Treasuries: The Treasury complex will experience a bull flattener as bond kurtosis and volatility decay toward their minimums.
- This is driven in part by Chairman Warsh’s shift toward a more laissez-faire policy, eschewing the hyper accommodative approach of BYP, )Bernanke, Yellen and Powell).
- Warsh’s policy stance, will normalize the kurtosis, skew and volatility curves of sovereigns and that will mechanically flatten the yield curve deep into inversion.
- Currencies: The US Dollar and Japanese Yen will strengthen at an accelerating pace alongside accelerating beta deflation.
- Equity Beta expansion has been decelerating since 2023 and is about to fall below the level it was one year ago and it is about 5% above zero outperformance versus the S&P 500 over 26 months
- Commodities and Crypto: Commodity markets will drop to new one-year lows before the conclusion of the wars involving Iran and Russia.
- Bitcoin is a yield free commodity.
- Mortgages & Labor: Pre-payment speeds will accelerate at an increasing pace, tightening US labor markets due to the embedded option in the US mortgage structure.
- Rates & Policy: Mortgage rates will fall below their multi-year low of 5.99% and accelerate lower. This will eventually force Chairman Warsh into an easing program as the US budget deficit shrinks to 3% or lower.
The poetry of an ever increasing supply of investment opportunities in excess of savings is fiction.
Markets go in cycles, of greed and fear, of FOMO and failure.
This is a normal wave function that has been interrupted by excessive policy interference during the last three federal reserve chairmanships.
Focus on the geometry and not the poetry.
- Below will be a link to our initial post short bonds and beta on 1/3/22 and it’s reversal to maximum beta 10/28/22. Then a gradual migration of Capital away from Beta to low volatility 7/17/24.
- Beta outperformance of the S&P 500 is down to only 5% over the last 2.2 years, and now we’re looking for an acceleration of capital out of high beta into interest rate sensitive, low beta and sovereigns.
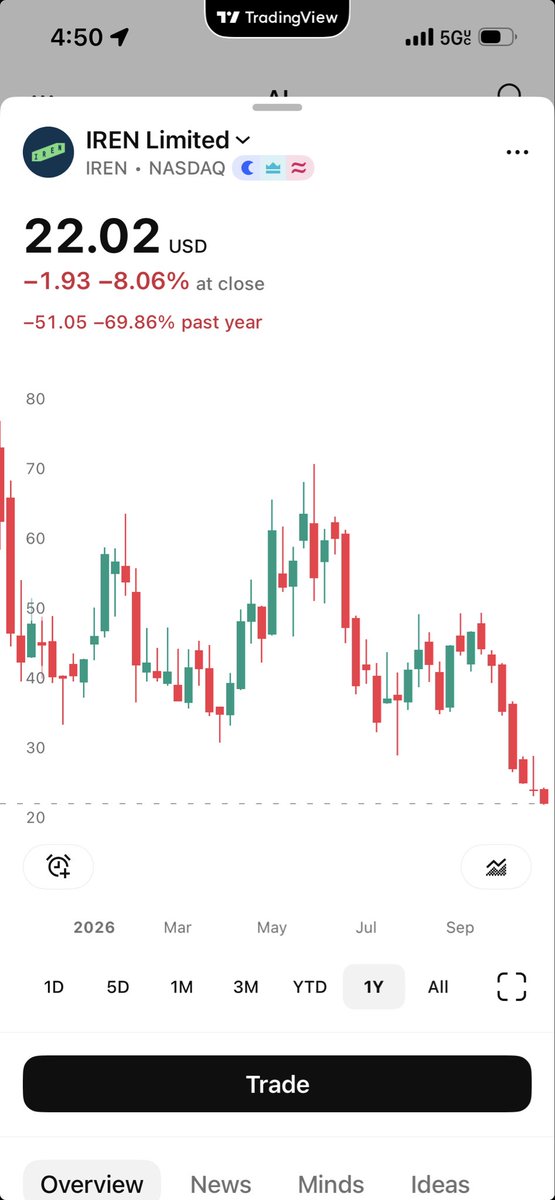
- Beta deflation will be observable only if you monitor for most people; the poetry of markets is grabbing too much screen time and the AI credit decay isn’t getting nearly enough attention.
Asset deflation leads to consumer price deflation.
. https://t.co/KOpuYv22Vj
https://t.co/TivwArcTq1
My assumptions:
1. Trump admin wants equity markets to pump into midterms
2. A hike on Sept 16 doesn’t make sense - DXY would rally/curve would flatten more into midterms
3. Fed needs a “reason” to not hike - Warsh maintains credibility
4. Vol spasm between now and CPI
Waller rhetoric shifted Sept FOMC odds back to a coin flip - the stage is set for an aggressive whipsaw.
Strong beat on payrolls tomorrow AM should get the party started. Right as we head into the Fed quiet period. Let’s see…
Seemingly the only account talking about JNK/XCCC is @PolarityRadio
Breaking out to new all time highs. The market experienced significant volatility the last two times this ratio spiked (March 2026 and liberation day).
Feels like the vol is coming any minute now
@briantribbitt 🎯squeeze is imminent IMO. I think the administration needs a vol spasm between now and FOMC to give Warsh & co a reason to hold rates steady. DXY should then weaken and equities higher into midterms.
Downside? No one cares.
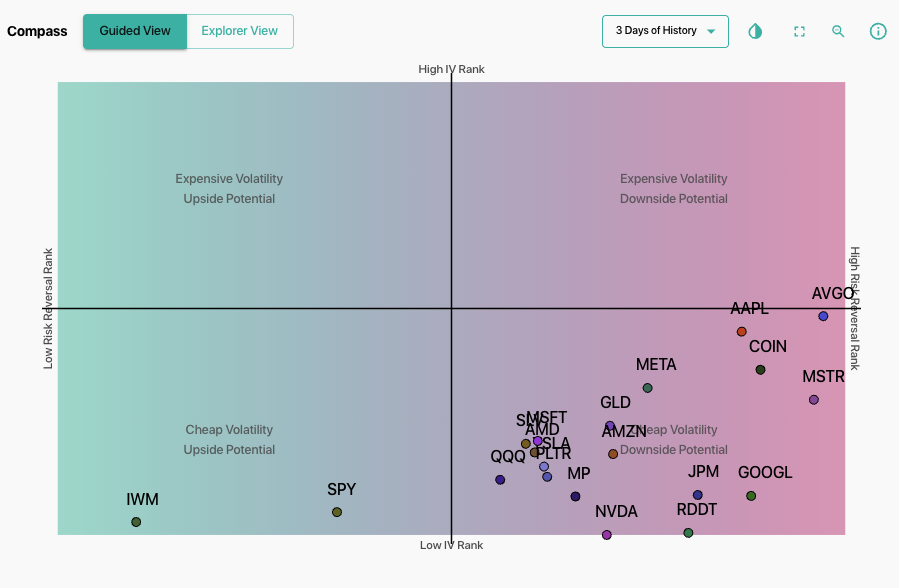
The bottom right of this quadrant = calls skews ranking higher than puts.
<7,600 in SPX is likely where these calls skews come off
@jam_croissant@tastyliveshow Well said. There’s a 25% chance of no rate hike by midterms. I think that’s the fuel for an equity squeeze into Nov. IMO the likely window for a vol spasm is between now and Sept 16. Rate hikes getting priced out will weaken DXY, steepen curve, and send equities higher. Thoughts?