🧵 All My Stock Picks in One Place! 🧵
Hey there, fellow investors! 🌟📈🚀
I’ve been diving deep into exciting sectors like EV tech 🚗⚡, aerospace ✈️, IT infrastructure 💻, and more! But let’s face it—keeping track of all those stock insights can be a challenge.
🔗 Introducing My Google Sheet Tracker! 🔗
💼✨ I’ve consolidated ALL the stocks I’ve covered so far into one easy-to-use spreadsheet. Access it here:
📋https://t.co/300F11rx4A
💡 What’s Inside?
🔥 Thomas Scott India Limited (TSIL) 🇮🇳
🚀 Unimech Aerospace & Manufacturing Ltd (UAML) ✈️
🌐 Allied Digital Services Ltd (ADSL) 🖥️
🔧 Sterling Tools Ltd. (STL) 🔩
...and so many more promising companies! 🌟
📅 Future Updates?
💹 Every time I share a new stock pick or analysis, it’ll be updated here. 🕵️♂️ No more scrolling through endless threads to find the gems!
✨ Why You’ll Love This:
✅ Easy Reference: One click, all insights! 👆
✅ Stay Organized: Your investment research, streamlined. 📚
✅ Efficiency: Instant access = saved time. ⏱️
📍 I’ve pinned this post for your convenience!
Let’s make smarter investment decisions, together. 🌍🚀📊
👉 Bookmark, share, and grow your portfolio with me
China's Electricity Consumption Surpasses Combined Total of US, Europe, and India
In 2024, China consumed over 9.5 trillion kWh, exceeding the total consumption of these major economies.
Meanwhile, the EU faces stagnation and declining demand for electricity.
In Germany, forecasts for electricity demand by 2030 have been revised downward, with officials stating that at current energy prices, no new industrial production facilities are expected to open.
Zomato Limited And Jio Financial Services Limited To Enter Nifty50 Index By Replacing BPCL And Britannia Industries Limited
Extremely Unhappy With This Development
This Will Make Nifty50 Expensive
Included
▪︎ Zomato : FY24 PE - 635×
FY25 TTM - 342×
▪︎ Jio Financial : FY24 PE : 93×
FY25 TTM : 86×
Excluded
▪︎ BPCL : FY24 PE - 4.06×
FY25 TTM - 9.2×
▪︎ Britannia : FY24 PE - 54.5×
FY25 TTM - 54×
This Small Reshuffling Will Increase Nifty's Valuations By ~2.6%
Zomato Is A Good Company, No Doubt About It But It's Still Not A Mature Business, It Was Surely A Nifty Contender But Atleast After Three Years After Proven Profitability Track Record And Jio Financial Services Has Barely Any Business With 25% PAT Coming From Other Income Component And No Visibility Of Business Operations
Zomato And Jio Financial Services Have Very Less Public Markets Track Record
Two Recently Listed Companies, One From Them With No Business Have Replaced Two Extremely Mature Businesses Who Were Nifty50 Components From A Long Time
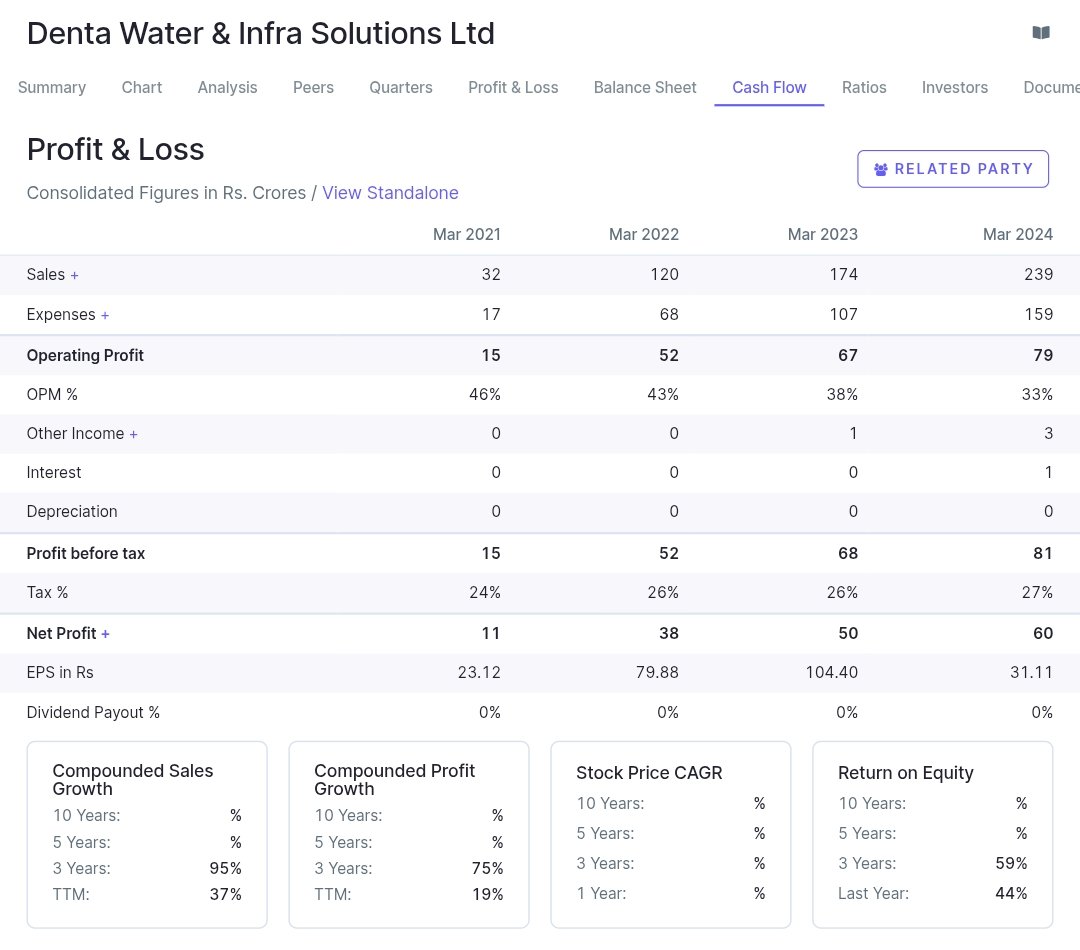
📌 Strong Q3FY25 on both YoY and QoQ from Denta Water & Infra Solutions
➡️ Revenue
52.3cr vs 46cr (13.7% up YoY) & 48.4cr (QoQ)
➡️ PAT
14.9cr vs 6.6cr (125% up YoY🔥) & 11cr (QoQ)
✅ Significant increase in margins
Denta Water & Infra Solutions Ltd🌊🔧
Company Overview 🏗️
Founded in 2016
Specializes in water engineering, procurement, and construction (EPC) services
Focuses on water management infrastructure projects
Services Provided 🌍
Groundwater recharging through recycled water 💧
Lift irrigation projects 🚜
Drinking water supply 🚰
Treated wastewater reuse ♻️
Key Projects 🎯
KC Valley Project (Phase 1) - Bengaluru's big water project 🌆
Jal Jeevan Mission - Drinking water initiatives 🥤
Byrapura, Hiremagaluru, and Karagada Lift Irrigation System (LIS) projects 🌾
Geographical Focus 📍
Primarily operates in Karnataka
Projects in drought-prone areas to manage water resources effectively 🏜️
Financial Performance 📊
Sales Growth: 95% over 3 years 🚀
Profit Growth: 75% over 3 years 💹
Revenue from operations: Increased from Rs 119.57 crore in FY22 to Rs 238.60 crore in FY24 📈
Profit After Tax (PAT): Increased from Rs 38.34 crore in FY22 to Rs 59.72 crore in FY24 💰
Additional Information 📚
Uses advanced technologies like GIS for mapping and GPS for location mapping 🗺️
Has completed 32 water management projects as of Nov 30, 2024 ✅
Developing 445.77 km of water management infrastructure 🛠️
IPO Details 📅
Issue Size: Rs 220.50 crore 🪙
Price Band: Rs 279 to Rs 294 per share 💵
IPO Dates: Open from January 22, 2025, to January 24, 2025 🗓️
Listing Date: January 29, 2025 📅
Lot Size: 50 shares 🧾
GMP (Grey Market Premium): Rs 135 as of January 24, 2025 📉
Market Perception 🧐
GMP indicates strong investor interest 🧑💼
Expected listing gain of approximately 46% 📈
Valuation Metrics:
P/E Ratio: 13x (at the upper price band) based on the FY24 earnings, which is relatively reasonable considering the growth prospects and sector dynamics 📊
Market Cap to Sales: 3.29x, indicating the market's valuation of the company's revenue potential 📈
ROCE: 77% (FY24), showing efficient use of capital and strong profitability metrics 💹
Growth and Financial Health: The company's impressive growth in sales (95% over 3 years) and profits (75% over 3 years) supports the valuation, reflecting investor confidence in future growth and profitability.
Comparative Valuation: When compared to peers in the water management and infrastructure sector, the valuation seems competitive, considering Denta Water's growth rate, profitability, and strategic positioning in a growing market segment 💼
#Multibagger #PEExpansion #HighGrowthSector #WaterInfra
Denta Water & Infra Solutions Ltd Listing Update 🌊🔧🚀
After much anticipation, Denta Water & Infra Solutions Ltd has officially listed today! Here's the rundown:
The stock listed at a muted price of ₹325 on NSE 📉, a gain of 10.5% 📈 from the upper price band.
On BSE, it listed slightly higher at ₹330 📊, marking a 12.2% gain. 🎉
Given these listing prices, this presents a GREAT OPPORTUNITY to enter into this stock! 🎉🌟 Here's why:
Low Valuation 💰: The stock listed at a very low valuation in comparison to its growth potential and industry standards. With a P/E ratio of 13.1x at listing, based on FY24 earnings, it's relatively undervalued considering the sector's dynamics and Denta Water's impressive growth trajectory. 📉🔍
Growth Prospects 🌱: With sales growth of 95% 📈 and profit growth of 75% 📈 over the last 3 years, the company's financial health is robust, offering a promising future for investors. The company's involvement in critical water management projects in Karnataka, especially in drought-prone areas 🏜️, positions it well for future expansion.
Market Perception 🧐: The initial listing gain, although modest, coupled with the GMP of Rs 135 💸 before listing, indicates strong investor interest and confidence in the company's future. This muted listing might be seen as a dip in what could be a long-term upward trend. 📈🔥
Strategic Positioning 🎯: Denta Water's focus on water infrastructure 💧, a sector with increasing demand due to water scarcity issues, aligns with government initiatives like Jal Jeevan Mission 🇮🇳, ensuring a steady flow of projects and revenue. Their use of advanced technologies like GIS 🗺️ and GPS 📍 for project execution adds to their competitive edge.
For investors considering long-term gains, this listing at a lower valuation provides an EXCELLENT ENTRY POINT! 🤑 Remember, the growth in sales and profits, along with the strategic focus on a critical sector, suggests that Denta Water & Infra Solutions Ltd could be a valuable addition to your portfolio. 💼✨
Now is the TIME to decide on your investment in Denta Water & Infra Solutions Ltd. 🧐💼🚀
#InvestmentOpportunity 💡 #WaterManagement 💧 #LowValuation 💸 #GrowthStock 📈 #DentaWater 🌊
Disclaimer: 🚨 This analysis is for educational purposes only and should not be considered as investment advice. Always conduct your own research or consult with a financial advisor before making investment decisions. 📚👨🏫
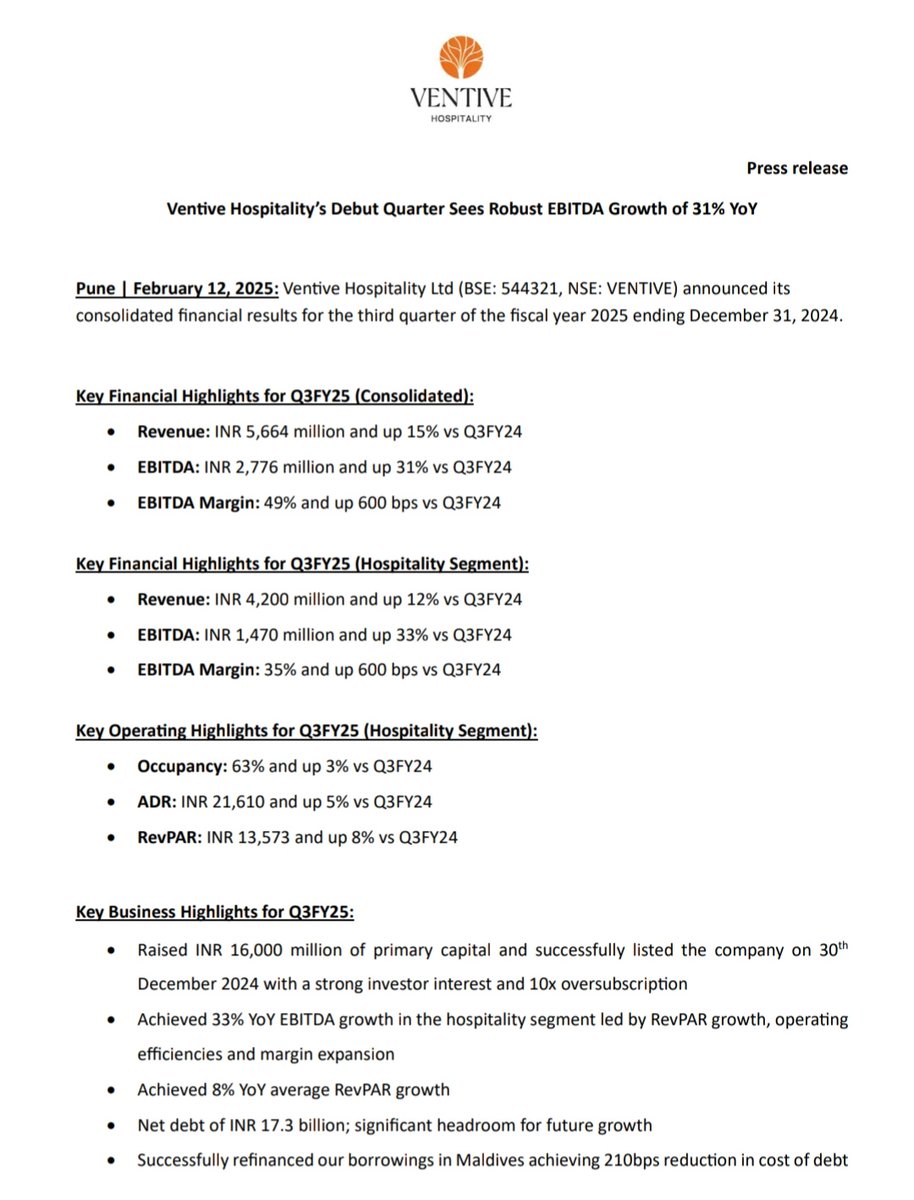
Ventive Hospitality Limited Q3 Results And Investor Presentation
Decent Topline Growth With Significant Margin Expansion 👏
Continues To Maintain Industry's Most Superior Metrics With Operational Efficiencies
Rev : 492➡️566 Cr
EBITDA : 212➡️277.6 Cr
Margin : 43%➡️49% 🤩
PAT : 43.4➡️79.8 Cr
(PAT Comparison At Consol Level Isn't Available So Q3 FY24 Is Taken At Standalone Level And Q3 FY25 is At Consol Level, The Exceptional Item And Adjustment Made On the Course Of Foreign Exchange Gains)
▪︎ Ventive Hospitality Repays 1,400 Cr Debt Raised From IPO Proceeds
Net Debt : 3,199 ➡️ 1,732 Cr
▪︎ Company Refinances Borrowings In The Maldivian Entities And Reduces 210 BPS in Finance Costs
▪︎ From Next Quarter (Q4), The Saving of interest Cost Will Bump Up The PAT Significantly
Operational Metrics :
▪︎ RevPar : 12,537➡️13,573
India Hospitality –
▪︎ ADR : 10,378➡️11,275
▪︎ Occupancy : 62➡️64%
▪︎ RevPar : 6,418➡️7,181
Maldives Hospitality –
▪︎ TRevPar : 63,124➡️69,906
▪︎ Occupancy : 56➡️59%
Average Interest Cost At 8.3%
(Most Superior in The Industry)
▪︎ Cash And Cash Equivalents :
374 Cr
▪︎ Expansion :
– Expansion And Development in Bengaluru
– Brownfield Development in Varanasi (Near Airport)
– Greenfield Development in Sri Lanka (Near Yala East National Park)
▪︎ The Raaya By Atmosphere, The Super Luxury Property in Maldives Portfolio, Isn't Consolidated In The Results, This Will be Consolidated From Q4 Results
▪︎ Q4 Is The Strongest Quarter For The Company And Debt Repayment Will Help In Achieving Significant PAT Growth
9M FY25 –
Rev : 1,442 Cr (17%⬆️)
EBITDA : 641 Cr (33%⬆️)
Q4 is Generally ~35% Of The Complete Year
(This Excludes The Raaya By Atmosphere Property, Which Can Increase The Q4 Topline By 7-10%
By Calculating All These Figures, Company Is On Track To Cross 1150 Cr+ EBITDA in FY25
Currently Trading At 15× FY25E EV/EBITDA
Hope We See Some Institutional Coverage On India's Largest Luxury Focused Hospitality Platform Soon 🤞
🚀 Ventive Hospitality Limited Deep Dive – A Premium Bet on Luxury! 🏨
A deep dive into one of India's rising luxury hospitality players, Ventive Hospitality Limited. Is this company worth your attention? Let's break it down! 🧵👇
1️⃣ Company Overview 📜
🔹 Founded in 2002 under Panchshil Realty
🔹 Focus: Luxury & upscale hospitality in business & leisure segments
🔹 Strategy: Asset ownership, development & management
🔹 Key Partnerships: Marriott, Hilton, Minor, Atmosphere
🔹 Operates 11 hotels, 2,036 keys across 🇮🇳 India & 🇲🇻 Maldives
2️⃣ Ownership & Leadership 🏢
🔹 Panchshil Realty – Majority stakeholder (57%)
🔹 Blackstone – Owns 33% (strong private equity backing 💰)
🔹 Leadership: Asset management team collaborates with operators to maximize performance
3️⃣ Brand Portfolio 🌟
🏨 JW Marriott
🏨 The Ritz-Carlton
🏨 Conrad
📍 Locations: Pune, Bengaluru, Varanasi, Maldives
🔹 Premium brands = High ARR (Average Room Rate) 💲
4️⃣ Financial Performance 📊
💰 Revenue Growth:
➡️ ₹229.17 Cr in FY22
➡️ ₹477.98 Cr in FY24 (+108% growth!) 🚀
📉 PAT Growth (Profit After Tax):
➡️ ₹29.43 Cr (FY22) ➡️ ₹166.32 Cr (FY24)
➡️ BUT a -526% drop from FY23 to FY24 📉 (concern for investors!)
5️⃣ Expansion Plans 🌍
🔹 Increasing hotel keys by 18% by FY28
🔹 Focus on prime business & luxury tourist destinations
🔹 Heavy CAPEX (Capital Expenditure) for growth
6️⃣ Strategic Advantages ✅
🌟 Strong global brand partnerships
📍 Prime locations in India & Maldives
💰 Premium ARR positioning = High Revenue per Room
7️⃣ Key Risks & Challenges ⚠️
💸 High financial leverage (Debt concerns!)
🌍 Luxury hospitality is cyclical (Economic downturns = lower demand)
🏨 Depends on third-party operators (Brand reputation risk)
8️⃣ Peer Comparison 🆚
🔹 Chalet Hotels Ltd
🔹 Indian Hotels Company Ltd (Taj Group)
🔹 EIH Ltd (Oberoi Group)
🔹 Lemon Tree Hotels Ltd
🔹 Apeejay Surrendra Park Hotels Ltd
🔹 Ventive has lower revenue & net worth than Indian Hotels & EIH
🔹 BUT: High ARR positioning gives a competitive edge in luxury
9️⃣ Market Trends 📈
🔹 Luxury travel demand booming post-COVID 🌍
🔹 Sustainability in hospitality is a growing focus ♻️
🔹 Technology integration (AI-driven guest services, IoT for room automation) 🤖
🔍 Verdict: Should You Invest?
✅ For risk-takers: Strong brand + premium positioning = Potential long-term winner
⚠️ For cautious investors: Debt levels, PAT drop, and execution risks need close monitoring
Disclaimer: It's not a buy sell recommendations. It's just for the educational purpose.
💬 What do you think? Would you invest in Ventive Hospitality Limited? Drop your thoughts below! 👇
#Ventive #LuxuryHospitality #Investment #MultibaggerStock
Excited to announce that SJ Logistics is at Breakbulk Middle East 2025! Meet us at Booth L41 to discuss seamless project cargo and logistics solutions.
📍 Dubai World Trade Centre | 📅 10-11 Feb 2025
Please Visit Us Now—See You Everyone!
#SJLogistics#BreakbulkME2025#Dubai
@SpangleAdvisors@Vismaya9999@vivbajaj Really sir, the podcast was amazing. I have seen it twice and am planning to watch one more time tomorrow. You have put up your complete stock market experience in a single video.
Amazing #Face2Face podcast done by @vivbajaj with @SpangleAdvisors. Key Takeaways from the Podcast 🚀🎙️
1️⃣ Investing Philosophy
Everyone should invest to seize life-changing opportunities.
A single stock can be transformative—find quality businesses and hold long-term.
Patience builds wealth; selling winners too early leads to regret.
Market dips and drawdowns are normal; conviction pays off.
Investing is about partnering with businesses, not just trading stocks.
2️⃣ Amit Sir's Market Journey
Grew up around stocks but initially focused on speculation.
Shifted from trader to investor post-2013, prioritizing risk management.
Capital preservation is key—you can’t win if you’re wiped out.
Early believer in the SME sector, which has grown significantly post-COVID.
3️⃣ Investment Process
Meets 20-25 companies monthly for deep insights.
Management quality is critical—ethical leadership drives success.
Goes beyond numbers, speaking to stakeholders for a 360° view.
Prefers established businesses needing capital over risky startups.
Keeps stakes below 5% to manage risk, investing for long-term growth.
4️⃣ Advice for New Investors
Research is crucial—don’t rely solely on readily available data.
Learn analysis instead of chasing stock tips.
SME sector offers hidden gems for those willing to dig deep.
5️⃣ Valuation & Risk Management
Seeks undervalued stocks with a margin of safety.
Avoids misleading order books—revenue doesn’t always mean profit.
Prefers averaging up in strong performers rather than selling winners.
Uses market corrections to buy more rather than panic-selling.
6️⃣ Sectoral Bets & Mega Trends
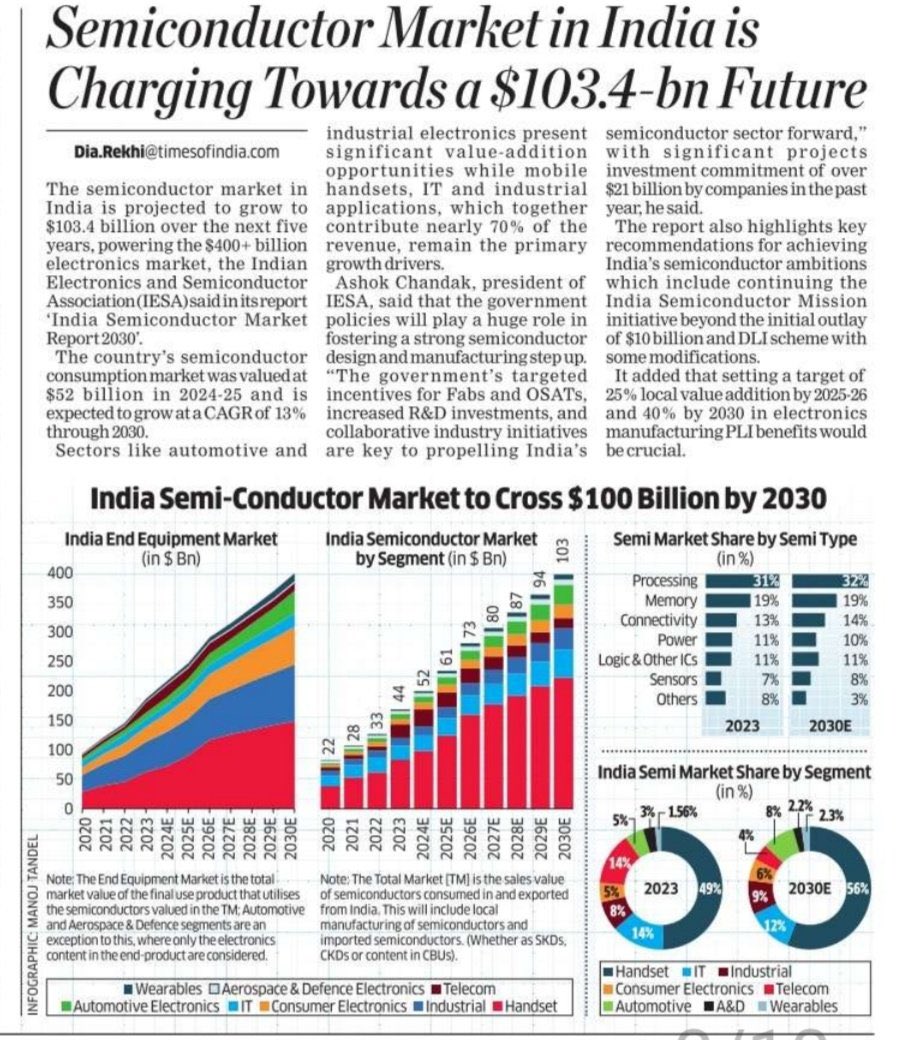
Bullish on: Semiconductors, defense, power transmission, data centers, capital goods.
Believes India’s self-reliance push will fuel manufacturing growth.
7️⃣ Portfolio Strategy
No fixed allocation—invests based on conviction.
Comfortable making large additional investments in winners.
Contrarian investor—prefers undervalued stocks over momentum plays.
Avoids companies with governance issues unless they stem from fixable mistakes.
8️⃣ Final Thoughts
Investing is about understanding businesses, not just stock prices.
Learning from experienced investors provides unique insights.
Stay invested in great companies—don’t exit too soon.
Wealth creation is a result of smart, patient investing.
🎤 Conclusion: Amit Sir’s strategy is a blend of deep research, patience, and conviction in long-term winners. His ability to identify hidden gems and stay invested sets him apart. Investors should focus on understanding businesses, managing risks, and staying patient through market cycles. 🚀
🧵 Finally a direct play in the Data Centre theme: Sify Infinit Spaces Limited:
🚀 Overview:
Public Limited Company in India
Incorporated: November 20, 2017
Based in Chennai, Tamil Nadu
📊 Financials:
Authorized Capital: ₹1,000 crore
Paid-up Capital: ₹555.86 crore
FY 2022 Growth:
Revenue Up by 35.01% 📈
Profit Increased by 8.68% 💰
Net Worth Up by 14.67% 📊
🏢 Business Focus:
IT Sector, specifically Data Center Services
Wholly owned by Nasdaq-listed Sify Technologies Limited
👥 Leadership:
CFO: Veeraraghavan Ramanujan
Company Secretary: Devendiriya Poornasandar
Directors include:
Arun Seth
Vegesna Raju
Rajeswara Chinjaluri
💸 Market Activities:
IPO Planned: Aiming to raise ₹3,000 crore
Expected in FY26 📅
Bankers appointed for IPO management
📅 Recent Financial Moves:
October 2024: Launched first NCD issue
Amount: ₹250 crore
Rating: AA- by CARE
Coupon Rate: 8.95%
Fully subscribed on listing ✅
🌐 Operational Scale:
Data Center Capacity: 190 MW
Presence: 19 cities across India 🌍
🔑 Strategic Importance:
Key player in India's data center market
Growth driven by digital transformation, cloud computing, and internet expansion
🔮 Future Outlook:
With the planned IPO, SISL aims to expand further, enhancing its infrastructure and market position.
This thread provides a snapshot of Sify Infinit Spaces Limited's current standing and future plans. Keep an eye out for more updates as they navigate through their IPO process! 📈🔍
Finally A Direct Play In The Data Centre Theme Eyeing A Public Listing !!
Sify Infinit Spaces Limited, The Data Centre Arm Of Nasdaq Listed Sify Technologies Limited Hires Bankers For 3,000 Cr IPO
The Data Centre Operator Which Has Installed Capacity Of 190 MW In 19 Cities Like Bangalore, Kolkata, Noida, Chennai, Mumbai, Hyderabad Has Picked Three Bankers For It's IPO
Sify Infinit Spaces Limited Had Recently Announced That It Has Became An NVIDIA Collocation Partner Which Would Support AI Servers With Certified Liquid Cooling Technology
With This Development, Sify's Data Centres Can Support 7-8 GPU Servers Per Rack With ~130 kw Capacity Per Rack Catering To Hyperscalers And Enterprise Needs For AI Computation Solutions
In September 2023, Kotak Data Centre Fund (KDCF) Had Invested 600 Cr In Sify Infinit Spaces Limited Which is Likely To Take A Part Exit via IPO
Sify Infinit Spaces Limited Has Posted 1,100 Cr+ Revenues in FY24 With ~60 Cr PAT And 674 Cr Revenues In H1 FY25 With ~50 Cr PAT
The Data Centre Arm Of Sify Technologies Expects Revenues To Double By FY27
🚀 India's GPU Revolution & Netweb’s Strategic Edge
🇮🇳 India’s AI ambitions get a boost!
Nvidia, AMD & HPE are in talks with MeitY to develop indigenous GPUs—a major step towards self-sufficiency in AI & computing tech. 💡
🔥 Why this matters?
Reduces reliance on imported chips 🏭
Lowers AI infrastructure costs 💰
Strengthens India’s tech ecosystem 🔗
🖥️ Targeted GPU models include:
Nvidia: H100, H200, A100, L4
AMD: MI 325X
Intel: Gaudi-2
🏆 Netweb Technologies: The Big Winner?
Already partners with Nvidia 🤝, manufacturing GPU servers in 🇮🇳
Experience in Grace CPU & GH200 Superchip design 💪
🛠️ Expanding AI Product Portfolio
Govt push for local GPUs = More AI-optimized servers ⚙️
Netweb’s Tyrone AI systems can integrate indigenous GPUs 🚀
💰 Government Support = More Gains
Eligible for PLI incentives for IT hardware 📈
Lower costs, more scale, better margins ✅
🏗️ Building a Local AI Ecosystem
New suppliers, developers & R&D hubs 🔬
Collaborations with startups & universities 🎓
🌍 Market Leadership & Expansion
First-mover advantage in India’s GPU space ⚡
Broader customer base (Govt, academia, enterprises) 🏢
Potential global opportunities 🌎
⚙️ Reduced Dependency on Imports
Affordable AI infrastructure for Indian startups 💡
Cost-effective GPUs = Higher adoption 📊
Long-Term Growth & Sustainability
Aligns with India’s Atmanirbhar Bharat vision 🇮🇳
Focus on energy-efficient AI computing 🔋
📢 Netweb Technologies is primed to lead India’s AI future! 🚀 #AI #GPU #IndiaTech
In investing, patience is key, very well explained by @prateek_madaan1. We should spend 99% of our time in analyzing of a stock/idea, 1% in executing. Avoid the impulse, embrace the strategy. #LongTermInvesting#PatiencePays
𝐒𝐨𝐦𝐞 𝐯𝐞𝐫𝐲 𝐢𝐦𝐩𝐨𝐫𝐭𝐚𝐧𝐭 𝐨𝐛𝐬𝐞𝐫𝐯𝐚𝐭𝐢𝐨𝐧𝐬 𝐭𝐡𝐚𝐭 𝐰𝐢𝐥𝐥 𝐡𝐞𝐥𝐩 𝐲𝐨𝐮 𝐬𝐮𝐜𝐜𝐞𝐞𝐝 𝐚𝐬 𝐚 𝐥𝐨𝐧𝐠 𝐭𝐞𝐫𝐦 𝐢𝐧𝐯𝐞𝐬𝐭𝐨𝐫 :
Many people buy stocks impulsively, often chasing trends or news. This leads to a scattered, unfocused portfolio that lacks proper strategy or conviction. Such behavior increases transaction costs, emotional stress, and exposure to market volatility without proper analysis.
Waiting for Opportunity :
Successful investing requires patience. Legendary investors like Warren Buffett often emphasize that you don’t have to swing at every pitch. Opportunities where the risk-reward ratio is strongly favorable might not come every day, but when they do, you need to act decisively.
Analysis vs. Execution :
99% Analysis:
Understanding a business, its financial health, competitive position, industry dynamics, and growth prospects is crucial. This includes reading annual reports, following management commentary, and monitoring performance metrics.
1% Order Execution:
Once you've identified a strong opportunity, you execute your trade strategically. The actual act of buying is the easy part, provided your analysis is sound.
By focusing on well-researched opportunities, you’re better positioned to endure market fluctuations and hold onto quality investments. Impulse buyers, on the other hand, often panic and sell at a loss.
Breakdown of Union Budget 2025 Capex
Union Budget 2025 has allocated ₹11.21 lakh crore for capex in FY 2026
🔖Defence (2025 Vs 2024)
🏷️₹6, 21, 940 Vs ₹6, 81,210 (10%)
💠₹1, 92,387 Cr – Capital Outlay
💠₹48,614 Cr – Aircrafts & Aero Engine
💠₹24,390 Cr – Naval Fleet Related
💠₹63,099 Cr – Other Equipment
🔖Rural & Urban Dev (2025 Vs 2024)
🏷️₹2, 66,817 Vs 1, 80,233 Cr (48%)
💠₹1, 00,000 Cr – Urban challenge fund
💠₹82,577 Cr – For MoHUA
🔖Railways (2025 Vs 2024)
🏷️₹2, 52, 000 Vs ₹2, 40,200 Cr (5%)
🔖Agriculture (2025 Vs 2024)
🏷️₹1, 51, 000 Vs ₹1, 71, 000 Cr (13.2%)
💠₹8,500 Cr – For RKVY
🔖Education (2025 Vs 2024)
🏷️ ₹1, 28,650 Vs ₹1, 21, 000 Cr (6.6%)
💠₹78,572 Cr – Schools
💠₹50,077Cr – Higher Education
💠₹500 Cr – Centre of Excellence in AI for education
🔖Health Care (2025 Vs 2024)
🏷️₹98,311 Vs ₹90,958 (9.78%)
💠₹37,226 Cr – National Health Mission
💠₹9,406 Cr – AB PM-JAY
💠₹4,200 Cr – PMABHIM
💠₹2,445 Cr – PLI for Pharma Industry
#Budget2025