As I received a good response, here you go
My Diwali Picks 🎇
1. Satin Creditcare
2. Raymond Realty
3. Sammaan Capital
4. P N Gadgil Jewellers
These are not direct buy/sell recommendations. Just four companies where I believe the risk-reward looks interesting and which have the potential to perform well over the next 12 months.
Two Special Mentions 👀
1. Prime Cables
2. Purple United Kids
Both are SME companies, so please be VERY careful. SME stocks carry significantly higher risks, liquidity constraints and volatility. Things can change quickly, so position sizing and risk management are extremely important.
Would be interesting to revisit this post next Diwali and see how these picks have performed.
Let's see how this plays out! 😊
Very few Diwali picks showing up on my timeline this time.
Would you be interested in seeing my picks?
Drop a comment below. If there's enough interest, I'll share my list! 👇
The realty sector is indeed undervalued and completely ignored.
Good to see PPFAS betting on DLF.
Looking at the MMR redevelopment opportunity and Raymond Realty's valuation, I cannot stop myself from adding at each dip.
The entire sector is trading at cheap multiples, not just Raymond Realty.
But I believe Raymond Realty is dirt cheap; whenever the realty sector becomes a hot theme, Raymond Realty will surprise many.
Then there are some analysts who have their own magical formulas for calculating certain ratios. Only God knows where those numbers come from
@grok do you think these calculations are correct for credit access grameen.
One big positive is -
Guarantee Fee: Decrease in guarantee fee from 1% p.a. to @ 0.75% p.a.
No change for SHG; continue to pay guarantee fee of 0.25% for the first year and 0.50% in subsequent years.
Big Positive for the MFI sector.
Although Satin is currently not availing the credit guarantee scheme, this can encourage more NBFCs, MFIs and SFBs to extend credit to underserved borrowers and micro-enterprises.
The guarantee reduces the downside risk for lenders, particularly those with limited experience in these segments or weaker risk-management infrastructure.
This can improve formal credit penetration at the bottom of the pyramid, bring more borrowers into the organised lending ecosystem and potentially support sustainable credit growth.
The important thing is that this should translate into responsible lending rather than another cycle of aggressive disbursements.
The Cabinet approval for continuation of the Credit Guarantee Fund for Micro Units is a major boost for India's aspiring entrepreneurs, especially our youth!
What does this mean?
Rs. 5,000 crore corpus to help facilitate over Rs 12.5 lakh crore in MUDRA loans over the next 5 years.
Credit guarantee support for collateral-free loans up to Rs. 20 lakh under PM MUDRA Yojana.
Lower guarantee fees to encourage lending to micro-enterprises.
Our aim is to empower more young Indians to turn their ideas into enterprises, create opportunities and become job creators.
https://t.co/VH823yxezC
@vbomkara Satin creditcare (0.9 PB ~20% ROE in Q2 annualised )
Muthoot Microfin (0.9 PB ~15% ROE in Q2 annualised )
MFI players are Guiding the ROE to expand further as the AUM grows cost to income will further fall and ROEs will further improve. Credit cost guidance are encouraging.
IDK dude, how closely are you tracking this sector?
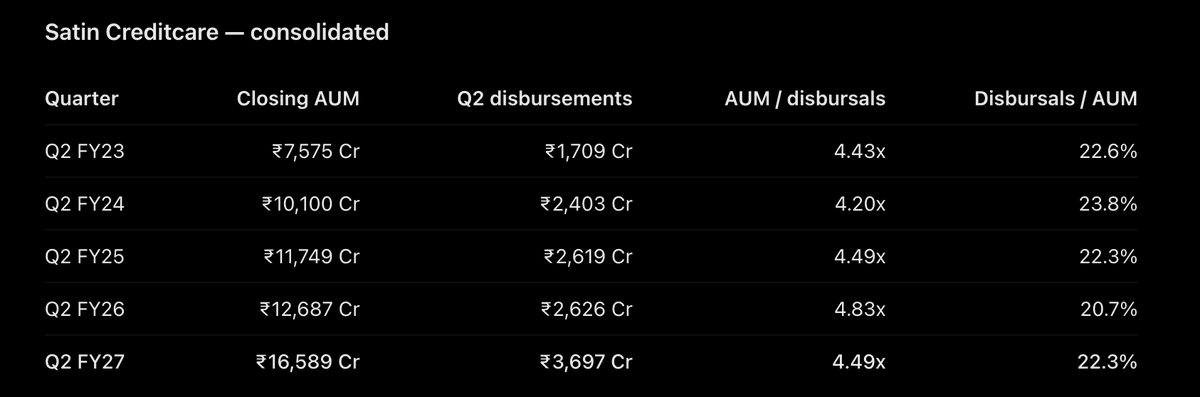
The AUM to disbursement ratio of top players like Satin, CAG and Arman is pretty much in line with previous years. Q2 is usually a weaker quarter for disbursements, which tend to pick up from Q3 onwards. That's exactly what managements have been commenting on. Go through the Muthoot Microfin and Arman concalls. Both have explicitly mentioned that disbursements picked up in October.
Satin, CreditAccess, Arman and Muthoot Microfin are all guiding for 20%+ AUM growth and are pretty much on track. Just look at the H1 numbers.
Coming to repayments, Satin reported 99.8% X-bucket collection efficiency and Muthoot reported 99.9%. Except for Maharashtra, the X-bucket is holding up well and is largely in line with Q2 trends. Monsoon-related blips are seen almost every year. Go back and check historical data.
And IDK what you mean by normalcy. Multiple players in the sector reporting 20%+ ROE seems pretty normal to me.
Data for 11-Nov-2026
A) Cash Market Flows
👎 DII net sold ₹8434 cr
👍 FII net bought ₹12563 cr
B) FNO Data
FII On Index Futures
👉 Added 4844 Longs
👉 Covered 15484 Shorts
🚨 FII Long:Short at 31%:69% 🚨
FII net shorts at 70k contracts, reduced by 70% in Nov 2026 🩳
The realty sector is indeed undervalued and completely ignored.
Good to see PPFAS betting on DLF.
Looking at the MMR redevelopment opportunity and Raymond Realty's valuation, I cannot stop myself from adding at each dip.
The entire sector is trading at cheap multiples, not just Raymond Realty.
But I believe Raymond Realty is dirt cheap; whenever the realty sector becomes a hot theme, Raymond Realty will surprise many.
Why is PPFAS investing in the real estate sector despite disappointing returns?
CIO Rajeev Thakkar says that though DLF was the "hot theme of 2007," PPFAS waited 19 years to buy around ₹640 once the stock faced pessimism and a lack of market interest.
He highlighted that the 2007 thesis is finally materialising: DLF has turned debt-free and possesses a solid balance sheet backed by three core verticals: a steady yield co, an active development arm, and a strategic land bank- listen in.
Full interview: https://t.co/1LRDlopi5M
@hershsayta@sajeetkm@ppfasmf@RajeevThakkar
Kalyan continues to deliver.
Q2 numbers were strong, and the forward earnings trajectory looks encouraging.
Contrarian bets backed by strong fundamentals and a clear trigger often create good opportunities.
At current levels, I believe P N Gadgil offers a better risk-reward.
Kalyan has already established itself as a strong No. 2 player in the industry and proved its execution capabilities.
P N Gadgil is still at a stage where it has to prove that. That's where the potential opportunity lies.
Kalyan Jewellers story is honestly one of the best lessons in how markets can completely lose their mind while the actual business just keeps grinding.
From an all time high near 794 in Jan 2025, the stock crashed almost 40% in a few weeks, wiping out over 20000 crore in market cap. And the irony is the business itself was firing on all cylinders. Revenue crossing 25000 crore, aggressive expansion across India and Middle East, first store opening in the US.
So what actually went wrong. First, a real event. Govt cut customs duty on gold from 15% to 6% in July 2024. This compressed inventory values overnight and Kalyan booked a one time hit of around 120 to 130 crore. Genuine impact, but management was upfront that this was industry wide and fully recoverable by Q4.
Then came the real circus. January 2025 turned into a full blown rumor mill. IT raid rumors that never happened. Fake inventory claims that collapse the moment you look at 450 crore of debt repaid plus 170 crore in dividends, fake books just dont generate that kind of cash. A franchisee revolt story that got massively blown up, when in reality only 3 to 4 partners were terminated over contract breaches. Then the wildest one, bribing fund managers at Motilal Oswal, which MOAMC themselves publicly denied, sending the stock up 7% the very next day. And finally FIR rumors that turned out to be just a civil dispute with one ex franchisee.
On top of all this, promoter pledge panic. People saw the pledge percentage rise and assumed distress, but most of it was old collateral from the Warburg Pincus buyback back in FY20, and the fresh top up was simply because collateral value fell after the stock itself crashed. Classic chicken and egg.
Fast forward to FY26 and the numbers speak for themselves. Revenue past 35700 crore, PAT at 1350 crore, ROCE near 29%. The capital light FOCO engine is clearly working.
Whats next is what gets me excited. 150 new stores planned for FY27. Zero non GML debt targeted by H1 FY27. A brand new regional brand to take on unorganised local jewellers. Candere already PAT positive and scaling with 50 more stores. Plus non core real estate being sold off to clean the balance sheet even further.
The part most people will miss is the EBITDA vs PAT divergence. EBITDA margin looks weaker because FOCO partners take their share of revenue, but PAT margin expands because interest cost basically disappears once debt is gone. Thats the real story, not the headline EBITDA print.
If FY28 plays out as guided, revenue could be near 50000 crore and PAT crossing 2100 crore, and management has even hinted at reopening COCO stores once the balance sheet is fully clean, which could be the next leg of margin expansion.
Sometimes the best setups happen exactly when the noise is loudest and the fundamentals are quietly compounding underneath. Kalyan feels like a textbook case of that.
Retail investors have a habit of chasing themes when they are already nearing the top of the cycle.
If you suddenly see your friends talking about investing in CDMO stocks, and you already own them, you probably know what to do. 🙂
Don't confuse popularity with opportunity.
CDMO , at these prices , many would be dissapointed with 1-2 years returns from here , and this is specially in the context of the smaller players who might have lot of capabilty but no capacity , yes the tailwinds are very strong
But without capacity there is an earnings ceiling , even if you are focus on the players who have both capacity and capability , not just one
I am saying this with rationality because we have played this theme with big winners over the last 3 years , and hence my opinions
Large are winning here now