UK GP 🩺 and long-term investor. Daily market dissections with dark humour 🔪 Built from £0, no inheritance, no leverage. Full portfolio public on eToro 👇
UK GP 🩺 First in my family to go to university, and the first to invest. Built from £0, no inheritance, no finance degree.
+25.6% this year. Risk score 4/10. No leverage, no shorting.
This is Scalpel to Stocks 🔪 Here's the whole story 👇
By day I'm a GP. By 6am I'm reading earnings reports with a coffee, because it turns out the skills overlap more than you'd think. Take a history, look for the red flags, ignore the noise, and never panic in front of the patient.
I didn't start well. In 2022-23 I day traded, which is a bit like treating yourself with whatever's in the medicine cabinet. Lots of activity, very little healing. 🎢 I stopped, and rebuilt everything around one boring, brilliant idea: buy good businesses and leave them alone long enough for compounding to do the heavy lifting.
Where it stands today, straight from my eToro profile:
📈 +25.6% so far in 2026, +27.3% over the last 12 months
🛡️ Risk score 4 out of 10, and it hasn't gone above 4 all year
✅ 69% of trades profitable, two thirds of months in the green
📉 Worst dip this year: about 9%
🗓️ Active every single week
Every position is public. The winners, and the ones that have humbled me.
I'd rather show you the scars than pretend I don't have any.
If you want to see the full workings, the thesis behind each holding and the whole journey, it's all on my eToro profile:
https://t.co/JmAfKNfTWD
A bit more about Scalpel to Stocks:
https://t.co/NuXJYjWSOF
Not investment advice. Past performance is not a guide to future returns. 🙏
𝗦𝗖𝗔𝗟𝗣𝗘𝗟 𝗧𝗢 𝗦𝗧𝗢𝗖𝗞𝗦 🔪 | 𝗘𝗕𝗜𝗧𝗔: 𝗧𝗛𝗘 𝗟𝗜𝗧𝗧𝗟𝗘 𝗔𝗖𝗖𝗢𝗨𝗡𝗧𝗜𝗡𝗚 𝗡𝗨𝗠𝗕𝗘𝗥 𝗧𝗛𝗔𝗧 𝗪𝗔𝗡𝗧𝗦 𝗬𝗢𝗨 🕺💰
𝗘𝗕𝗜𝗧𝗔, 𝗘𝗕𝗜𝗧𝗔. 𝗘𝗕𝗜𝗧𝗔, 𝗘𝗕𝗜𝗧𝗔. 𝗘𝗕𝗜𝗧𝗔, 𝗘𝗕𝗜𝗧𝗔…Uh. Uh-huh, uh-huh.
Profit before interest, profit before tax,
Strip out the financing, then look at the facts!
Add back amortisation, let the earnings come through,
If you want to know the business, EBITA’s for you.
I sing!.....
𝗘𝗕𝗜𝗧𝗔, 𝗘𝗕𝗜𝗧𝗔. 𝗘𝗕𝗜𝗧𝗔, 𝗘𝗕𝗜𝗧𝗔…Yeah.
Today we are getting into one of those financial acronyms that sounds like something a junior accountant whispers into your ear at 2am. So lets do this!... 🥁
𝗘𝗕𝗜𝗧𝗔. Earnings Before Interest, Taxes and Amortisation.
Sexy? No. Useful? Hell YEAH! Come on!....
𝗦𝗢 𝗪𝗛𝗔𝗧 𝗧𝗛𝗘 𝗛𝗘𝗟𝗟 𝗜𝗦 𝗜𝗧? 🧮
EBITA starts with operating profit and adds back amortisation.
Amortization? Its not bringing things back from the dead, oh no.... This is the gradual reduction of a debt through scheduled payments or the systematic spreading of an intangible asset's cost over time. 😎 Can you dig it?!
In simple terms, it tries to show you how much profit the underlying business generates before you account for how it is financed, how much tax it pays and the accounting expense associated with amortising intangible assets. 🎸
Imagine two companies doing the same thing.
One has borrowed a Mount Rushmore of money, Abe Lincoln and all. 🎩
The other has barely borrowed anything.
Their bottom-line profits can look very different because interest expense sits below operating profit.
EBITA strips that financing decision down and out, down and out.....
𝗪𝗛𝗬 𝗡𝗢𝗧 𝗝𝗨𝗦𝗧 𝗨𝗦𝗘 𝗘𝗕𝗜𝗧𝗗𝗔? 🤨
One more letter makes all the change!
T, right between the I and D, I say T, right between the I and D...you see?
-EBITDA adds back depreciation AND amortisation. 💃
- EBITA adds back amortisation only. Say whaaa?! 😱
That distinction matters. Depreciation relates primarily to tangible ASSets 🍑 such as machinery, buildings and equipment.
Amortisation generally relates to intangible ASSets 💨 such as acquired customer relationships, patents, software and certain other intangible assets.
The criticism of EBITDA is that depreciation can represent a very real economic cost for businesses that constantly need to replace their physical ASSets. 🍈
If your factory needs replacing every ten years, telling investors “IGNORE THE DEPRECIATION, BABY” does not magically make the factory free. EBITA is therefore a slightly less aggressive adjustment.
HOWEVER....A company can have beautiful EBITA while simultaneously requiring enormous capital expenditure (CAPEX BABY, YEEEEAH!), carrying a mountain of debt or destroying shareholder value through terrible acquisitions.
This is why you never look at one metric in isolation.
𝗧𝗛𝗘 𝗩𝗔𝗟𝗨𝗔𝗧𝗜𝗢𝗡 𝗣𝗔𝗥𝗧 💰📈
EBITA becomes particularly useful when paired with an EV/EBITA multiple.
Enterprise Value represents the value of the entire operating business, including debt and subtracting cash.
Divide that by EBITA and you get a rough measure of how much investors are paying for each unit of operating earnings.
A company trading at 10× EBITA and one trading at 30× EBITA are telling you very different valuation stories.
If you liked that juicy McNugget drop a like, a follow and be prepared for more sing-a-longs to come. PEACE! 🎤 $MCD
EBITA, EBITA. Uh-huh. Now go read the accounts. 🙃
James | Scalpel to Stocks
Cutting through the noise. Finding the signal. Getting fat with the stacks. 💰
$NSDQ100 $SPX500 $DJ30
$NKE trades on a forward P/E of 20.98, with a PEG GuruFocus can't even calculate because earnings are shrinking.
$LULU trades on a forward P/E of 11.22 and a PEG of 0.37.
One's priced like a comeback story already happened, the other's priced like nobody's watching. Which is the actual bargain here?
My thesis and every holding, on eToro:
https://t.co/JmAfKNfTWD
More here:
https://t.co/NuXJYjWSOF
𝗦𝗰𝗮𝗹𝗽𝗲𝗹 𝘁𝗼 𝗦𝘁𝗼𝗰𝗸𝘀 🔪 | 𝗙𝗿𝗶𝗱𝗮𝘆 𝟮 𝗢𝗰𝘁𝗼𝗯𝗲𝗿: 𝗡𝗶𝗸𝗲 𝗛𝗮𝘀 𝗟𝗲𝗳𝘁 𝘁𝗵𝗲 𝗚𝘆𝗺 𝗮𝗻𝗱 𝗧𝗮𝗸𝗲𝗻 𝗨𝗽 𝗖𝗿𝘆𝗶𝗻𝗴 𝗜𝗻𝘁𝗼 𝗮 𝗣𝗶𝗹𝗹𝗼𝘄 👟💀
Good morning, Scalpels. Friday is here. Coffee is here, the jobs report is lurking in the bushes and Nike has just walked into the clinic looking like it has been chased here by a pack of wolves.
I was genuinely wondering whether $NKE could disappoint investors even further 🤣...
Nike reported fiscal Q1 revenue of $11.21bn, down 4%, missing the roughly $11.32bn consensus. EPS was actually a beat at $0.48, but nobody cared because the full-year outlook arrived carrying a flamethrower.
Nike now expects fiscal 2027 revenue to fall by a high-single-digit percentage and adjusted EPS of just $1.15-$1.35. The Street had been around $1.61. The stock fell as much as 6.6% after hours. 💀
𝗧𝗵𝗲 𝗛𝗮𝗮𝗹𝗮𝗻𝗱 𝗖𝗵𝗮𝗽𝘁𝗲𝗿 👟⚽️
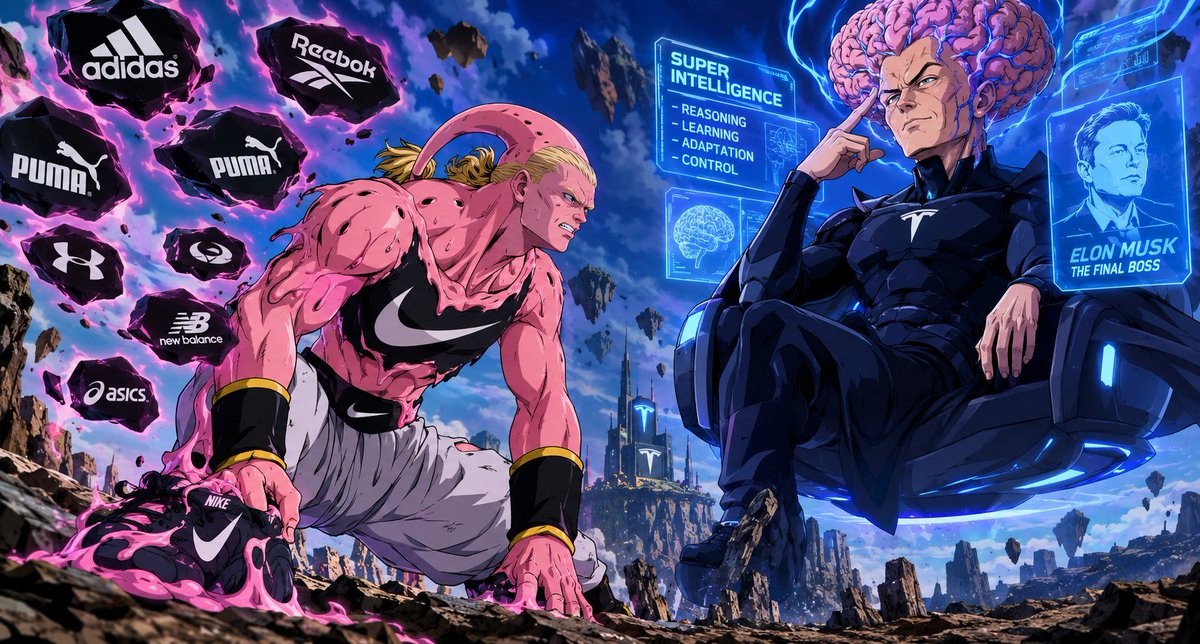
A man of memes, a man compared to Majin Buu himself, yet the man is associated with a brand that has mastered the ancient art of failing to impress.
Nike is repositioning Sportswear, Jordan and Greater China through “Pace”, a restructuring programme expected to deliver about $2.5bn of cumulative savings through fiscal 2031, with roughly $1bn of pre-tax charges and more job cuts.
China is the particularly ugly bit. Revenue fell 22% reported, or 26% currency-neutral. Converse fell 28%, Nike Brand footwear fell 6% and Digital fell 13%.
𝗧𝗵𝗲 𝗥𝗲𝗮𝗹 𝗣𝗿𝗼𝗯𝗹𝗲𝗺 🩻
A company can beat quarterly earnings and still deteriorate underneath. Revenue tells you whether customers are buying. Margins tell you what survives. Cash flow tells you whether profits become money. Guidance tells you what management thinks happens next.
Nike's gross margin improved to 42.8% and inventory fell 3% to $7.8bn.
𝗪𝗵𝘆 𝗜’𝗺 𝗪𝗮𝘁𝗰𝗵𝗶𝗻𝗴, 𝗡𝗼𝘁 𝗧𝗵𝗿𝗼𝘄𝗶𝗻𝗴 𝗠𝗼𝗻𝗲𝘆 𝗔𝘁 𝗜𝘁 🔪
Nike is exactly the sort of stock that tempts long-term investors into a trap.
“It's down 50%.” “Everyone hates it.” “The brand is iconic.” “Surely it can't go lower.”
Famous last words...A falling share price does not make a business cheap. It makes the business cheaper than it was.
The question is should be, “What does Nike have to become for today's price to be attractive?”
I want product momentum, improving China economics, healthier full-price selling and sustainable earnings growth. A famous logo is not a moat if consumers stop caring.
𝗧𝗵𝗲 𝗪𝗮𝗿𝗱 𝗥𝗼𝘂𝗻𝗱 🏥
Wall Street was comparatively calm yesterday, with the $SPX500 up 0.2% and $RTY up about 0.3%. $NSDQ100 and $DJ30 did not do much better.
The 10-year Treasury yield remains around 5.25%.
Brent is around $100 after September's roughly 14% gain, with Iran still hanging over supply. $OIL
$BTC remains around the low-$80Ks.
𝗧𝗵𝗲 𝟭𝟮:𝟯𝟬 𝗚𝗠𝗧 𝗠𝗼𝗺𝗲𝗻𝘁 💼
Today, the big one is employment. The September U.S. jobs report lands at 1:30pm UK time.
The market is looking for roughly 90,000 payroll gains and unemployment around 4.1%.
Strong jobs could reinforce higher-for-longer. Weak jobs could revive rate-cut hopes.
One number can move the market. It does not necessarily change the thesis.
𝗦𝗰𝗮𝗹𝗽𝗲𝗹 𝘁𝗼 𝗦𝘁𝗼𝗰𝗸𝘀 𝗔𝗰𝗮𝗱𝗲𝗺𝘆: 𝗧𝗵𝗲 𝗙𝗮𝗹𝗹𝗶𝗻𝗴 𝗞𝗻𝗶𝗳𝗲 𝗧𝗲𝘀𝘁 🔪📚
Never confuse a falling share price with a falling valuation.
If a company earns $5 per share and trades at $100, its P/E is 20. If the share price falls to $60 but earnings collapse to $2, the P/E is now 30.
Congratulations, you bought the dip and somehow made the valuation more expensive.
𝗧𝗵𝗲 𝗪𝗵𝘆 𝗦𝗰𝗮𝗹𝗽𝗲𝗹 𝘁𝗼 𝗦𝘁𝗼𝗰𝗸𝘀? 🔪
I don't want a portfolio of companies that merely look cheap. I want businesses capable of compounding over 10–20 years.
Sometimes it means watching an “obvious” bargain fall through the floor and resisting the urge to catch it with your face.
Cutting through the noise. Finding the signal. Getting fat with the stacks. 💰
James | Scalpel to Stocks
@CatLadyCapital I usually put 1k in a month but am keeping back as most the internet is screaming re a crash. High yields, rate hikes, war...its all a bit dicey.