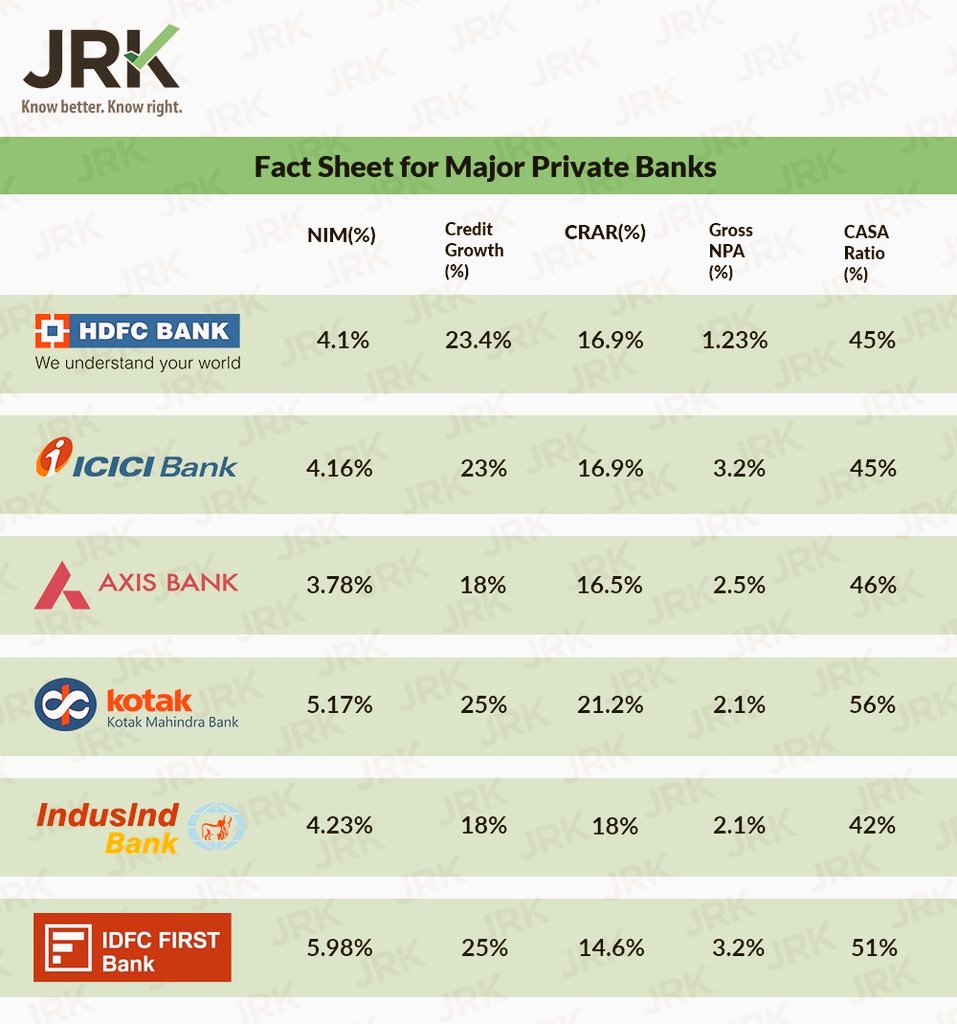
#HDFCBANK Q3: PAT UP 18.5% at ₹12259 Cr & NII UP 24.6% at ₹22988 Cr YoY
Asset Quality Stable: Gross NPA 1.23% vs 1.23% & NIM also Steady at 4.1% QoQ
Deposits Growth 19.9% & Credit Growth 19.5%
TTM P/E 21x (10 Yr Median PE 25.7x) & P/Bv 3.3x (10 Yr Median P/Bv 4.4x)
ROE: 16%
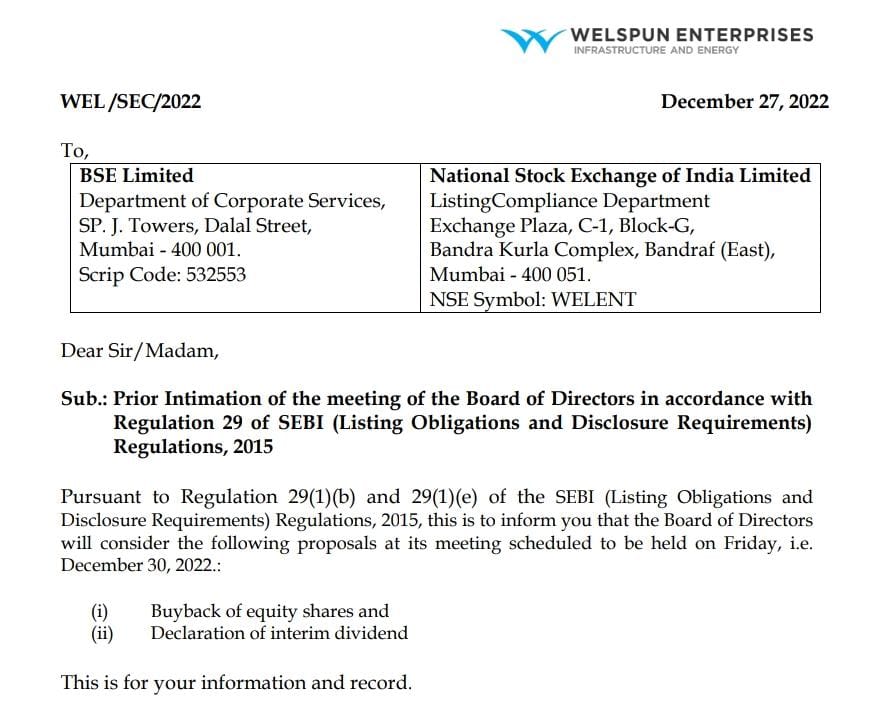
KTAs from #Welspun Enterprise "Asset Monetization Concall"
- Divestment Done: 5 HAM & 1 BOT
completed Highway Projects portfolio to Actis.
- Total Consideration: ₹ 2700 Cr (Approx ₹2200 Cr received & ₹500 Cr to be received by Mar'23)
1/n
KTAs from #Welspun Enterprise "Asset Monetization Concall"
- Divestment Done: 5 HAM & 1 BOT
completed Highway Projects portfolio to Actis.
- Total Consideration: ₹ 2700 Cr (Approx ₹2200 Cr received & ₹500 Cr to be received by Mar'23)
1/n
4) Welspun has Equity commitment in one of its HAM project approx ₹ 225 Cr.
5) So roughly total outflow would be (630 + 40 + 40 + 225) ₹935 Cr.
6) So Net Cash Left in Books will be approx ₹1300+ Cr immediately + ₹500 Cr later on.
3/n
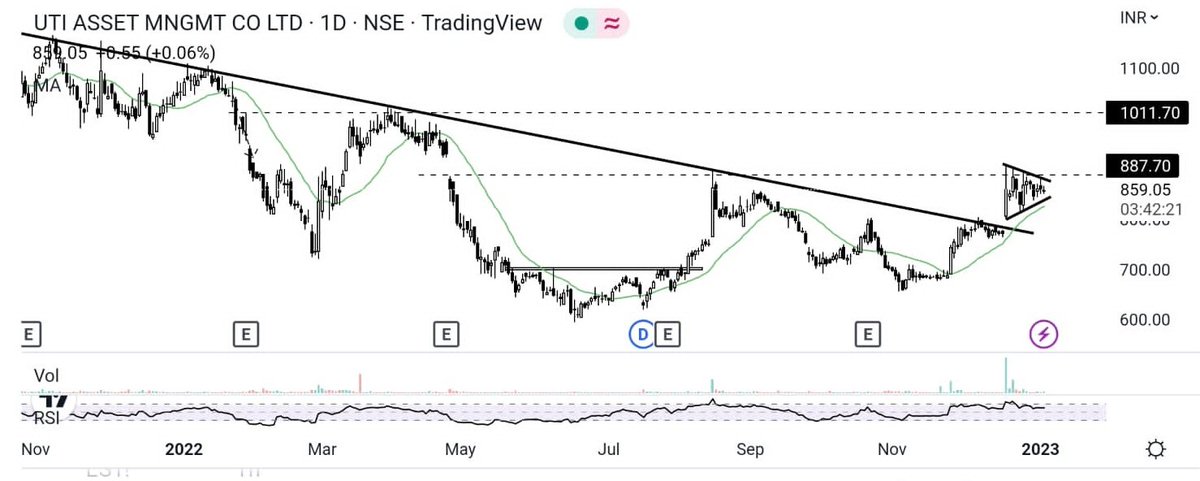
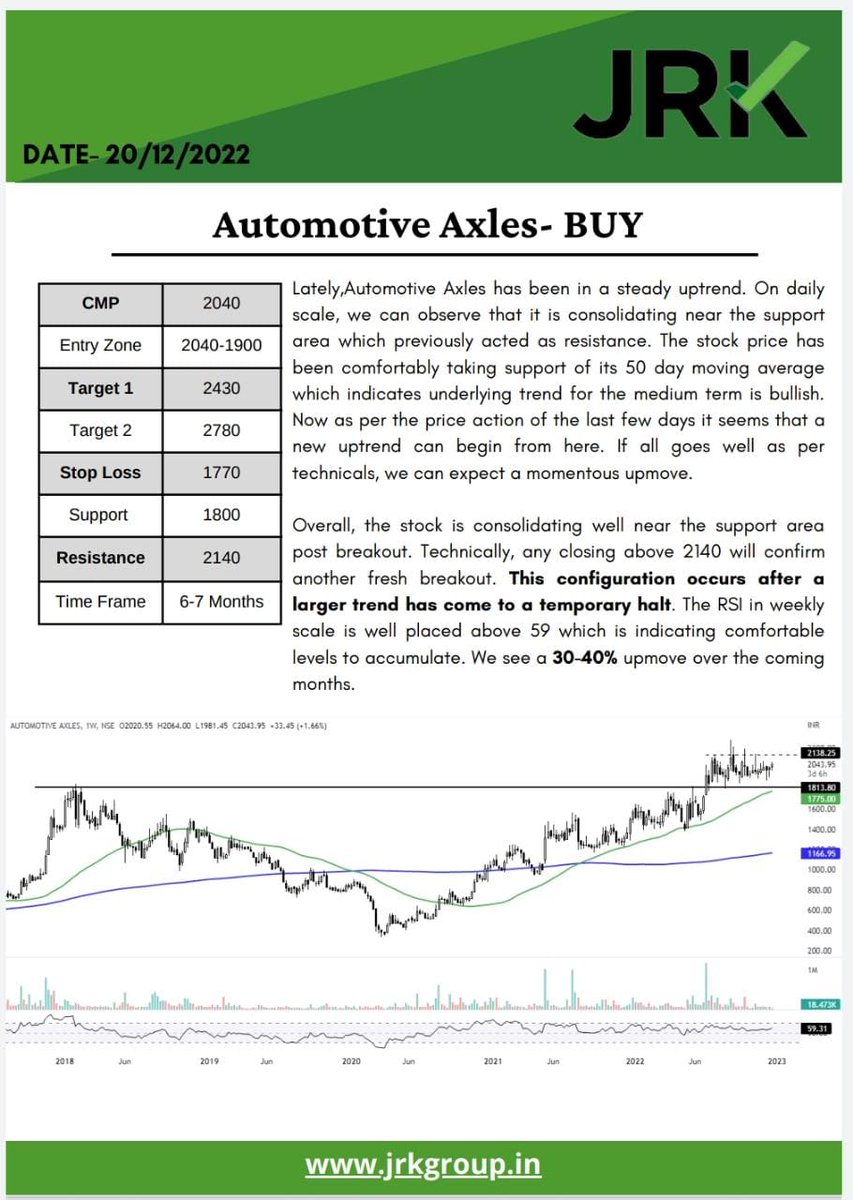
Technical Report #AutomotiveAxles
Consolidating post breakout - This configuration occurs after a
larger trend has come to a temporary halt.
If all goes as per Technicals, we can expect a momentous upmove.
Research Analyst @Chart__Guru /
JRK Research Team
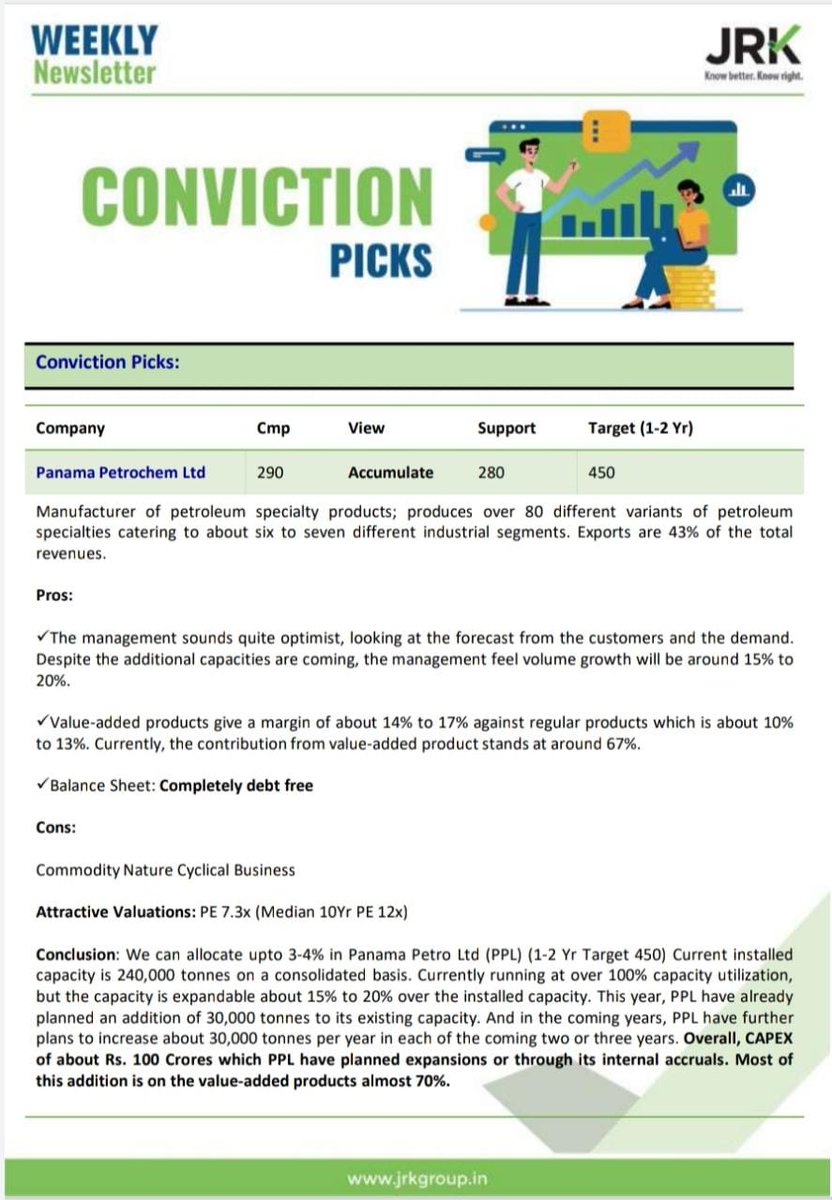
Our Conviction Pick: Panama Petro (Cmp 290) shared in our Weekly Report.
Disclaimer: Please Check our Research Analyst Disclosures & Investor Charter in our Website https://t.co/XY4hLEMBqp
#DeepIndustries
Extract from JRK's Interaction with the management in the Q2 Concall..
Mgt guided Q3 will be better than Q2 & Q4 will be better than Q3.
We have recommended Deep Industries in our Muhurat Picks 2022, our conviction remains same.
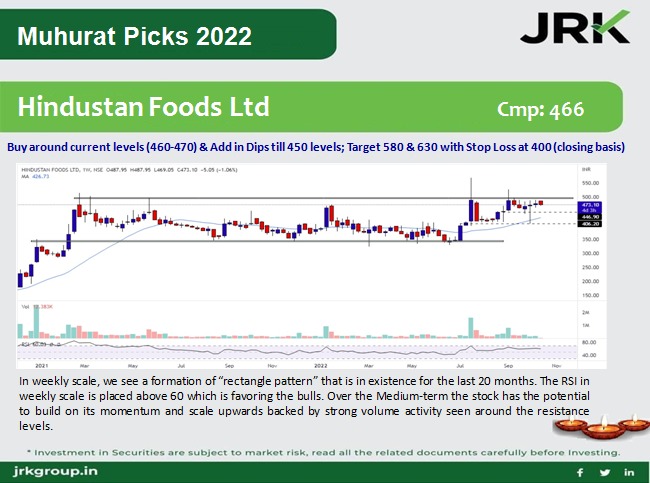
JRK Muhurat 2022 Technical Pick 2: #HindustanFoods
Buy around current levels (460-470) & Add in Dips till 450 levels; Target 580 & 630 with Stop Loss at 400 (closing basis)
#Panama Petrochem Q2
PAT at ₹ 67.4 Cr (+9% YoY & +4.4% QoQ) & Revenue at ₹ 614 Cr (+9% YoY & +11% QoQ)
EBITDA Margin at 14.43% vs 15.65% (QoQ)
P/E 7.5x & MCap to Sales 0.8x with Positive OCF & almost Debt Free
Declared Interim dividend of ₹ 3
Our Conviction Pick: Panama Petro (Cmp 290) shared in our Weekly Report.
Disclaimer: Please Check our Research Analyst Disclosures & Investor Charter in our Website https://t.co/XY4hLEMBqp
JRK Muhurat 2022 Technical Pick 5: #Avantel Ltd
Buy around current levels (300-310) & Add in Dips till 280 levels; Target 410 & 470 with Stop Loss at 240 (closing basis)
Cash Flow from Operations ₹ 42.6 Cr (6M FY23). Company invested most of its Free Cash Flows in MFs, Bonds & other financial Instruments ~ ₹ 30 Cr
Overall Good numbers but near-term upside limited due to high valuations. Long-term growth drivers / prospects intact.
#MAPMYINDIA
#MAPMYINDIA Q2
PAT at ₹ 25.4 Cr (Flat YoY & +5% QoQ) & Revenue at ₹ 76.3 Cr (+34.6% YoY & +17.4% QoQ)
Operating Margins declines: EBITDA at 40% vs 46% (QoQ)
1/3
Reasons behind Margin decline:
Increased Marketing Spends for brand building (for new client acquisition)
Higher Project & field suvey expenses (for new use case adoption)
Valuations: PE 80x & MCap to Sales 30x (Median MCap to Sales is 49x since listing)
#MAPMYINDIA
2/3