@CristianoVelos9@BssSpark With the ever-ailing fertilizer operation, undoubtedly the creditors will want their “pound of flesh” via some form of an equity stake in Magnes to clear a regulatory pathway for spin out. Could be a win-win to get Verde out from under untenable debt burden.
@MidnightNtwrk The average joe mostly opted out of privacy concerns but the bots are closing in - this digital passivity or laziness won’t continue to work. Midnight is skating to where the puck will be and appears to offer a very smart solution.
@verdeagritech The fertilizer operation has been in zombie mode for a number of years so these results are expected…more importantly the rare earth tone shifted ultra conservative all of a sudden.
@CristianoVelos9 Less AI generated slop…more drilling news. What’s with the crazy long delays between drilling updates!? It’s definitely unnerving retail investors. Meanwhile…Aclara hits an all time high this morning. Viridis just about near its all time highs.
@CristianoVelos9 AI bot takeover of your account? What’s with the AI generated 25 post slop? Cogent human articulated posts still add far more value on this forum and they carry more weight for discerning readers and investors. Food for thought!
@CristianoVelos9 The Brazilian Ag crisis is not improving anytime soon. Is the biofuel carbon avoidance market (especially for those pursuing BECCS credits) a viable solution for Verde, along with ERW monetization: https://t.co/Ue52KS62U1
@CristianoVelos9 Congrats Cris- excellent news! An investor cc in Q1 would be very helpful: investors need clarity on how ERW becomes profitable given glauconite’s delivery economics, MRV costs & farmer adoption. A simple walkthrough of unit economics + path to margin would be most appreciated!
@mschwartz_f@CristianoVelos9 The Verde project is too early stage to be able to translate imo. They will require a pilot plant to prove up consistently high recovery rates commensurate or better than Brazilian peers like Aclara, Meteoric, Viridis and https://t.co/uUBrN3Bmoa. This means about two year wait.
@CristianoVelos9 Verde runs negative cash flow while Brazil Potash presells 90% of production - a perfect case study in systemic misalignment. Policy, farm credit, and distributor incentives all protect legacy potash, not sustainable innovation.
@CristianoVelos9 Projects like Terradot’s Sentinel - soil to stream research site - raise the bar on ERW scientific rigor, surpassing even Isometric’s demanding standards. Can Verde’s glauconite be proven to be as good or better at sequestering carbon than basalt? https://t.co/k8NTxMgQLi
@CristianoVelos9 Interesting development with more advanced Viridis. They are leapfrogging pilot and going straight to demonstration plant in order to de-risk scale up challenges. Also using a “pro-Western”strategy of procurement and business alignment: https://t.co/ERIwBJ03R7
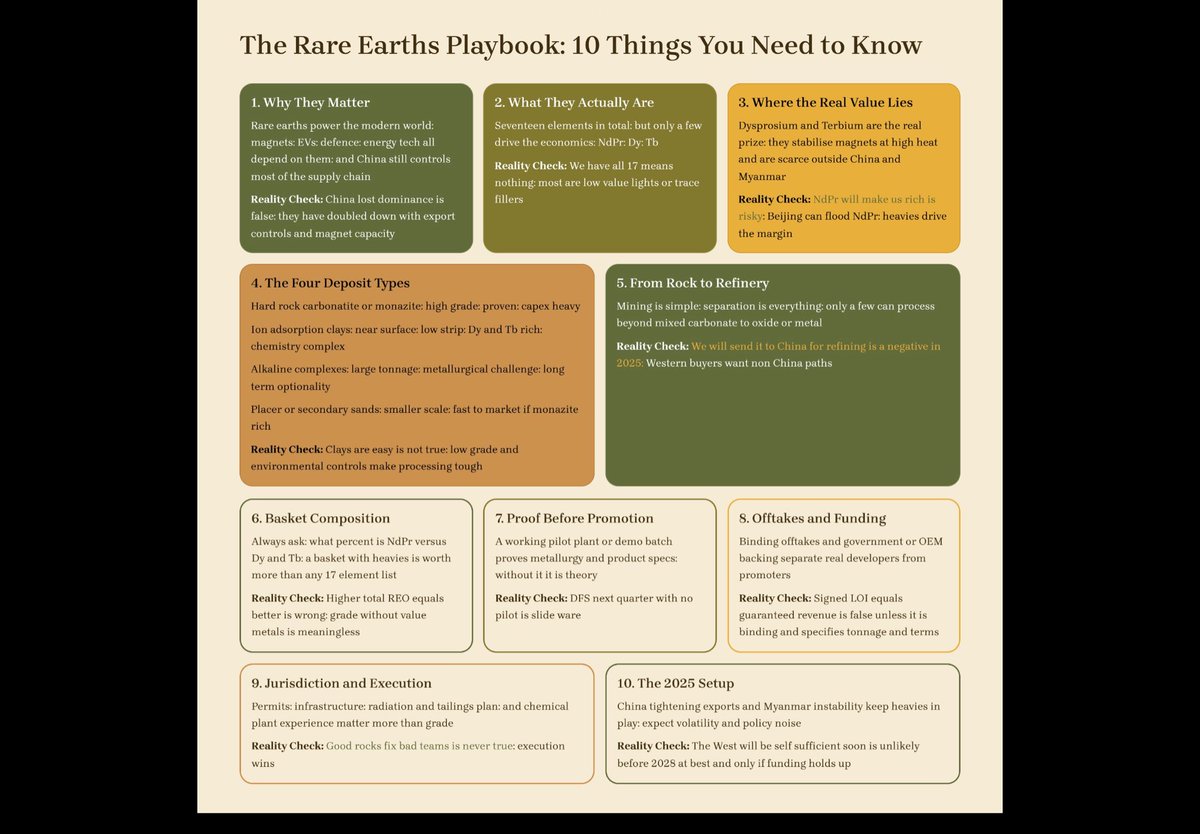
@CristianoVelos9 Here’s a concise picture of what separates the REE men from the boys. If Verde is able to prove its mettle, so to speak, then it could be game on but there are a LOT of reality checks. My favorite: DFS is slide ware, bring on the pilot plant or demo batch.
@CristianoVelos9 Cris clearly the market is moving toward Verde’s solution. Puro is readying its updated methodology for release, which will include glauconite for weathering. Is Verde going to offer published results in the near term to confirm it’s as good or better than basalt and olivine?
@CristianoVelos9 Geopolitical risks are rising. Have you run your model for the potential of the Strait of Hormuz being shut down if Iran is attacked again (a strong possibility)? How could this impact oil/potash prices, trade flows, freight/ins.prices? This threat is as real as other outliers.
@PauloMacro The fact so many agree with this would suggest the opposite setup ; however, I agree…mostly due to a ramping M.E. destabilization plan likely coming down the pike into year end. Hope I’m wrong though…