Investment Portfolio Manager with 12+ years in global markets. Specializing in asset allocation, risk management, and data-driven investment strategies.
Energy vs. tech could be today's battle.
Oil is helping energy.
Higher inflation expectations are hurting rate-sensitive growth.
If this divergence continues, sector rotation could become the real story of the day.
#SectorRotation#Energy#TechStocks#Oil#Nasdaq#Trading
Here’s what would make me more bullish today:
Nasdaq futures recover.
NVDA stabilizes.
Semiconductors stop bleeding.
Treasury yields cool off.
Market breadth improves.
If we get that combination, the morning weakness could turn into another buy-the-dip setup.
#StockMarket
One of the biggest mistakes today would be thinking:
“NVDA is up, so everything AI is automatically a buy.”
Nope.
I want confirmation.
Follow-through matters more than the first premarket spike.
#NVDA#AIStocks#StockMarket
The AI trade is getting more sophisticated.
The market isn't just asking “Who uses AI?”
It's asking “Who actually makes money because of AI?”
That's a very different question.
#NVDA#AIStocks#StockMarket
Western Digital (WDC) shares dropped 14–18.5% and Sandisk (SNDK) fell 9–11% in early trading after both reported better-than-expected quarterly results and revenue forecasts tied to AI demand. Investors viewed the guidance as failing to meet elevated expectations after massive year-to-date gains.
$AMD didn’t just beat Q2—it gave AI bulls the number they needed.
• Revenue: $11.54B vs. $11.31B expected
• EPS: $1.66 vs. $1.61 expected
• Data Center: $6.7B, up 107% YoY
• Gross margin: 56%, in line
Q3 guidance:
• Revenue: $13.0B vs. $12.5B expected
• Gross margin: 56%, in line
The headline beat was solid. The real story was Data Center revenue more than doubling while management guided another major step-up next quarter.
That’s how $AMD keeps moving away from the “PC chip company” label and earns a higher AI infrastructure multiple.
The catch: $AMD rallied more than 8% before the report, so expectations were already running hot. A strong print doesn’t automatically guarantee a clean continuation.
The next signal comes from the reaction. If buyers defend the post-earnings move instead of selling the news, the market is likely pricing in a broader AI accelerator cycle—not just another good quarter.
$NVDA remains the leader, but $AMD is making it harder for investors to ignore the second lane.
#AMD #AIStocks #Semiconductors #DataCenters #Earnings
Wall Street closed in full risk-on mode—and $SPCX gave the bulls one more reason to stay aggressive.
The closing tape:
• Nasdaq +2.69%
• S&P 500 +1.90%
• Dow +1.88%
• Semiconductors gained nearly 7%
Falling oil prices and lower Treasury yields removed some of the macro pressure, while strong AI-linked earnings pulled capital back into software, chips, and infrastructure names.
Then came $SPCX’s first public earnings print:
• Revenue: $7.8B vs. $6.8B expected
• Adjusted EBITDA: $3.5B vs. $2.1B expected
• Shares: +3% after hours to roughly $129
That’s a serious beat—but the reaction matters.
$SPCX had already rallied more than 8% during the regular session, so a smaller after-hours move suggests part of the upside was priced in. The market will now focus on Starlink growth, AI spending, capital intensity, and whether buyers can absorb the upcoming lockup-related supply.
My read: risk appetite is back, but tomorrow is about follow-through. Strong stocks need to hold their gains once the opening excitement fades.
I’m mapping the next setups now. My private watchlist is available through the WhatsApp link in my profile.
#SPCX #SpaceStocks #StockMarket #AIStocks #Semiconductors #Earnings
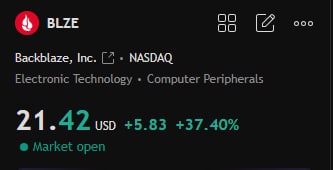
$BLZE +37.40%.
By the time the breakout started showing up across everyone’s timeline, the trade was already extended.
The setup had been on my group’s watchlist beforehand—with the entry, risk, and invalidation mapped out before momentum took over.
That’s the part traders often miss.
The edge isn’t predicting every candle or chasing the biggest green bar. It’s knowing exactly what you’re looking for before the move becomes obvious.
Not every setup works, and no one catches every runner. Preparation is the part we can control.
I’m building tomorrow’s watchlist now, focused on several high-volatility names where positioning appears to be shifting.
If you want to see the setups, use the WhatsApp link in my profile and send “6.”
That’s where I share the levels I’m watching—and what would make me walk away—before the trade gets crowded.
#BLZE #MomentumTrading #StockMarket #GrowthStocks #Trading
I share full trade details only inside my private group
The complete breakdown on this name is already out there
I won’t post the full ticker here:
$B***
This is a high-volatility setup.
Potential intraday range: 10%–40%.
Inside the group, I provide:
• Entry ranges
• Exact stop levels
• Real-time exits
👉 That’s the edge
If this goes public,
the first-mover advantage is gone.
If you want to stay ahead,
follow me.
#Stocks #Trading #USStocks #Investing
@rubideseo05 Sorry to hear that. Don’t try to win it all back in one trade—that usually makes things worse
I share the setups, entry zones, and risk levels I’m watching in my private WhatsApp group. The link is in my profile if you want to follow along
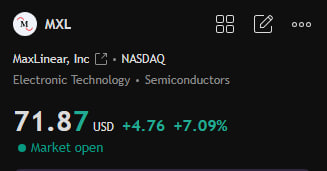
Yesterday’s $MXL call didn’t need long to age well.
After the stock got hit 21%, I said the selloff looked more like a positioning reset after a 166% run—not a breakdown in the AI infrastructure story.
Today, $MXL is up more than 7%.
The call wasn’t based on hoping for a bounce:
• Q2 revenue grew 55%
• Infrastructure revenue jumped 145%
• Q3 guidance came in at $210M–$220M versus the Street near $174M
• The 2026 optical data-center outlook was raised to $210M–$230M
Yesterday’s setup identified $64–65 as support and $64.50–66.50 as the buy zone. Today’s move is starting to validate that read.
Now $72 is the level that matters. A clean breakout with volume could reopen the path toward $82.
Anyone can explain a rally after it happens. The real edge is recognizing when the market has repriced a strong growth story too aggressively—and laying out the levels before the move.
I posted the setup before the bounce. I’m tracking the next one in my private watchlist. WhatsApp link is in my profile.
#MXL #Semiconductors #AIInfrastructure #ChipStocks
$MXL gave traders a clean lesson in expectations.
Q2 revenue grew 55% to $168.8M. Infrastructure revenue jumped 145%. Adjusted EPS came in at $0.35, while Q3 revenue guidance of $210M–$220M crushed the Street’s $174M estimate.
The stock still dropped 21%.
That wasn’t a broken quarter. It was a positioning reset after the shares had already run 166% following Q1.
The story has changed.
$MXL is no longer being valued as a legacy broadband recovery. The thesis now runs through Keystone, its 800G PAM4 platform, and whether the upcoming 1.6T products can turn the current ramp into a durable optical franchise.
Management raised its 2026 optical data center revenue outlook from $150M–$170M to $210M–$230M. That’s real execution.
The catch:
Most of the increase is still coming from Keystone. The newer platforms remain in qualification, operating cash flow was only $4.8M, and the unresolved $SIMO arbitration remains an overhang.
I like the business transition. I’m more selective on the stock after a 261% YTD move.
The setup:
• Support: $64–$65
• Breakout: Above $72 on volume
• Buy zone:?
• Stop: Below $61.50
A clean break above $72 would improve the short-term structure and put the larger $82 resistance zone back in play.
$MXL is no longer an early AI discovery trade. From here, the next rerating has to come from broader product adoption, margin expansion and stronger cash flow.
I’m watching the $65 reaction and the next 1.6T customer updates. The private-group WhatsApp link is in my profile.
#Semiconductors #AIInfrastructure #OpticalNetworking
I share full trade details only inside my private group
The complete breakdown on this name is already out there
I won’t post the full ticker here:
$B***
This is a high-volatility setup.
Potential intraday range: 10%–40%.
Inside the group, I provide:
• Entry ranges
• Exact stop levels
• Real-time exits
👉 That’s the edge
If this goes public,
the first-mover advantage is gone.
If you want to stay ahead,
follow me.
#Stocks #Trading #USStocks #Investing
$VECO has already gone through a full valuation reset—from nearly $80 in June to about $51 now. That makes tomorrow’s report more interesting, not safer.
The company is starting to trade less like a legacy MOCVD vendor and more like a niche process-equipment play on AI scaling.
Its laser annealing tools are already qualified at three Tier-1 logic customers and one HBM DRAM customer. Two IBD300 systems are under evaluation at HBM customers, while June’s follow-on NSA500 order suggests evaluations are starting to turn into production demand.
The numbers still need to catch up.
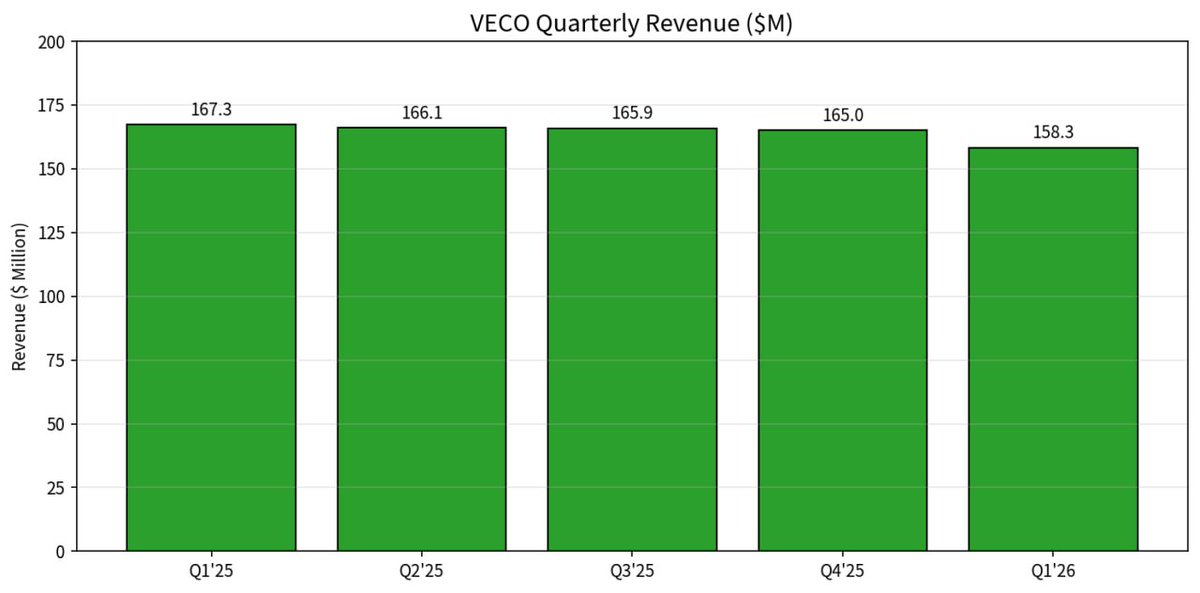
Q1 revenue fell 5% to $158.3M, and adjusted gross margin slipped to 36.2%. Management kept FY26 revenue guidance at $740–800M, but tomorrow’s report needs to confirm the second-half ramp.
There’s also the pending $ACLS merger—0.3575 $ACLS shares for each $VECO share—with China approval still outstanding.
The setup:
• Support: $48–50
• Breakout: Above $56 on volume
• Buy zone: ?
• Stop: Below $46
I like the rerating thesis, but this is a post-earnings confirmation trade—not a blind bet into the print.
I’m tracking the reaction in my private semiconductor watchlist. WhatsApp link is in my profile.
#Semiconductors #AIInfrastructure #HBM #ChipStocks
$ON is showing where AI money is rotating next: beyond GPUs and into the power tree.
Q2 came in slightly ahead. Q3 guidance topped expectations. Management now expects AI data center revenue to more than double in 2026.
The stock is up roughly 7.5% premarket.
That keeps $MPWR, $VRT and $ETN on my radar. Every new AI rack needs power conversion, cooling and electrical infrastructure before it produces a single token.
The trade isn’t simply “AI is hot.” The trade is finding the next bottleneck.
I’m adding the strongest read-through names to my private watchlist. WhatsApp link is in my profile.
#Semiconductors #DataCenters #AIInfrastructure #Onsemi
$PLTR’s AIP Bootcamps are doing what every enterprise software company wants: shortening the path from demo to deployment—and then expansion.
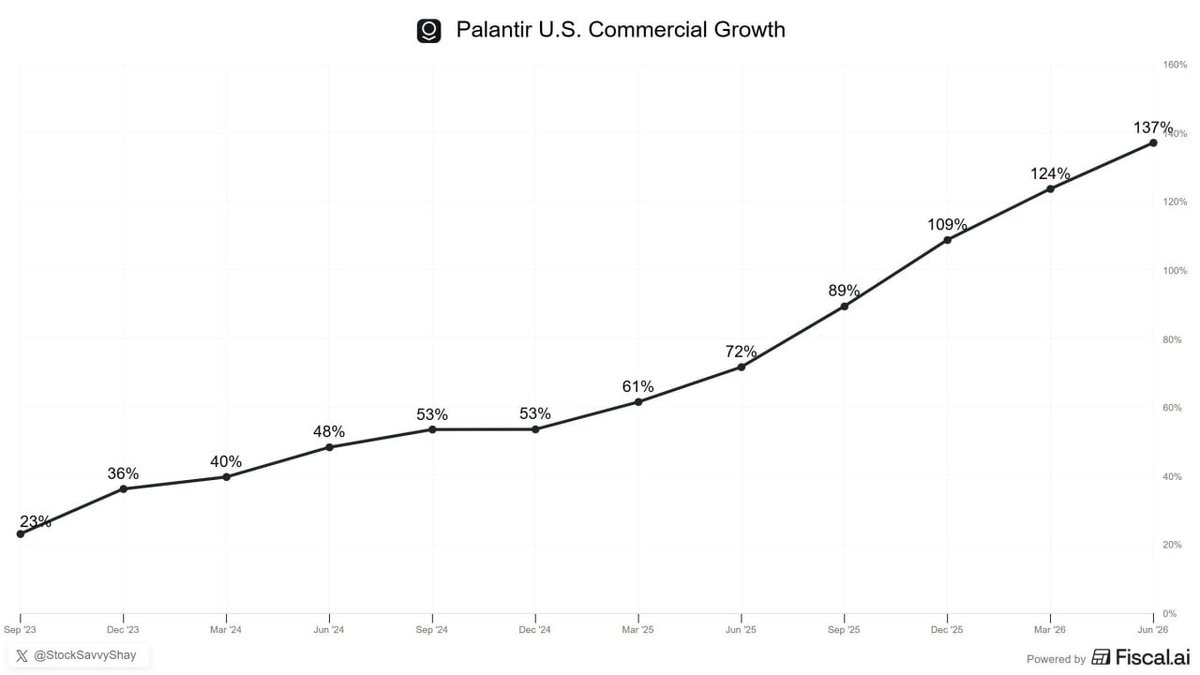
U.S. commercial revenue growth:
• Q4: 137%
• Q1: 133%
• Q2: 149%
One brief slowdown, followed by another acceleration on a much larger revenue base.
That’s the real signal. Customers aren’t just testing AIP. They’re embedding Palantir deeper into their data, workflows and operating decisions.
The land-and-expand engine is working.
More post-earnings notes are in my private group—WhatsApp link in my profile.
#Palantir #EnterpriseAI #AIStocks
That wasn’t an earnings beat. $PLTR just reset the bar.
• Revenue: $1.94B vs. $1.81B — up 93% YoY
• Adjusted EPS: $0.41 vs. $0.35
• U.S. commercial revenue: $764M — up 149%
• U.S. commercial RDV: $6.2B — up 124%
FY26 guidance:
• Revenue: $8.15–$8.16B vs. $7.73B expected
• Adjusted operating income: roughly $4.9B vs. $4.5B expected
The real story is the combination: accelerating growth, expanding margins and stronger future revenue visibility.
That’s exactly what the bears didn’t want to see.
Now the question is whether buyers defend the earnings gap once the opening excitement fades. I’ll be tracking the setup in my private market notes—WhatsApp link is in my profile.
#Palantir #AIStocks #Earnings
$PLTR didn’t just triple its revenue. It nearly quadrupled it—and margins exploded at the same time.
Q2 2023:
• Revenue: $533M
• Adjusted operating margin: 25%
Q2 2026:
• Revenue: $1.94B
• Adjusted operating margin: 62%
That’s 3.6x the revenue in three years while operating margins more than doubled.
The valuation is still demanding, but this is why $PLTR keeps commanding a premium: it isn’t choosing between growth and efficiency. It’s delivering both.
#Palantir #AIStocks #Earnings
That wasn’t an earnings beat. $PLTR just reset the bar.
• Revenue: $1.94B vs. $1.81B — up 93% YoY
• Adjusted EPS: $0.41 vs. $0.35
• U.S. commercial revenue: $764M — up 149%
• U.S. commercial RDV: $6.2B — up 124%
FY26 guidance:
• Revenue: $8.15–$8.16B vs. $7.73B expected
• Adjusted operating income: roughly $4.9B vs. $4.5B expected
The real story is the combination: accelerating growth, expanding margins and stronger future revenue visibility.
That’s exactly what the bears didn’t want to see.
Now the question is whether buyers defend the earnings gap once the opening excitement fades. I’ll be tracking the setup in my private market notes—WhatsApp link is in my profile.
#Palantir #AIStocks #Earnings
Today wasn’t just a relief rally. It was a reminder that when risk comes back on, institutions still reach for mega-cap AI first.
Nasdaq: +2.1%
S&P 500: +1.5%
Dow: +1.3%
$GOOGL jumped nearly 5% and passed $AAPL to become the world’s second-largest company.
$AMZN gained 5.3%, hit a record high and joined the $3 trillion club.
$NVDA added nearly 3% and climbed back above $5 trillion.
Falling oil helped the entire market, but the real signal was concentration: capital moved straight into companies with scale, infrastructure and a credible path to monetize AI.
Now we see whether the rally broadens—or stays crowded at the top.
#StockMarket #AIStocks #BigTech
I can see a path where $TSLA eventually reaches a $10.27 trillion market cap—but not as a car company.
The bull case depends on Tesla becoming several businesses at once:
• Robotaxi turns the vehicle fleet into a high-margin transportation network
• Optimus becomes a physical labor platform, backed by a scalable AI and software stack
• Energy grows into a major grid infrastructure business
• Manufacturing expertise becomes a platform Tesla can license or monetize
• Software adds recurring revenue across the entire ecosystem
This isn’t a near-term target or the base case.
It requires autonomy to work at scale, regulators to approve it and robots to become commercially useful.
The path to $10.27T isn’t about selling more cars.
It’s about proving Tesla can own multiple platforms built around intelligence, labor and energy.
#Tesla #Robotaxi #AI
$PLTR is expected to post its first $1B adjusted operating income quarter today—just one year after reporting its first $1B revenue quarter.
That’s a remarkable operating leverage story.
Management guided for $1.797B–$1.801B in revenue and $1.063B–$1.067B in adjusted operating income, implying a margin near 59%.
This is also why I think the threat from OpenAI and Anthropic is overstated.
They build foundation models.
Palantir connects those models to enterprise data, permissions, workflows and real-world decisions. It isn’t trying to win the model layer. It’s building the control layer companies use to deploy AI inside actual operations.
The competitive risk becomes more serious if model providers move deeper into enterprise deployment and start replacing AIP or Foundry. We’re not there yet.
The catch is expectations.
Wall Street is looking for roughly 81% revenue growth. A basic beat may not be enough. U.S. commercial growth and forward guidance will decide the reaction.
I’m tracking the report and post-earnings levels inside the private group. WhatsApp is linked in my profile.
#Palantir #AIStocks #Earnings
Alright, be honest—who bought $SPCX today ahead of its first public earnings report tomorrow? 👀
This isn’t a normal earnings trade.
Wall Street will be watching Starlink margins, Starship spending and how aggressively management plans to fund its AI ambitions.
Then comes the next risk: the first major post-IPO share unlock starts two days later.
So anyone holding through the call isn’t just trading the numbers. They’re trading guidance, valuation and a potential supply wave at the same time.
Who’s holding overnight—and who’s waiting for the reaction?
#SpaceX #Earnings