Prices have corrected by 12-13rs. Maharastra mills quoting 54-55rs/kg.
It should settle at these levels for a few more sessions, and then hopefully start marching upwards again 🤞🏼🤞🏼
#sugar
Import duty angle done. Now waiting for diversion restrictions towards ethanol
Uske baad kya?
In all probability sugar prices should not crack 52-54rs/kg (cmp65-70rs in different states), and eventually start marching towards 75rs+ after both news
#sugar
https://t.co/wiF4y8sQZZ
Import duty angle done. Now waiting for diversion restrictions towards ethanol
Uske baad kya?
In all probability sugar prices should not crack 52-54rs/kg (cmp65-70rs in different states), and eventually start marching towards 75rs+ after both news
#sugar
https://t.co/wiF4y8sQZZ
If import duty is reduced from 100% to say 0%, the time lag is going to be 3 months for imports to arrive India, and landed cost may also be in the range of 44-46rs.
If ethanol diversion is restricted, mills are happy to sell more sugar than ethanol.
https://t.co/u0nMcmUNrI
If import duty is reduced from 100% to say 0%, the time lag is going to be 3 months for imports to arrive India, and landed cost may also be in the range of 44-46rs.
If ethanol diversion is restricted, mills are happy to sell more sugar than ethanol.
https://t.co/u0nMcmUNrI
Sugar segment of sugar companies can report a strong 22-25% PBT margins if current sugar prices of 50rs/kg hold on
Keep tracking sugar prices (ex-mill) https://t.co/KknHWJGhKK
Super bull cycle in the making with tight sugar production supply, stable demand. Dont miss this space
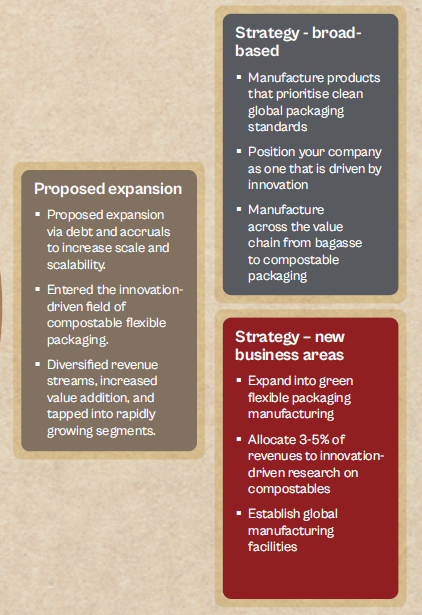
Some snippets from annual report of Pakka Ltd, which is planning a humungous capex of ~3500crs in the next 24-30 months.
Mgmt and board is AAA, the product offering is new age and disruptive and largely the intent is to DO BIG...
#Pakka
Sugar segment of sugar companies can report a strong 22-25% PBT margins if current sugar prices of 50rs/kg hold on
Keep tracking sugar prices (ex-mill) https://t.co/KknHWJGhKK
Super bull cycle in the making with tight sugar production supply, stable demand. Dont miss this space
The annual report is worth reading upon for someone who wants
- top class governance
- big capex plans (pass this Co if you think growing 20-40-100% volumes in 3-4 years is HUGE), this is much bigger story than this.
- Co doing the unconventional
Disc: invested, hence bias.
Some snippets from annual report of Pakka Ltd, which is planning a humungous capex of ~3500crs in the next 24-30 months.
Mgmt and board is AAA, the product offering is new age and disruptive and largely the intent is to DO BIG...
#Pakka