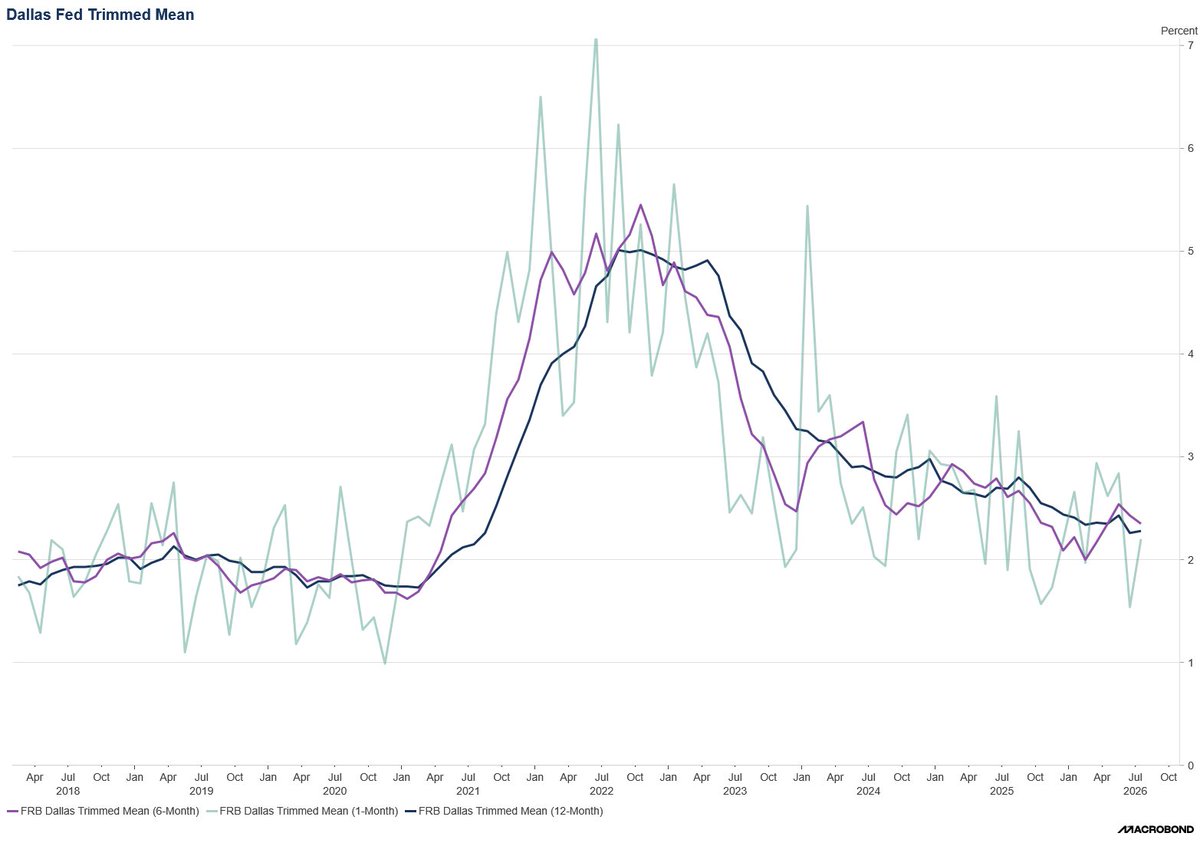
"Here is my standard: We must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do."
Imo, there is a lot of ambiguity in that and Warsh's favourite measure of underlying inflation is quite benign.
Market now pricing 2.5 hikes over the next 12 months following Warsh's hawkish sounds at Jackson Hole. We have been here before - Warsh sounds hawkish, market sells off, and so far he hasn't followed through. Is this time different?
For me, I don't think the Fed hike in . I continue to think Warsh doesn't want to hike, and he left the door open to not hiking with a suitably vague condition for tightening:
European growth resilient, driven by surprisingly strong consumption, but also supported by the massive German fiscal package undergoing.
Don’t let the short term noise distract from important long term themes.
Not necessarily a tradable signal (FX tends to move before surprise indices respond), but euro area economic data releases are again outperforming expectations by more than their US equivalents:
@NickTimiraos@JackFarley96 If he doesn’t then follow markets, markets will then start pricing him not doing anything and not pricing the data as he wants.
An issue Warsh will have with “being informed by markets” is that if he doesn’t start following them, markets will then stop pricing the data and start pricing him as an incredible Chair (incredible as in without credibility, if not obvious..). That will be messy.
This exemplifies the issue I think Warsh will have. He wants the task forces to give him cover to not raise rates, but his FOMC colleagues will see through that and he risks losing all credibility if he ignores that risk. Tough line to walk.
NEW: At dinner after day one of his first meeting as Fed chair, Kevin Warsh told his 18 colleagues he was launching five task forces to rethink how the Fed reads the economy.
Chris Waller asked what the point was. Name who's on them, he said, and I'll tell you what they'll say.
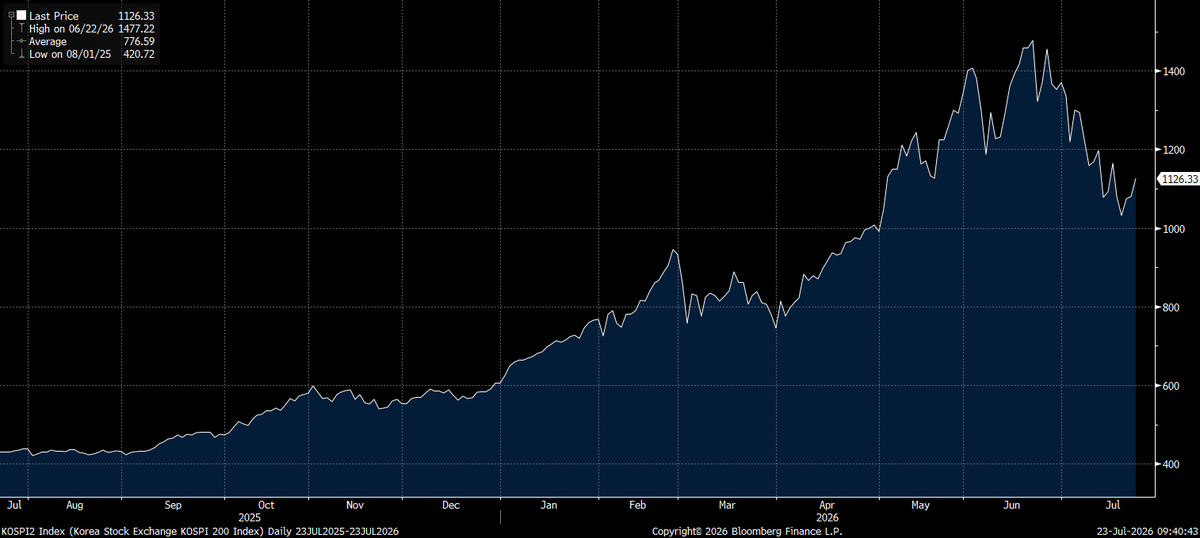
Korea is a big energy importer so it typically has a negative sensitivity to oil moves.
What it tells us is that the AI/Memory story was far more important for KRW that energy, and as the wind comes out of the KOPSI, it leaves people buying KRW to keep active exposures in line.
Interesting returns within EMFX as we see oil back around $100. High carry oil "winners" like COP and BRL make sense to be doing well. TRY hanging on in there. But if someone had told me oil moves from $70 to $100 and KRW was the 2nd best performer, I'd have said they were mad.
Does beg the question, why Mahmood? She is widely regarded as one of the best politicians of her time, and what she is known to be good at is 2 things: 1) communication, and 2) getting stuff done.
Ideal person to execute Burnham's quite radical devolution plans
Shabana Mahmood now seen as the front-runner for Chancellor. I had a lot of Qs yesterday about why the reaction in FX and not bonds? Simple answer is positioning, lots more people where short GBP than long Gilts.
Interesting piece from the BofA card data showing solid US consumer spending, and actually maybe a narrowing of the K shaped economy? That would certainly be a positive surprise
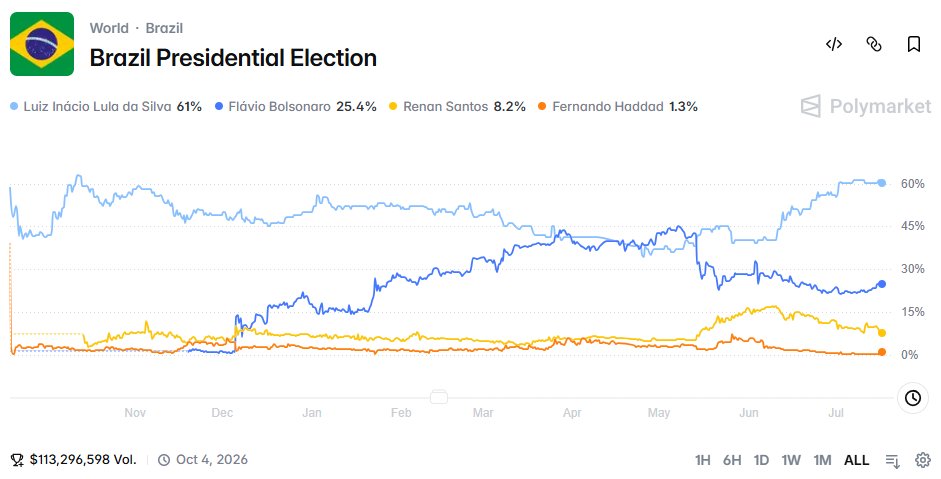
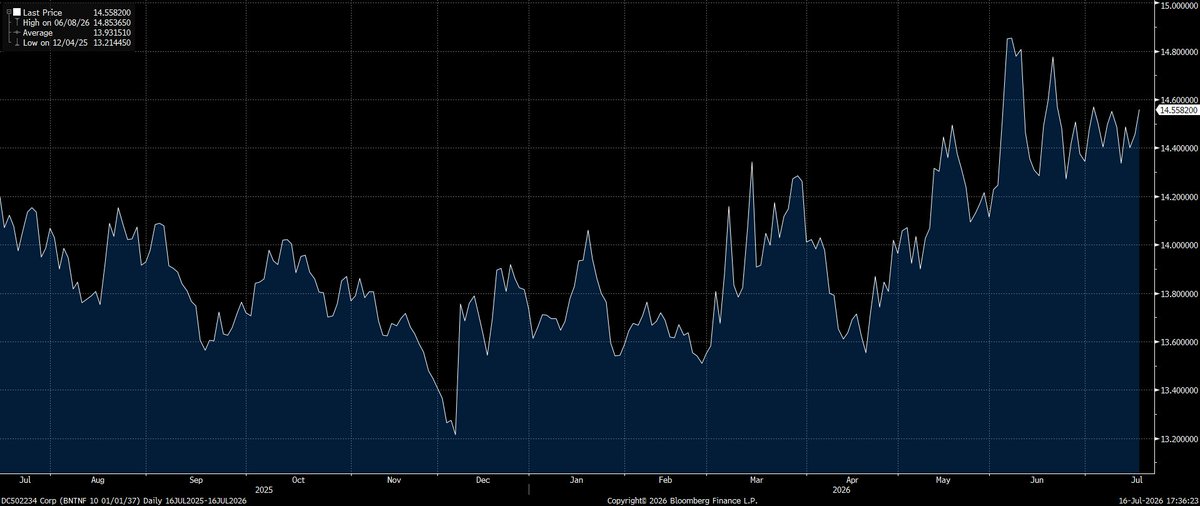
We have talked about Brazil before, but the latest market chat on Lula is that he is going to be more fiscally conservative than in previous administrations. So despite Lula remaining way out ahead in the polls, Brazilian yields have been stable
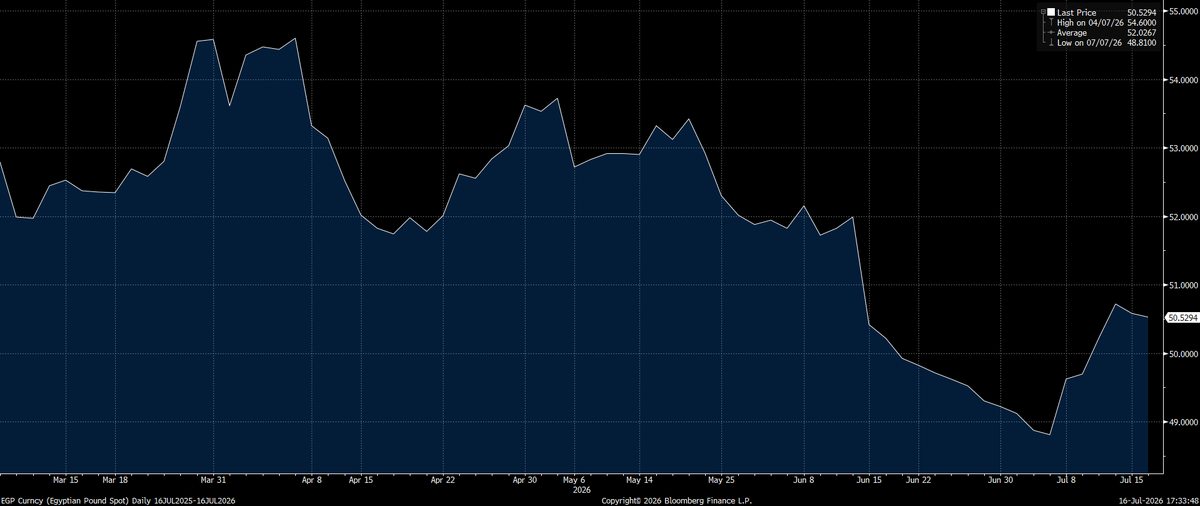
This is nirvana for investors seeking yield. Egypt offers t bill that pay 25%ish, but your risk is really the FX, however since the US/Iran conflict has settled down, EGP has actually strengthened. 25% annual carry + FX appreciation... yes please
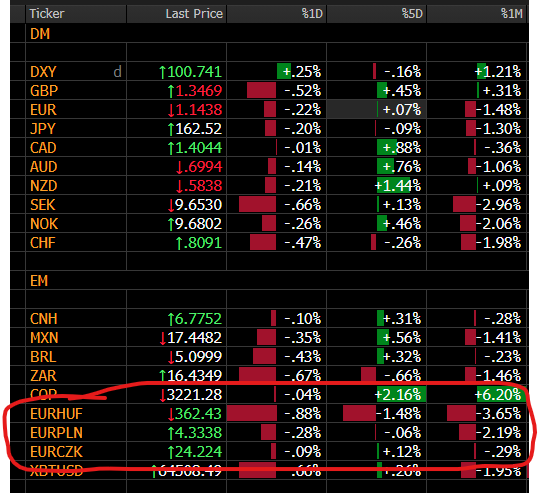
Tough month for HUF, underperforming CEE. I think its just a combo of central bank bias to ease, crowded positioning, and a lack of positive domestic news flow. We have the NBH next week, I expect them to introduce some more optionality going forward, which should support HUF.
The chance of a Fed rate hike at the July meeting has fallen to 12% (given the CPI data yesterday). Given the extent of the miss yesterday it should be 0%, but this is the new world where "every meeting is live"
It is weird we are seeing G10 carry names outperforming, USD in the middle, then EM weaker. The EM bit makes sense, but why G10 outperforming USD? Probably due to rate differentials as the other G10 central banks will hike if this persists, we are still not sure about the Fed
US/Iran conflict back as a theme in markets, will be interesting to see if: 1) the blockade goes ahead, 2) the US continues striking Iranian military targets, and 3) (the big one) when/how does Iran respond?
Markets for now are generally looking through this episode