There’s now over a 90% chance the Fed hikes today but if you read X over the last 24hrs you would think there’s a 90% chance the Fed doesn’t hike
Should be a very interesting afternoon
I'm actually looking forward to buying quality tickers from $NBIS to $WYFI to $NUAI to $SNDK to $AAOI (down over 60%) at increasingly better prices.
That's the silver lining of this "everything crash" continuing... getting more shares of the good stuff when the time's right.
As soon as $QQQ and $KOSPI (down almost 40%) show stability, I'll start highlighting entries again using our https://t.co/EhtZ5UZ4F4 indicator suite.
There's a time and place for everything.
Slow and steady wins the race.
$NBIS weekly chart BTW...
Holy shit, Sun owns 88,888 ($3.5M) shares of $WYFI. 🐋
Appreciate the transparency.
The $META news clearly shows that neoclouds have further room to grow. We’re already seeing $CRWV, $NBIS, and $IREN pumping on the news.
Long neoclouds!
It doesn’t matter if you’re team $NBIS or team $IREN, or invested in other solid picks like $CIFR, $CRWV, etc.
We’ll all win in the end…
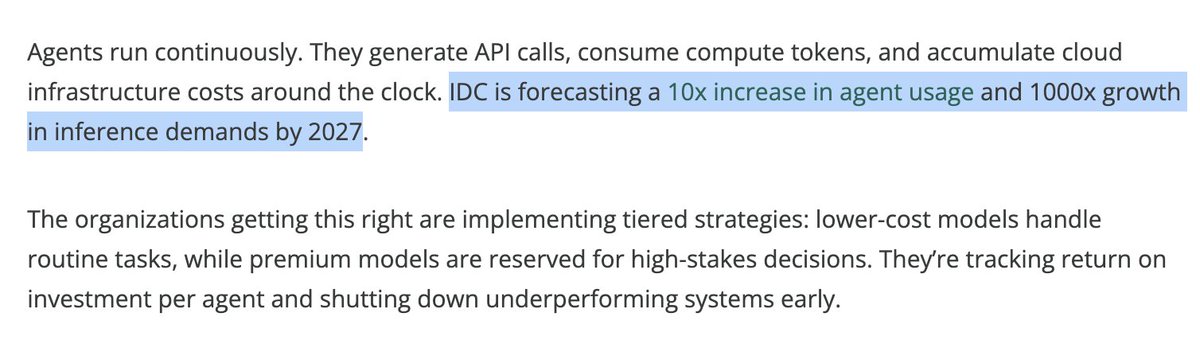
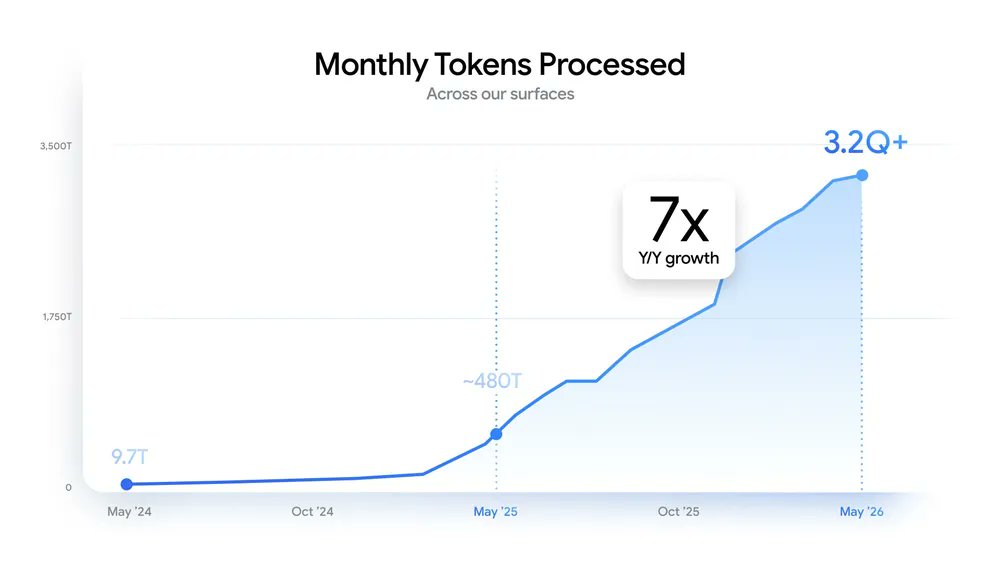
Agentic AI is going to make the current compute demand look small.
Reminder that a simple prompt ~1,000 tokens. An agentic task burns 100k to 1M+...
Now imagine that, but running 24/7 across every timezone. Utilization that was built around "peak human hours" will become irrelevant.
Cursor, Claude Code, coding agents in general... this is the first real agentic wave and it's already stressing capacity.
Now imagine agents rolled out across legal, healthcare, pharmaceuticals, etc.
Enterprise adoption is still under 30%, and most of that is just chatbots... not agents.
Same reason I'm not worried about potential capex cuts or $META’s "excess compute" claim.
Demand was never the worry.
I got a starter $WYFI position and happy to add if there's any FOMC turbulence. 👍
Had a big correction recently (with rest of neocloud theme) and looks ready IMO.
Leopold Aschenbrenner’s Situational Awareness LP took a new position in WhiteFiber in their Q1 2026 13F.
About 991,000 shares, $20.9M position.
The fund manages $5.5B and Leopold turned $225M into roughly that figure in 12 months by being early to the AI infrastructure trade.
So when Leopold adds a position, it's worth understanding why IMO...
His framework is built around AGI by 2027 and the compute, power, and memory bottlenecks that the buildout creates.
$WYFI fits squarely inside that thesis as a pure play AI compute infrastructure operator.
They operate AI compute infrastructure across two segments.
Cloud services and colocation.
They design, develop, and run data centers and provide GPU-based HPC services to enterprise and AI customers.
They also have a $100M delayed draw term loan facility from $BTBT available.
5 year agreement with an investment-grade tech customer for AI compute in the Paris region using advanced NVIDIA GPU systems.
Total contract value exceeding $160M over five years.
$865M 10 year colocation deal with Nscale at the NC-1 campus signed earlier this year.
Q1 2026 revenue at $21.9M, up 31% YoY.
The colocation services division was the standout, up 190% YoY from $1.6M to $4.7M.
Anthropic just signed more than a dozen letters of intent for direct US data center leases totaling over 1 gigawatt of capacity, with $GOOGL backing the financial obligations.
This is on top of their existing $200B Google TPU deal, $50B Fluidstack partnership, and the $35B Apollo-Blackstone private credit financing for their data center buildout.
Anthropic raised $65B at a $965B post-money valuation in late May.
Annualized revenue run rate is past $47B.
They confidentially filed an S-1 for their IPO on June 1.
The largest AI lab on Earth just told the market they need over 1 gigawatt of additional data center capacity, on top of the 10+ gigawatts they have already contracted from hyperscalers.
They're no longer just renting from AWS and Google Cloud.
They're leasing facilities directly.
They're signing colocation agreements with smaller specialized operators.
They're doing this because the hyperscaler capacity cannot keep pace with what AGI-scale workloads require.
Every other major AI lab is doing the same calculation.
OpenAI has its Stargate buildout.
$META has its 5GW Hyperion campus.
xAI has Colossus 2 in Memphis.
$GOOGL has its TPU manufacturing scale.
The capacity demand is multiplying across every frontier AI player simultaneously.
That demand has to go somewhere.
The hyperscalers cannot serve all of it.
That is the structural opportunity for neocloud operators like $WYFI to capture incremental capacity that hyperscalers cannot deliver fast enough.
Disclosure… we have WYFI positions.
We will buy/hold/sell/trade, as we see fit.
Not financial advice; do your own research.
Real revenue growth.
Real institutional sponsorship.
Real customer contracts.
Real macro tailwind from Anthropic and the broader AI capex cycle just getting started.
Attached 1.618 and 2.618 fib levels.
Would love to see a clear break of resistance levels (more charts incoming).
Reminder: Frontier Traders SpaceX ($SPCX) campaign is on for the next seven days
https://t.co/uWMSaziCF0
Brought to you by @sunrise & @torqueprotocol
Very few people saw this news about $AMPG yesterday since it wasn't officially released by AmpliTech... but that changed 2 hours ago.
Should see it start to price in today?
TLDR: $AMPG is the only American company that designs and commercializes O-RAN CAT B 64T64R Massive MIMO radio units, and it just got publicly demonstrated alongside $NVDA.
Great for market visibility, product compatibility, and a foundation for future MNO contracts.
We love double-news days on $AMPG. And it seems like most people haven't seen it yet?
$AMPG's CEO last week said new MNO deals could move straight to Purchase Orders.
2 hours ago, their hardware was publicly demonstrated alongside $NVDA's AI Aerial in Northeastern's first open-source mMIMO AI-RAN system...
Feels like we're watching pipelines & demos develop into contracts? Imagine an $NVDA deal...
$AMPG just received full FCC and ISED Canada certifications for their 5G Native DAS Solution.
Their entire hardware stack is now approved for commercial sale across North America.
Phase 1 of the valuation gap fill towards $1B MC... still 10x away. Did you listen?
So during my deep dive into Space, cross checking names that Renaissance holds, I came across only two names under $1B MC.
> $SATL (~$1.4B MC now) - I called an entry for you at ~$3, now it's ~$9.60 (I hope you’re enjoying that 3x+).
> And $AMPG. Currently sitting at ~$98M MC.
(While I remain bullish on both names, I’ll lightly compare the two for the sake of this post)
The interesting part is the actual fundamentals behind it, backed by numbers...
$AMPG is debt-free (very rare for small caps), 165% revenue growth in 2025, $50M revenue guidance, with a $20M+ backlog. Imagine revenue being half your market cap… that’s asymmetry.
$AMPG is generating ~14x more revenue per dollar of MC than $SATL at this very moment. Meaning, they have similar revenue, but $SATL is trading at 14x more.
I can see why it's the only space-related name RenTec holds under $1B MC... it also has multi-sector exposure, (satellite, 5G, defense, quantum) making it a multi-thesis bet.
And you know me, I love those valuation gap fills.
If $AMPG scales towards $SATL's ~$1.4B MC, that's quite literally 14x from here.
And if you want direct product competitors, there's even more asymmetry (mind you $AMPG is in a unique position in its own unusual niche):
> $MTSI offers the same products and end markets. Sitting at ~$27B MC.
> $QRVO is a major RF/microwave competitor as well, which currently sits at ~$8B MC.
> From the defense aspect, $LHX is the most vertically integrated comparison at ~$58B MC.
As for technicals, using https://t.co/r8G8UwUxO6 indicators, we just got the third BD (final buy-signal) on the Weekly timeframe.
We've seen how this usually plays out.
I started a position after my research.
Will ride this for a while.
As usual, NFA.