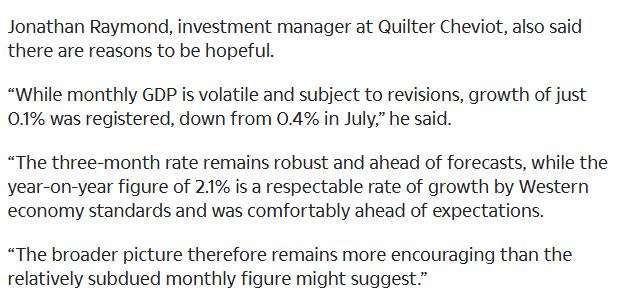
Today’s better GDP data and lower bond yields (10-year down 0.1%) underline Kallum’s conclusion here.
Counterintuitively, stronger growth should bring down yields due to less need to raise taxes and choking the economy.
Healey signals he won't pay for budget giveaways with more borrowing and the UK bucks the trend of rising yields . . . . the UK's problems really are not complicated . . . fiscal discipline = stronger growth
“The other problem is that much of this decarbonisation was achieved through deindustrialisation. In the face of higher energy costs and rising environmental taxes, many manufacturers relocated overseas”
Chickens coming home to roost after 20 years of bad policy.
FOOL BRITANNIA by @EdConwaySky
While many countries face higher energy costs due to the events in the Middle East and Russia, few have seen quite as big a spike as Britain has. Industrial power costs are comfortably higher than in most developed nations, with domestic costs not far behind. To some extent, this is a function of bad luck and geopolitics. Britain is particularly dependent on natural gas to provide the critical baseload power for its electricity, not to mention much of its domestic heating.
But higher energy costs are also the product of policy. Britain pushed faster and further towards net zero (the goal of diminishing carbon emissions to close to nothing in net terms) than most of its peers. The ambition, held by Labour and Conservative governments, was that the UK should be the global leader in decarbonisation – the flag-bearer for net zero. In one respect, the enterprise was a stunning success – Britain is one of the fastest-decarbonising major economies in the world.
The main catch in – and the cardinal sin of – the make-things-cheap economy is how it affects energy bills. For all that Boris Johnson and Ed Miliband insisted (and as far as I can tell, sincerely believed) that renewables would mean lower costs, the opposite has happened. Unlike solar power, the cost of which fell precipitously as the Chinese mastered the mass production of arrays, wind power has remained comparatively expensive. And so Britain’s ambitious offshore wind programme happened largely thanks to a complex web of subsidies and price guarantees. Those interventions will lock in higher power costs in this country for years.
There is a point – most likely a decade and a half in the future – at which the savings from net zero (less spent on gas and fuels) should outweigh the costs of building all the necessary infrastructure. But for the time being, the policy is expensive – nearly £30bn a year for the next five years, which is the equivalent of an extra 5p on the basic rate of income tax. One of the main reasons net zero is becoming so controversial (and will likely get more controversial) is that the majority of those costs end up on consumer bills.
The other problem is that much of this decarbonisation was achieved through deindustrialisation. In the face of higher energy costs and rising environmental taxes, many manufacturers relocated overseas. Indeed, more than half of Britain’s carbon footprint is now accounted for by imported goods. Paradoxically, the more steel mills and chemicals plants shut down, the better the UK’s environmental credentials, since net zero plans ignore the embedded carbon in our imports and focus solely on what is puffed out of domestic flues and chimneys.
Cover art by Doug Chayka
Simon hits the nail on the head here. The incentives skewing the wrong direction as for most people, there assets but be more liquid as they get older not less.
The combination of pension pots being brought into scope for IHT from next April (Reeves) and this proposal from the Leader of the Opposition would have the impact of massively increasing the incentive to hold property wealth over more liquid and (historically) higher return financial assets.
Not sure looking at the current breakdown of UK wealth (and comparing to the US) that is the direction policy from both main parties should be leaning.
You either get very, very bullish on equity release, or conclude that end of life assets are going to be very illiquid and will amplify financial planning/ social care challenges.
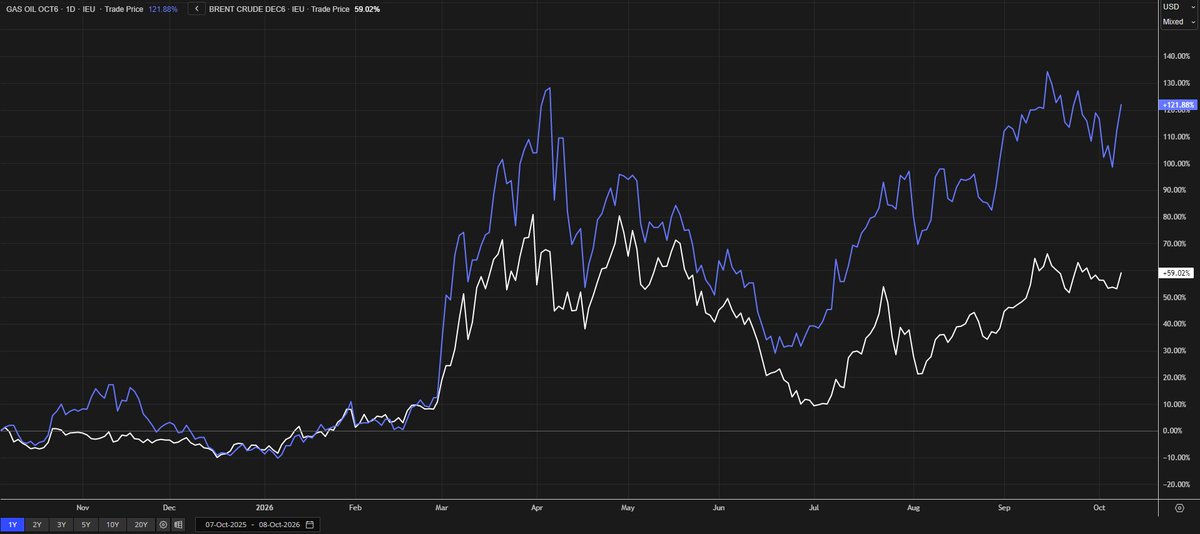
Lloyd made the point that it's not oil per se that's the issue for inflation, but refined oil products ie diesel and jet fuel.
The gasoil price (benchmark for refined oil products, blue line) has risen a lot more than oil (white line) due to shortage of refining capacity.
Taking Stock: After The Bell 🛎️
Episode 71: Bonds Behaving Badly 📉
Hughesy and I are joined by Premier Miton's Lloyd Harris to discuss rising bond yields, sticky inflation, energy markets, AI-driven borrowing and the opportunites in fixed income.
https://t.co/HiNhNiNsRE
@PolemicTMM This is excellent, thanks for sharing. I’m happy to nibble at the 5-year on the basis the BoE will struggle to raise rates to 5% but can see the appeal of the longer end.
@cookiejargolf@Rosapenna1893 Whisper it quietly, we actually preferred Old Tom over St Pats last year. It felt more of an old skool links and not a manufactured, OTT links with the American tourist in mind. Still great though of course!
Taking Stock: After The Bell 🛎️
Episode 71: Bonds Behaving Badly 📉
Hughesy and I are joined by Premier Miton's Lloyd Harris to discuss rising bond yields, sticky inflation, energy markets, AI-driven borrowing and the opportunites in fixed income.
https://t.co/HiNhNiNsRE