MOVE01
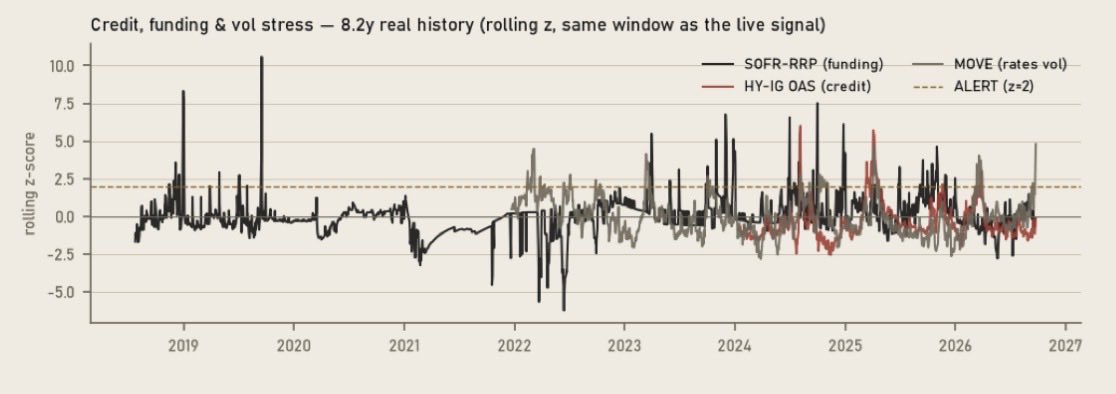
Our model for interest rate volatility against the trend of interest rate volatility in the last 120 days.
This model printed a 4.8-sigma (standard deviation) move yesterday.
In other words a statistical anomaly, assuming a perfectly normal distribution, the probability of this occurring is 0.000159% or 1 in 630,256.
But in the 120 day window, a move like this should be statistically impossible, what you have seen the last two days from treasury yields is a violent repricing of the yield curve.
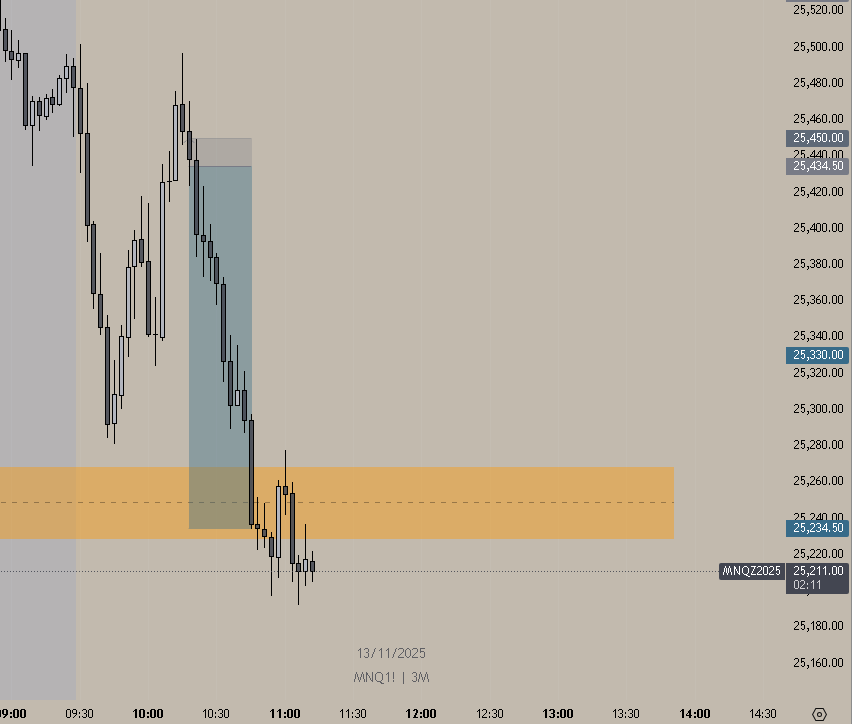
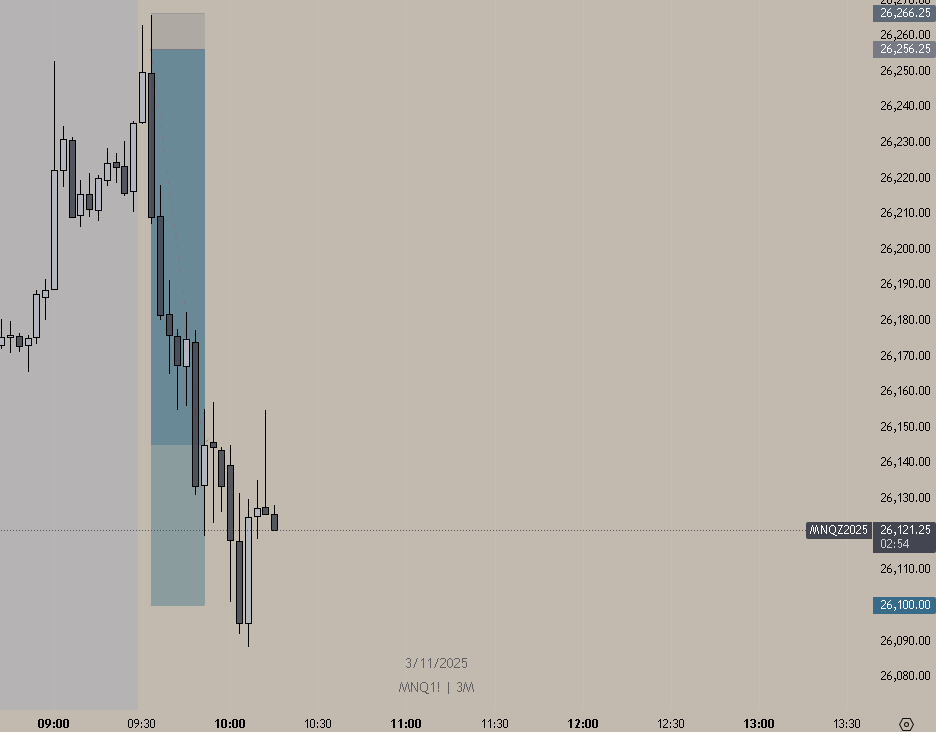
$NQ #Futures
3 Micro Contracts 111.25 points 15.63 RR
Which now brings our futures trading account to 360% in three trades this quarter
We will continue to compete in the most competitive markets in the world and prevail.
@Rainbow6Game No one cares fix the cheating I haven’t played a single game today that wasn’t against a cheater. For a million probably billion dollar corporation, y’all are fucking terrible at your jobs