Highly recommend for matured audiences only 🎬
Not for the Weak, Not For the kids 🔞
1. The Voyeurs (2021)
2. Room in Rome (2010)
3. Chloe (2009)
4. Lust, Caution (2007)
5. The Handmaiden (2016)
6. Nymphomaniac: Vol. I & II (2013)
7. In the Cut (2003)
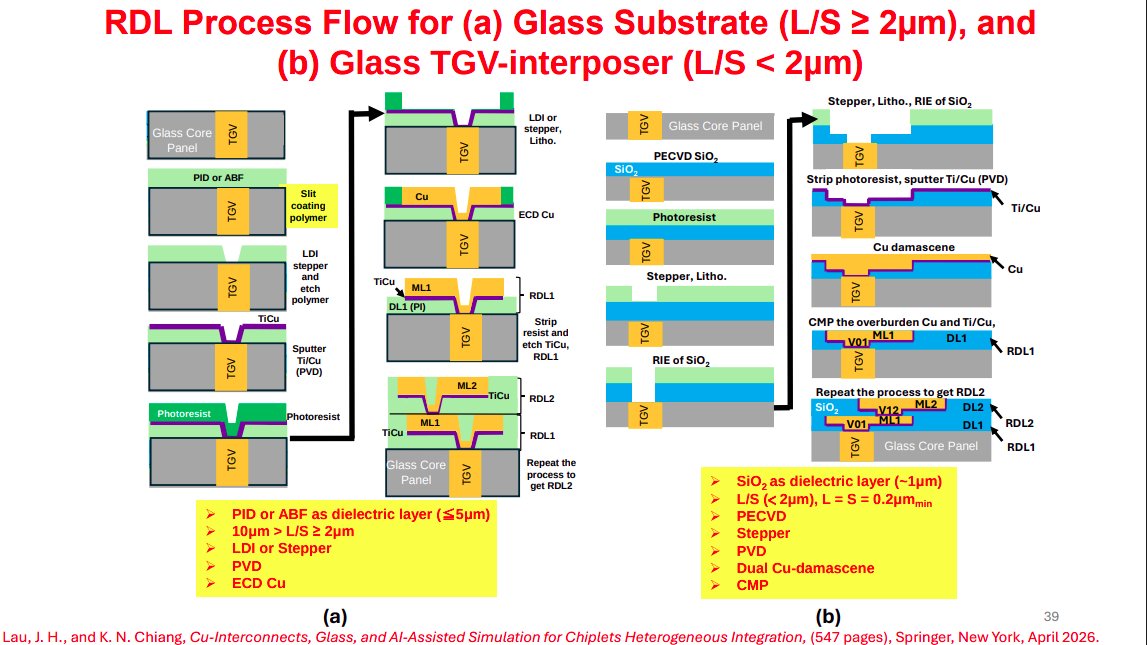
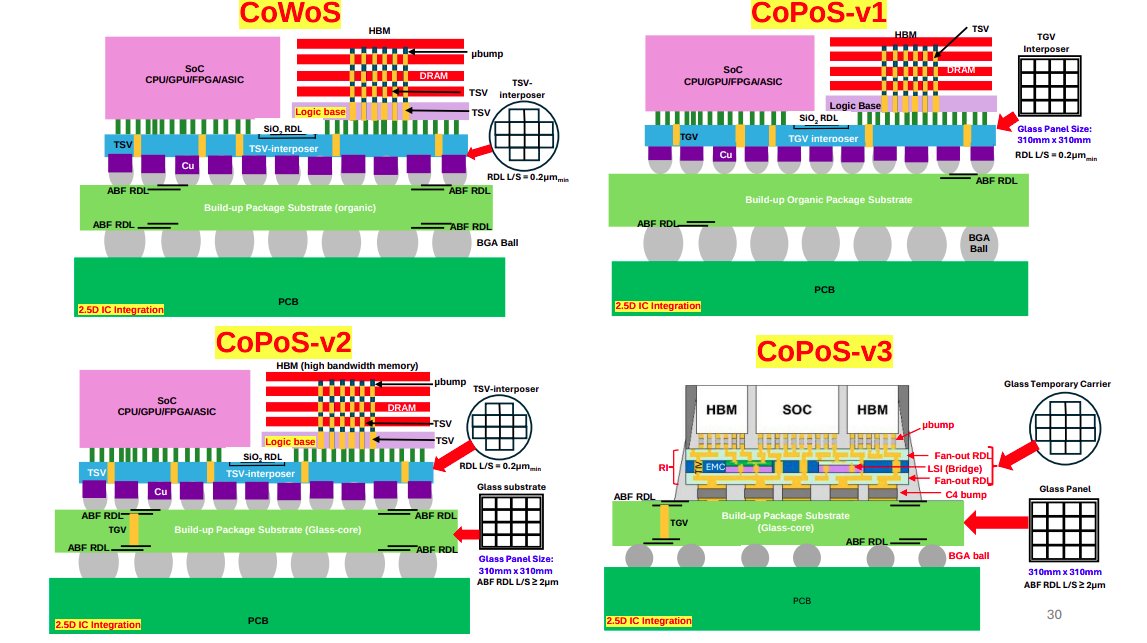
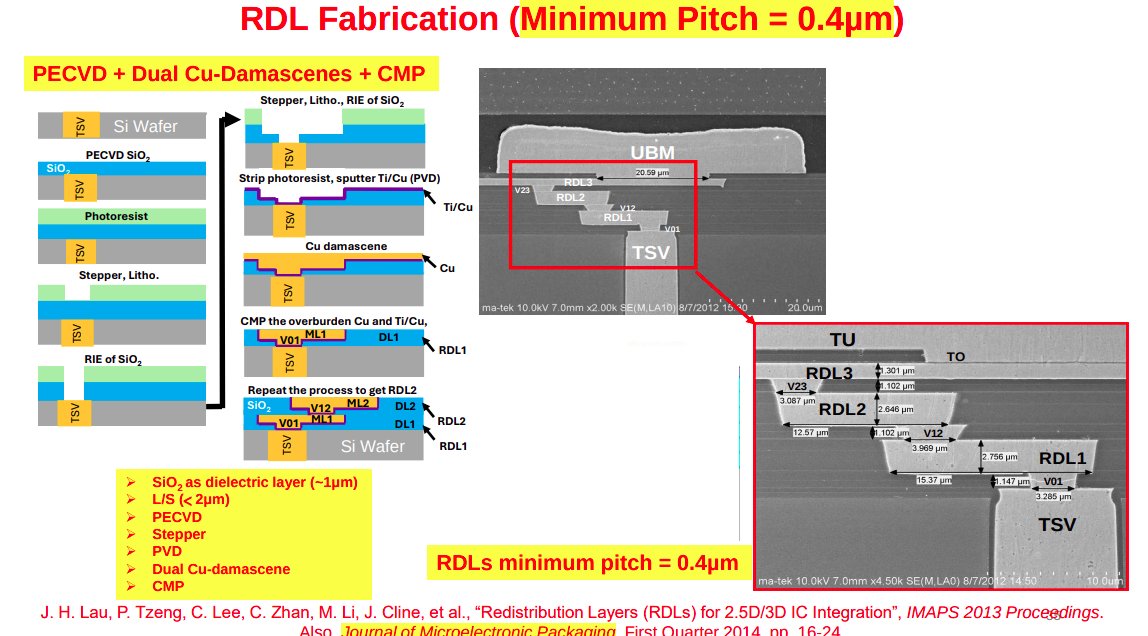
If you're looking for a complete overview of glass packaging, this is it. 80-page slide deck just published by John Lau, IEEE fellow.
https://t.co/9GsbHRJmv7
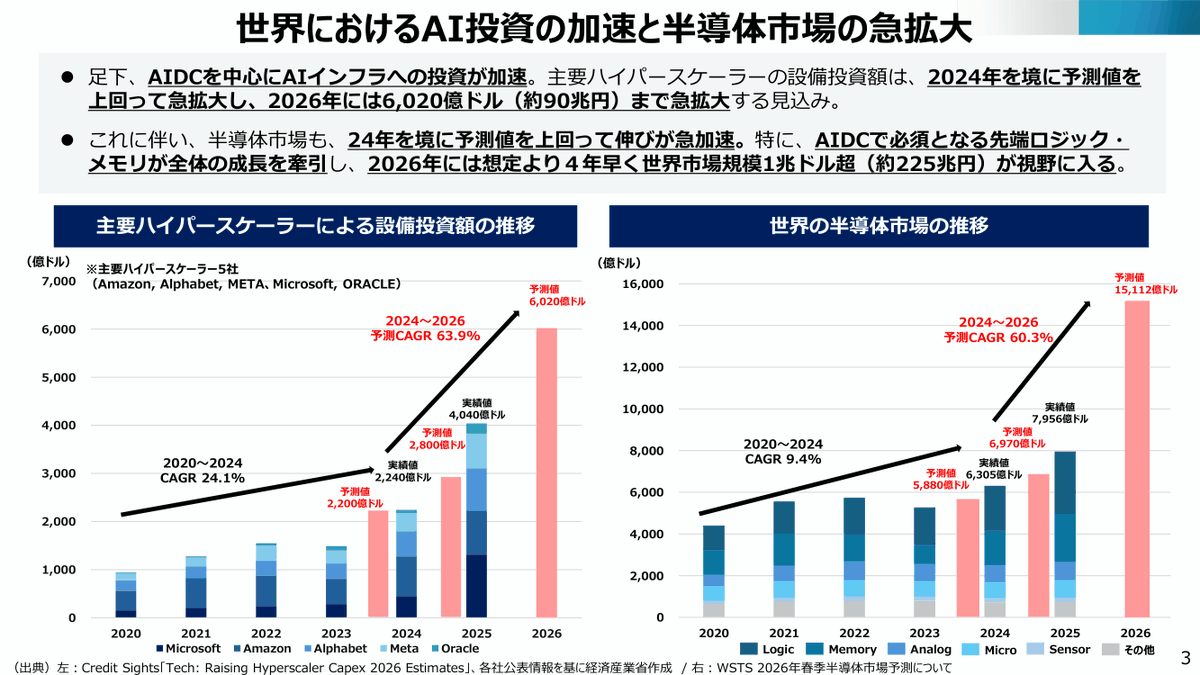
미국은 현재 역사상 가장 큰 인프라 투자 물결을 목격하는 중.
데이터 센터와 AI 인프라에 대한 총 투자는 2025년부터 2032년까지 매년 미국 GDP의 3.63%를 평균적으로 차지할 것으로 예상되며, 이는 1800년대 이후 주요 인프라 건설 중 가장 높은 비율.
골드만삭스도 2027년 국내총생산(GDP) 대비 하이퍼스케일러��� 자본지출이 차지하는 비중이 1800년대 후반 철도 건설 ��� 이후 가장 높을 것으로 예상하는중.
다만 투자 증가 속도는 점차 둔화할 전망.
올해 약 100%에 가까운 자본지출 증가율은 2027년 54%,
2028년에는 12%까지 낮아질 것으로 예상.
2028년 투자액은 약 1조4000억 달러로 추산
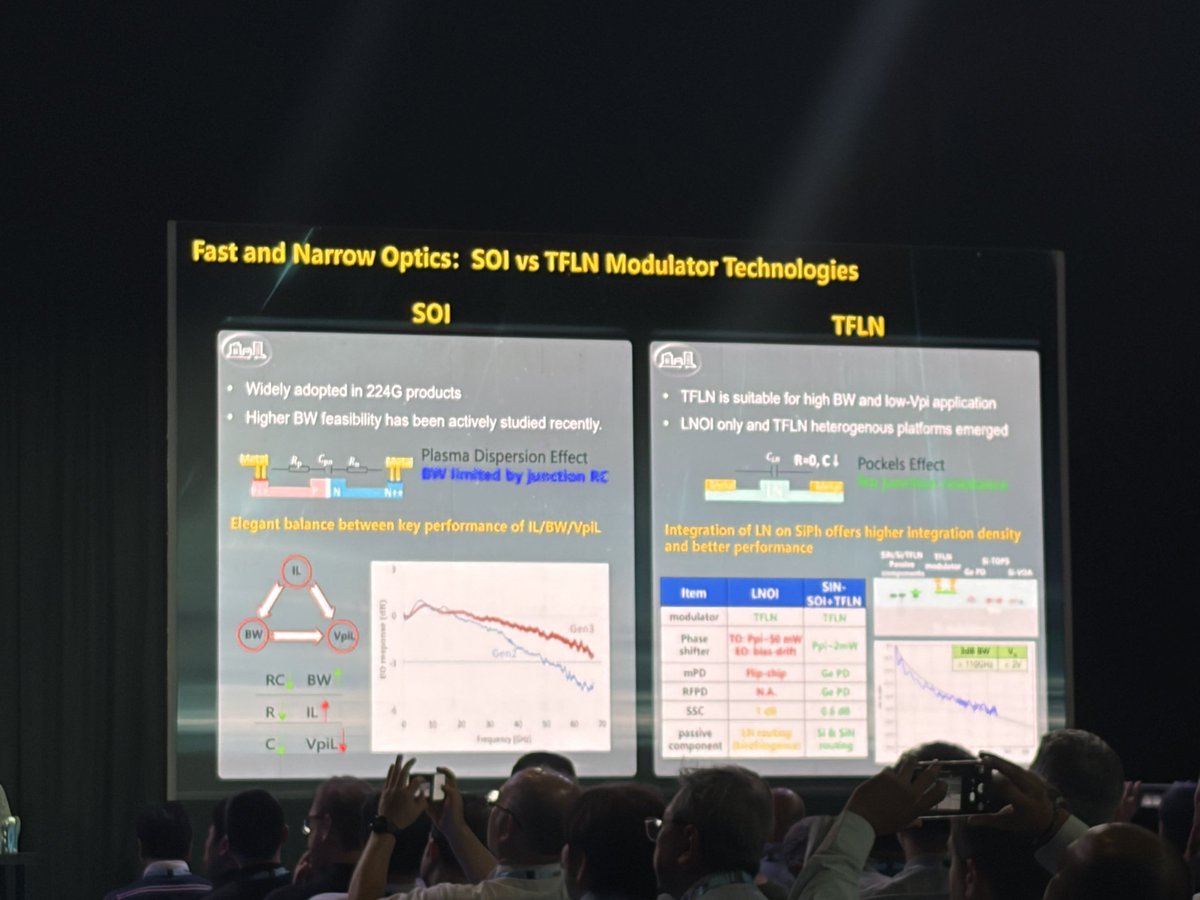
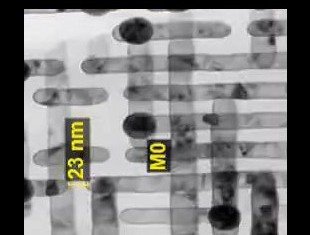
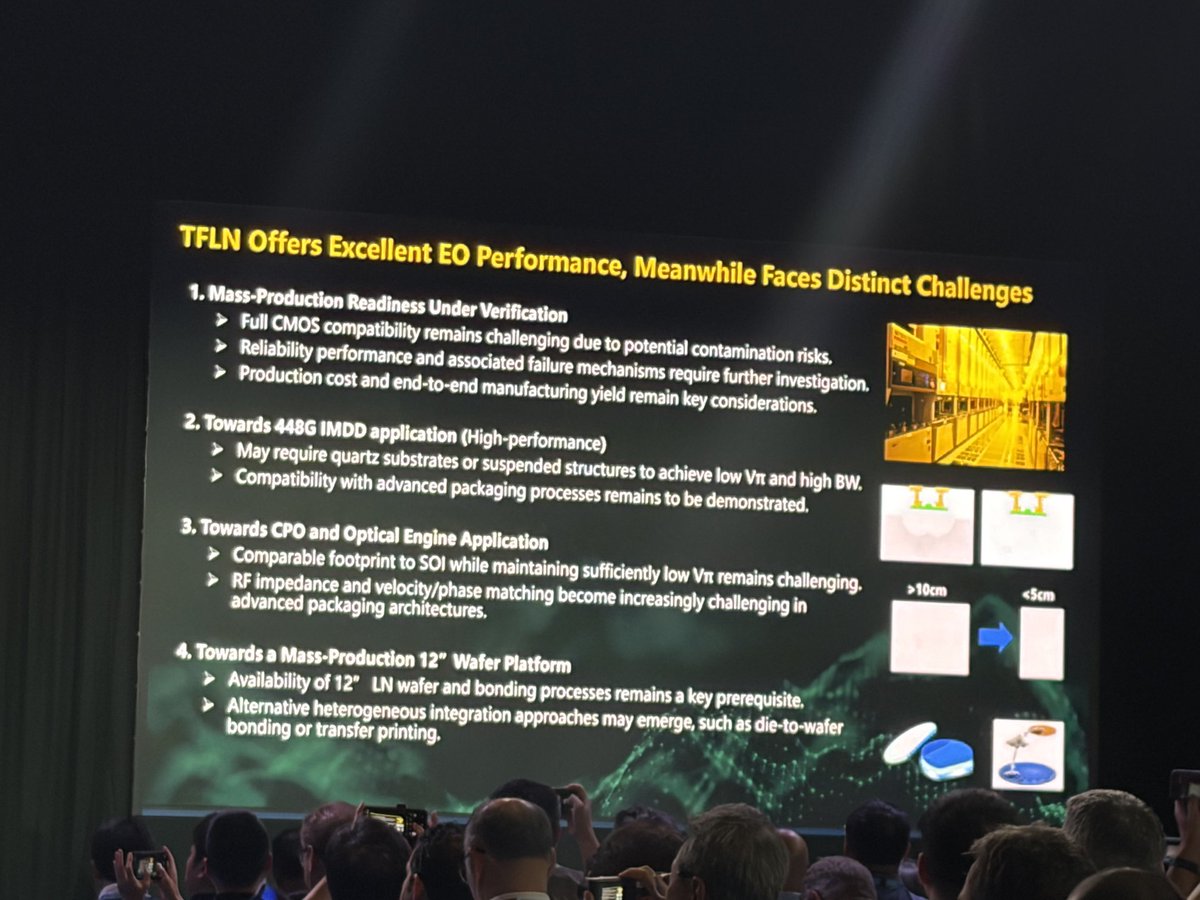
At 200G per lane, silicon photonics or SOI runs out of steam as a modulator. Silicon MZIs can only switch so fast. However, that does not mean TFLN will displace it. TFLN still faces significant supply chain and manufacturability challenges. Some of which include CMOS compatibility, reliability, and cost. This gives EML the opportunity for a comeback!
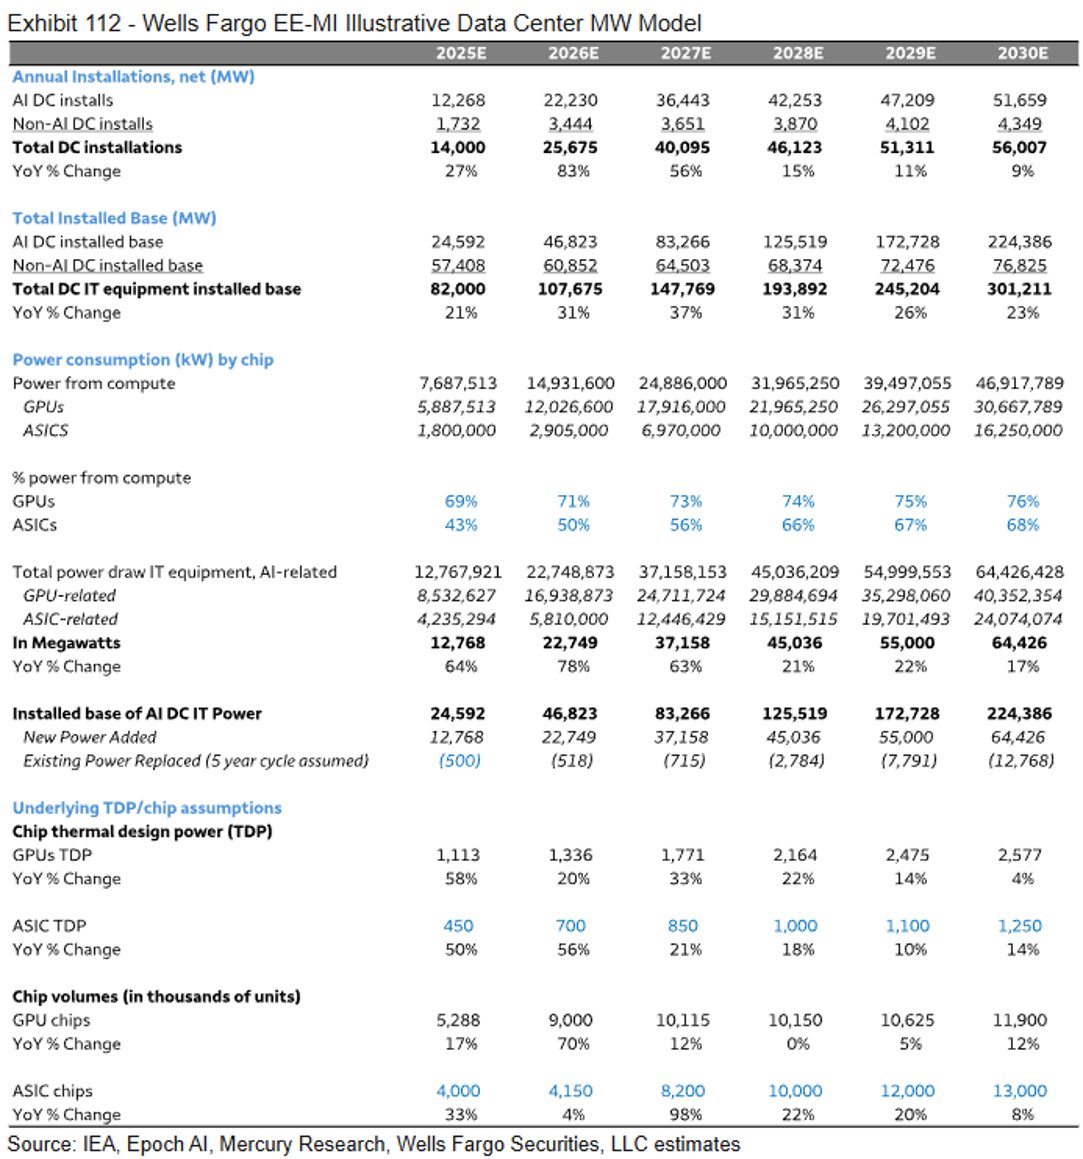
Datacenter GW forecast and GPU/ASIC mix from 2025-2030E per Wells Fargo.
Demand and semis buyside expects are much higher than this. For instance Wells has 15GW of ASIC deployments in 2028 vs. $AVGO alone has customers expressing demand for >20GW in FY28. Add to that $MTK $MRVL $Alchip maybe even $QCOM.
I think this forecast is more likely a scenario where constraints (capital, power) and moratoriums finally play a governing role the AI buildout pace. Eye on midterms.
The Chinese AI Infrastructure Boom:
Introducing the SemiAnalysis China Datacenter Model
1,000+ facilities across 60+ operators mapped,
built retail-first and flipped by AI,
largest hyperscaler leases 1/5 national capacity, 100MW in 12 months, Eastern Data Western Compute
https://t.co/twnBOg773d
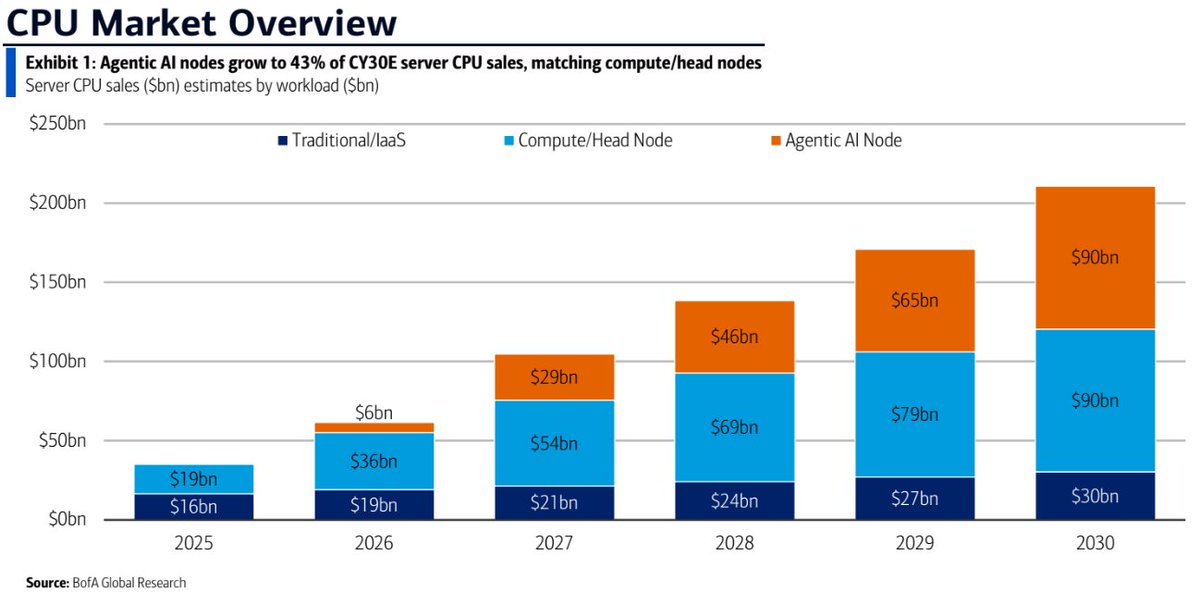
B of A: CPUs power Agentic AI
This should be the least surprising message for all AI investors. But here's some insights from Bofa's expert call on the CPU market that might add more
- CPU and GPU demands are now symbiotic, thanks to agentic AI
- CPU won't replace GPUs as it cannot be reduced to "cores/ user"
- Substantial variations by operator, workload, architecture and utilization
- $META muse has CPU-rich architecture
- $NVDA emphasizes faster, fewer cores that return tasks to GPUs
- $ARM 's AGI CPU though emphasizes on higher cores
- $AMD and $INTC targets a broader offering covering both scenario
- Time-to-completion, agents/racks, memory / thermal constraints are key deciding factors of architecture
- Expert expects CPU content of $4-$5K+ per Vera GPU
- ARM based server CPU to have 40% share (50% by decade-end)
- x86 deeply entrenched in legacy cloud/enterprise players. Advantagous in greenfield projects