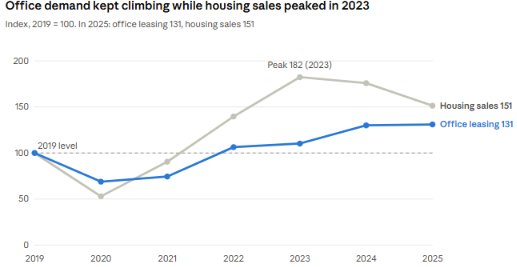
Risks: AI job cuts, stretched affordability in Mumbai and Delhi NCR (EMIs take 67–69% of income), unsold stock, and oil prices and interest rates. Expect a steady climb led by a few cities, not a China-style boom.
Bear case: top 7 cities avg prices rise 3-5% a year, reaching ₹11,300–12,400/sq ft by 2031
Base case: prices rise 5–7% a year, reaching ₹12,400–13,600/sq ft by 2031.
Bull case: prices rise 8-10% a year, 14,300-15,600/sq ft by 2031
Other demand sources: 2nd homes (Goa, Alibaug, Dehradun; the luxury segment is growing ~20% a year), families leaving Delhi’s polluted air, pilgrimage towns (some parts of Ayodhya are up more than 4x since 2020), and investors earning ~10% on co-living vs 2–5% on ordinary flats.
What’s splitting households:
1) nuclear families
2) rising divorce, where one home becomes two
3) later marriage, with single women now 22% of buyers
4) parents living apart from grown children
Only 1.5% of potential senior-living demand is met, vs 6–7% in the US.
Outside the box: housing demand is counted in households, not people. By my rough maths, India needs ~64 million more homes by 2036, and population growth explains only ~27 million of them. The rest comes from households getting smaller.
Indirect effects:
The $100k US H-1B fee pushes work offshore into Indian GCCs.
The 8th Pay Commission (~49 lakh employees, ~68 lakh pensioners) lifts cities with many government workers.
AI may reduce demand in mid-priced homes in IT-services suburbs.