Crude down five days in a row now. Diesel just hit $6.5276 a gallon, a record.
I keep staring at that pair. The crack spread is the whole story: turning crude into diesel earned $100+ a barrel earlier this month, first time ever. Normal is $20 to $30.
Somebody's getting paid for the refining, not the oil.
@tierrapartners No struggle clearly. Just pointing out the state of the business itself is still rocky. Need some signs of inflection in housing because a lot of names definitely have torque down here.
$KBH with a weird one. Revenue -20% yoy, net income -41%, and EPS beats by 16% anyway.
The trick is the share count. Diluted shares down 8.8% yoy after another $50M of buybacks. Same share count as last year and EPS is $0.96, not $1.05. That's more than half the beat.
Well that didn't take long. PayPal announced this morning that Muse can check out across its merchant network. $PYPL was up ~5% at one point. The agent still needs someone to process the payment.
Starting to think payments stocks may actually be worth something here.
Not like the other 25 times Furus tried shilling $PYPL $FOUR etc… but there’s going to be a need for them in the agentic world and the market finally dumped them far enough for me.
Any ideas?
$SCHW down 5%+ into the close. Nothing to do with rates or flows.
Muse hit #1 on the App Store yesterday. Today the market drew the second-order map: Shopify got the distribution trade, Schwab got the disruption trade, with investors pricing AI agents into advisory margins.
The speed of that repricing is the thing. One session from app-store chart-topper to a 5% de-rating in financials.
@charliebilello Zooming out: M2 fell 4.76% peak to trough from April 2022 to October 2023, the first contraction since the Great Depression. 5.7% YoY is the mirror image. One quibble on framing: this cycle's M2 is bank credit creation, not the Fed printing.
$AAPL crossed $5T today. Full run on the chart: $1T in Aug '18, $2T in Aug '20, $3T in Jan '22, $4T in Oct '25, $5T now. The $3T to $4T leg took 3.8 years. This one took 9 months.
A human concierge doesn't replace the inference bill. Every Muse task still runs on compute, and adding a staffed layer says Meta is finding demand for more of it, not less. https://t.co/8odCSQv2pW
@Mr_Derivatives The S&P bank ETF is tracking its lowest close in 3+ months today, on its longest losing streak since March (Barron's). Came right after the Fed hike last week.
Higher rates are supposed to be good for banks.
$TWLO: +9% yesterday, another ~6% today. No earnings, no company news.
The Muse trade moving one layer down the stack. TD Cowen raised to $300 from $260 Monday with the thesis that AI agents drive "significantly higher communications flows," unlocking demand for Twilio's texting/voice/WhatsApp rails.
Muse runs inside WhatsApp now.
@zerohedge 474 GW. That's what ERCOT was reviewing in connection requests before Texas hit pause. More than 5x the state's record peak demand, and roughly 90% of it data centers (Reuters).
And the audit could run into December.
@pequityresearch KB Securities this morning: server DDR lead times at 52 weeks vs a 6-week normal. Now Funda saying memory prices beat expectations into Q4'26 and keep rising in Q1'27. Not just an allocation story anymore. $MU
@KobeissiLetter Biggest daily print since Oct 2025, back when BTC was at $126k. The stat that matters more is Seyffart's: the average US spot ETF holder is back in profit for the first time since January. Everyone who bought the top is finally above water.
Amazon already blocked Muse. Shopify wired it into Shop Pay instead, $SHOP +7.3%. When the agent is the checkout, the shopping query never touches Google.
Where does $GOOG go from here?
You have to imagine search is in even deeper trouble in the agentic era, so unless DeepMind pulls a rabbit out of its hat where does the business head?
GCP is strong, so is YouTube, but just feels like the company is flailing a bit again.
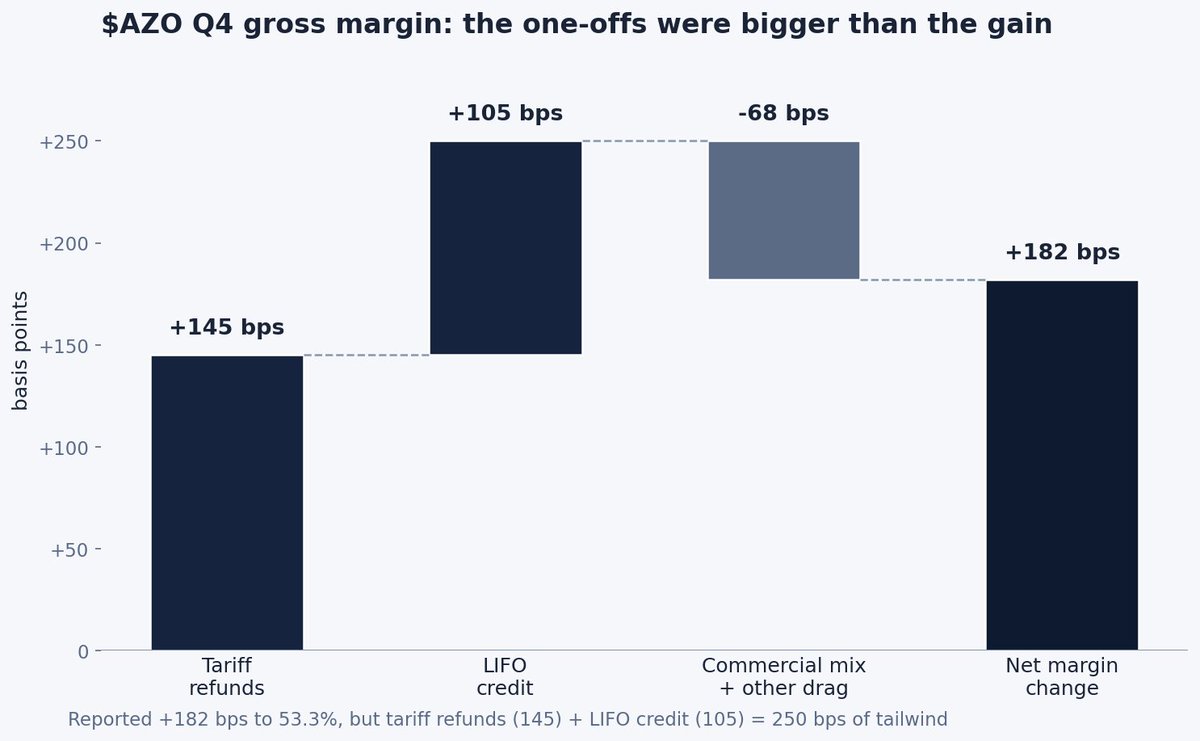
$AZO beat by ~$2 this morning while missing sales and comps, and the stock is up anyway.
The beat is all in the margin line. Gross margin +182bps to 53.3%. Of that: 145bps tariff refunds, 105bps non-cash LIFO credit.
The tailwinds were bigger than the gain. Underlying margin went backwards.