Bank of Japan Tankan business confidence survey drops 1 October 2026 at 08:50 JST. Manufacturing and non-manufacturing diffusion indexes are key data points for JPY direction and BOJ policy expectations. Watch USDJPY, EURJPY, GBPJPY for reaction.
Bank of England released its 2026 Q2 banking sector regulatory capital data, covering capital ratios and risk-weighted assets. No new figures disclosed in the release, so expect muted reaction in sterling. Watch GBPUSD and EURGBP for any broader macro drivers.
#BOE
ECB Governing Council decision drops 30 September at 14:15 CET, presser follows at 14:45. These events are major EUR volatility triggers as markets parse the rate path and forward guidance. EURUSD, EURGBP, EURJPY in focus.
#ECB
Chicago PMI surged to 58.8 from 47.1, crushing the 51.3 forecast. But the beat stands alone, softness in ADP, PCE and spending weigh against it. Regional volatility rarely moves the needle when the macro picture is mixed. USD remains neutral.
#USD#PMI
SNB published Quarterly Bulletin 3/2026 on 30 September. No major policy shift or guidance change flagged in initial coverage, though SNB publications often shape views on Swiss inflation and franc momentum.
#SNB
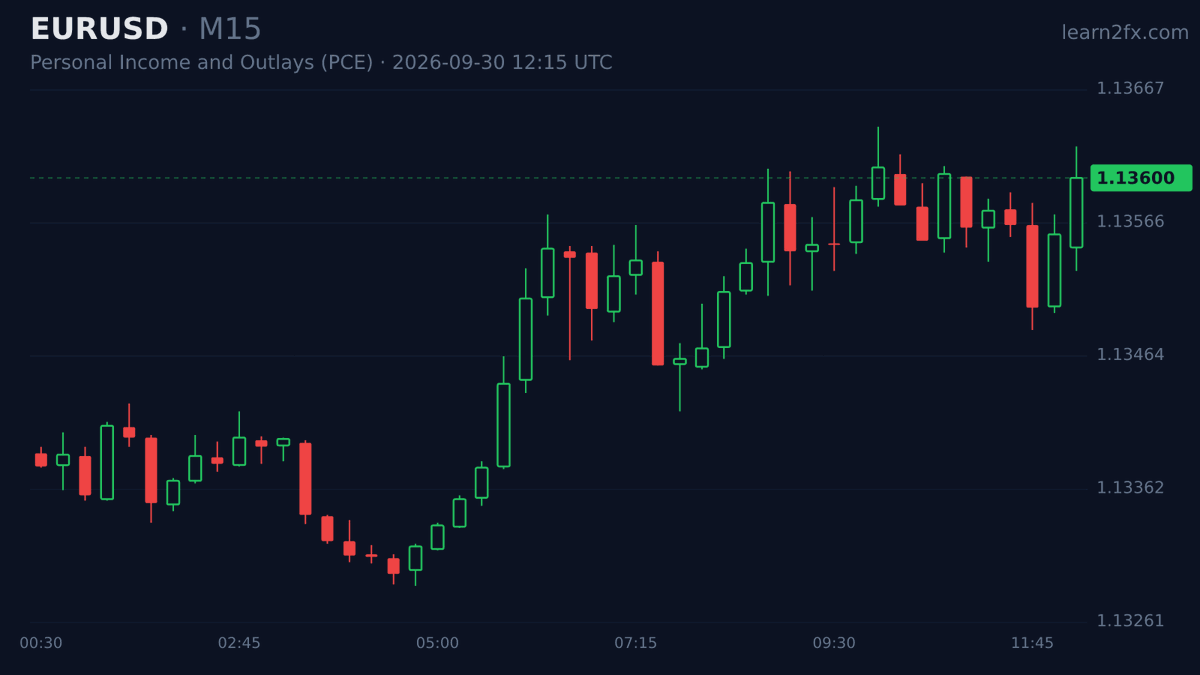
PCE inflation printed 0.2% vs 0.3% forecast, a dovish miss that weighs on the dollar through rate expectations. ADP was the real shocker at 38K vs 70K, while Personal Spending lagged at 0.9% vs 1.0%. Watch Non-Farm Payrolls and CPI next for confirmation.
#USD#Gold
USD Final GDP Price Index q/q landed at 6.4%, matching forecast and the prior 6.4%. Pure noise. Soft ADP at 38K and PCE income miss at 0.2% are the real movers today. Non-Farm Payrolls next.
#USD#GDP
US GDP came in at 1.5%, exactly matching forecast and down from 2.1% previously. The print itself is a non-event, but the concurrent ADP miss (38K vs 70K forecast) is driving softer USD on growth and rate-cut repricing. Focus shifts to Non-Farm Payrolls.
#USD#GDP
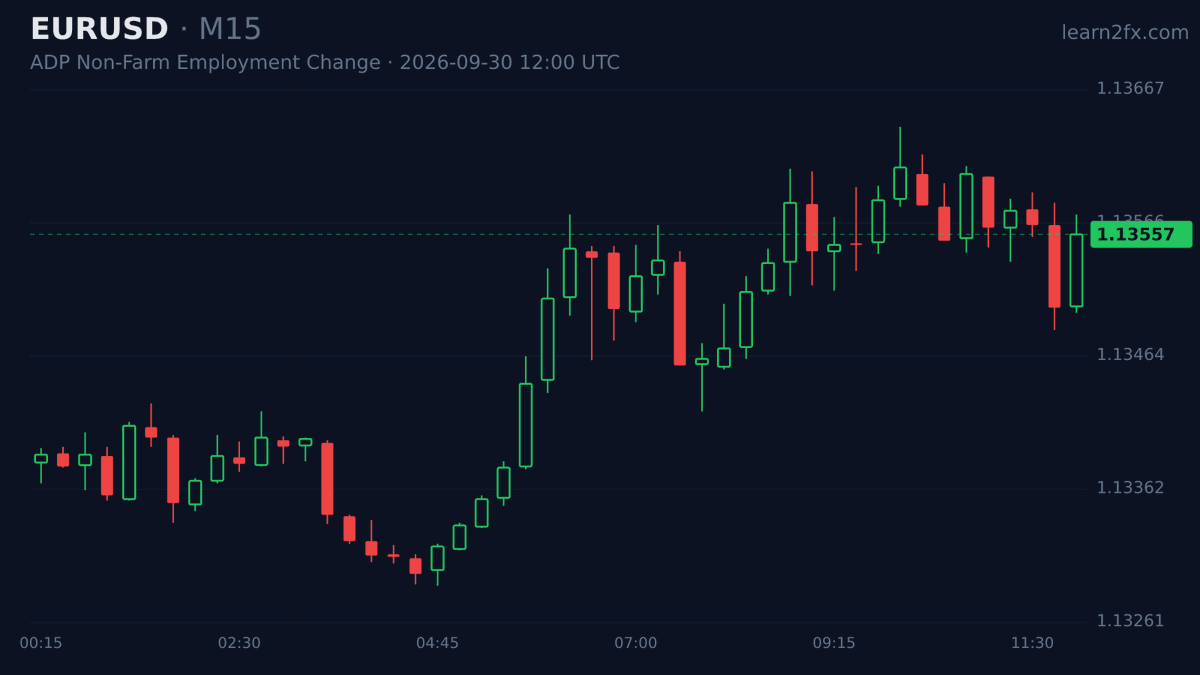
ADP Non-Farm Employment came in at 38K versus 70K forecast, matching the previous 38K reading. Soft private hiring bolsters Fed-easing bets and weighs on USD.
#USD#NFP
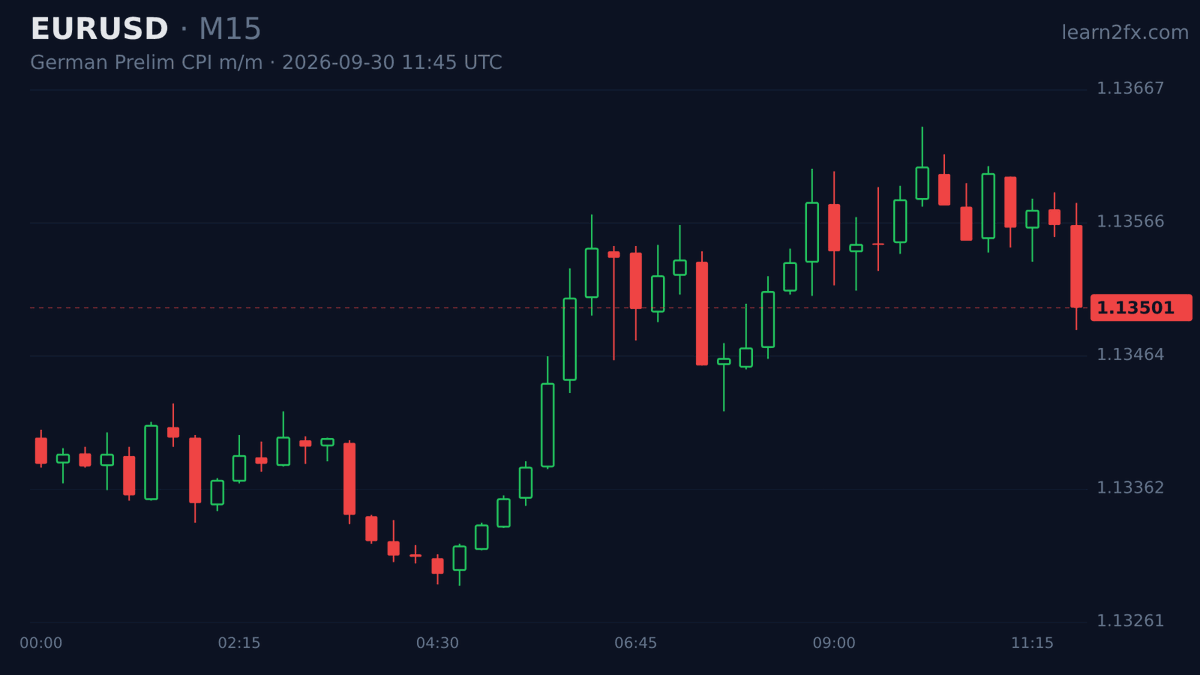
German prelim CPI beat at 0.6% m/m versus 0.5% forecast, up from 0.2%. Import prices surged 1.0% but weaker jobless claims and French spending miss temper any hawkish relief. Small, fleeting EUR upside at best.
#EUR#CPI
Destatis drops German import prices and preliminary CPI on 30 September at 06:00 and 06:30 UTC. Flash inflation data feeds the euro-area picture that shapes ECB expectations, keeping EURUSD, EURGBP and EURJPY in focus.
#CPI
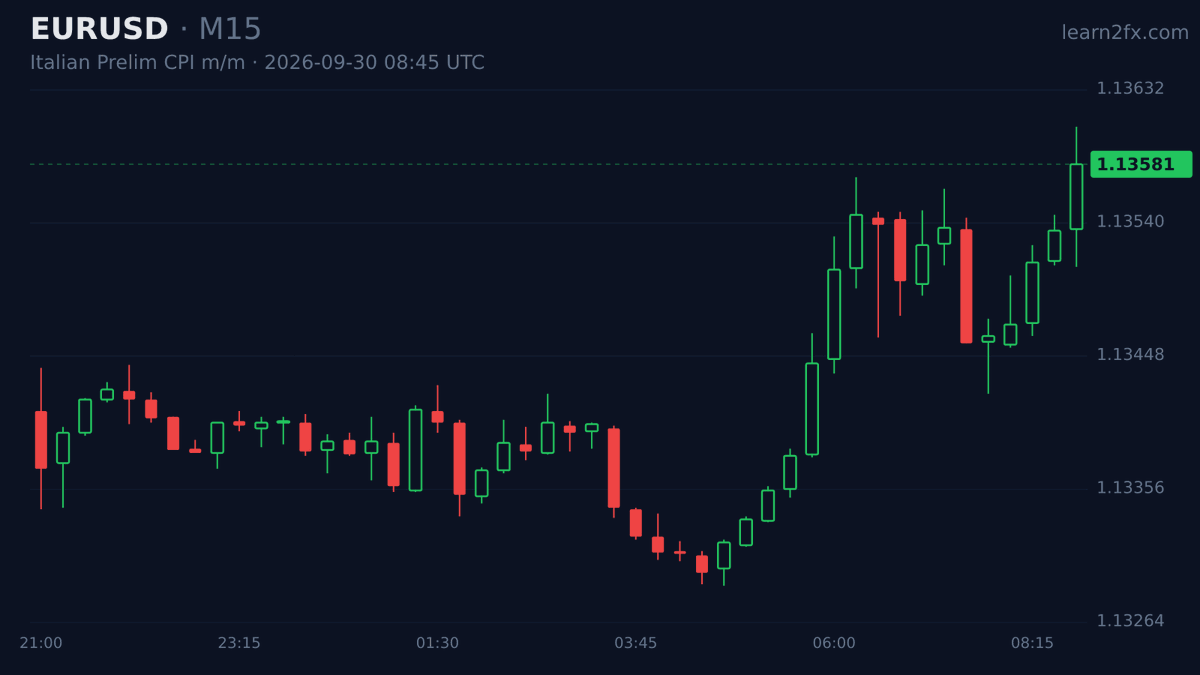
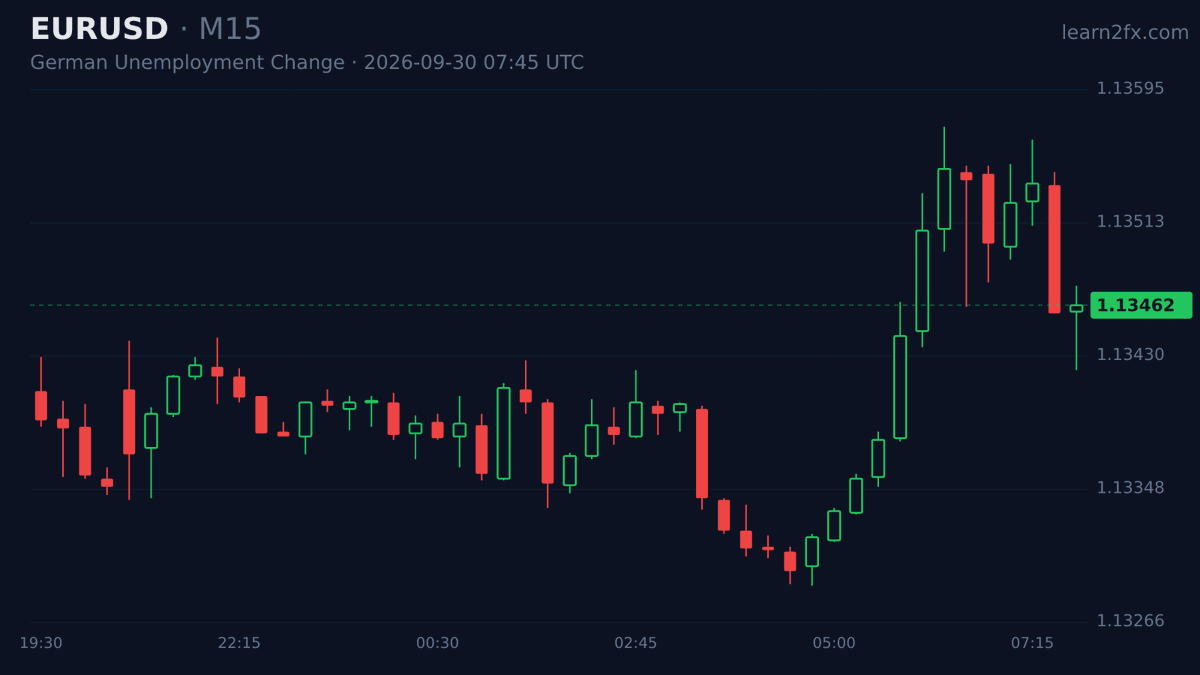
Italian prelim CPI surprised sharply with 0.7% m/m, well above the 0.0% forecast and prior 0.5%. Meanwhile German unemployment rose 12K versus 2K expected, offsetting some of the hawkish read.
#EUR#CPI
German unemployment rose 12K vs 2K forecast, a clear labour miss. Import prices jumped 1.0% and French CPI beat, offsetting the dovish signal. Expect limited EUR weakness. Mixed cross-currents keeping the pair rangebound for now.
#EUR#Jobs
ONS released revised Q2 2026 UK GDP quarterly national accounts, incorporating additional data for a sharper growth read. Watch for any shifts in Bank of England policy expectations on the back of the updated figures. GBPUSD and EURGBP in focus.
#GDP
ONS releases UK Q2 2026 balance of payments data. Current account figures are a key driver of sterling positioning. Watch GBPUSD and EURGBP for reaction as markets digest the UK's external balance picture.
ONS published UK Economic Accounts for Q2 2026 covering national product, income, expenditure, sector accounts, and balance of payments. The release covers data April to June 2026. Watch GBPUSD and EURGBP for any policy shifts.