@BourseLog Thanks for adding the math. That's exactly why we wrote "before or after." One more spot people miss: an automatic dividend reinvestment, or a purchase of the same fund in an IRA, can also count as a buy inside the window. Worth checking before you harvest.
1. Most 2026 tax moves have a hard deadline: December 31. After that, your options shrink to a few items like IRA and HSA contributions.
We boiled our year-end checklist down to save you the read.
Here are the 7 moves to review before the calendar flips:
8. Check estimated payments.
You generally avoid a penalty by paying 90% of this year's tax or 100% of last year's (110% if prior year AGI was over $150,000).
The Q4 payment is due January 15, 2027.
Our full checklist:
https://t.co/ltIJgxGv4G
7. Review equity compensation.
RSUs are taxed as wages when they vest, and default withholding is often lower than your actual rate.
Exercising ISOs can trigger AMT, so we model how many shares fit under the threshold this year.
A market headline isn't a financial plan. We take a calm look at election aftermath and the Ant IPO in our latest commentary. Context, not a trading instruction.
Watch: https://t.co/SK4K6vO9XQ
We put together our 2026 year end tax checklist. Investments, retirement accounts, giving, equity compensation, and business income. Questions to review before deadlines, not a list of moves everyone should make.
https://t.co/ltIJgxGv4G
1/ Most estate plans don't fail because of taxes. They fail because of small, fixable gaps.
We pulled together the list so you don't have to dig for it.
Here are the 7 estate planning mistakes we see most often:
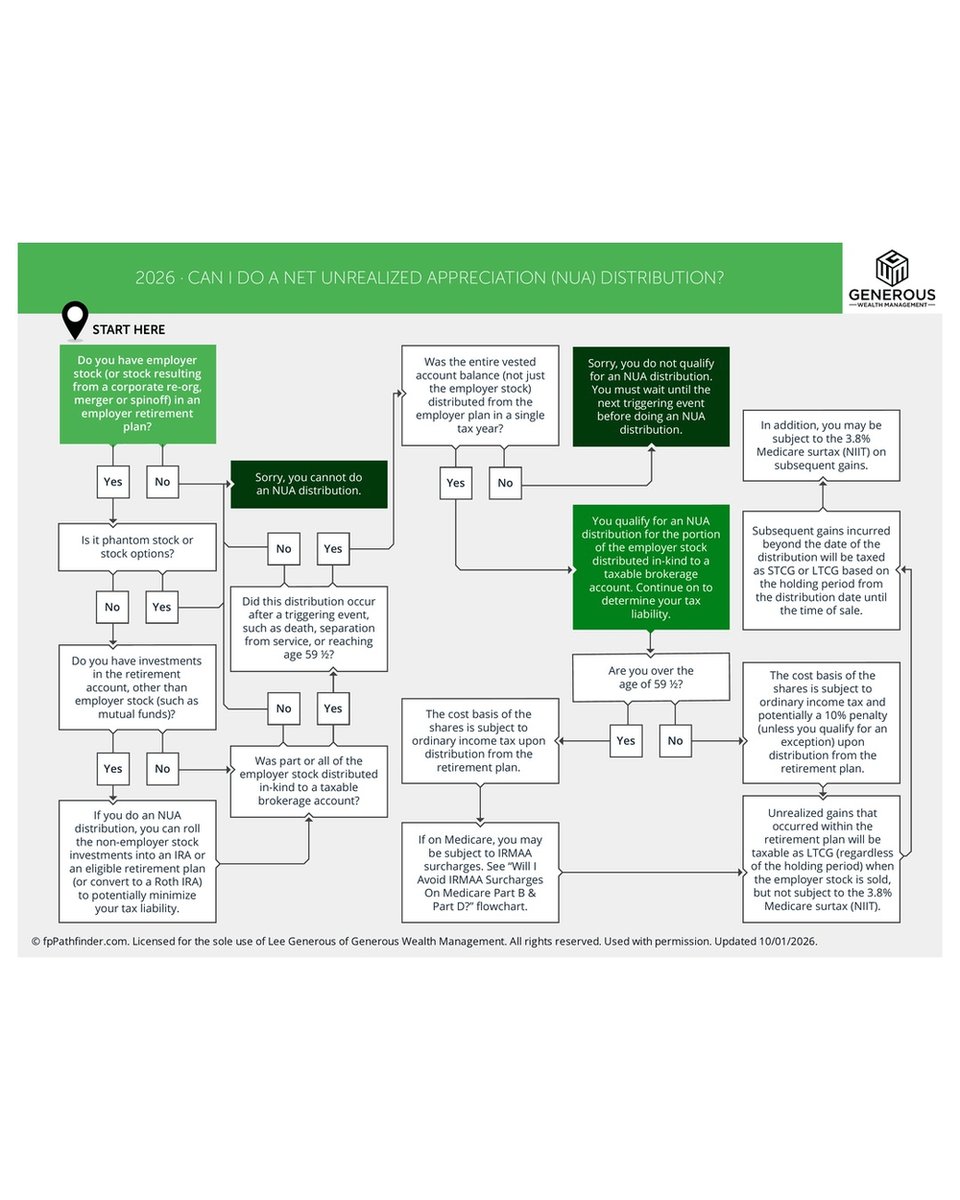
1/ Have company stock in your 401(k)? Don't roll it over yet.
There's a rule called NUA that can change how it's taxed.
We read the fine print so you don't have to.
Here are 7 things to know 🧵
7/ Gains after the distribution date are taxed as short or long term based on how long you hold, and may face the 3.8% NIIT.
On Medicare? The extra income could trigger IRMAA surcharges.