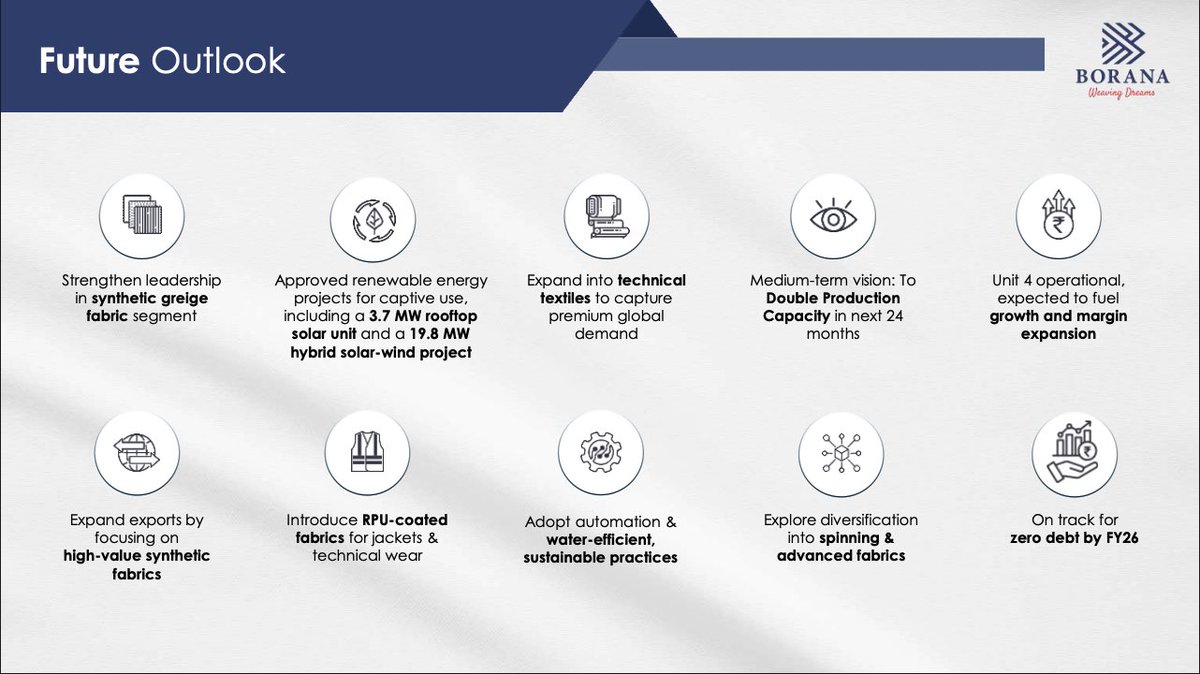
@VakhariaBhumil@nid_rockz Cashflow is negative due to temporary ipo adjustments, otherwise it is high cashflow business (Max 60-75 days credit to customers) . To double capacity they will need around 150-200 Crores so they might take some debt but most of the project should be funded by internal accruals.
@VakhariaBhumil@nid_rockz The weaving machines have faster payback like max 2-3 years if you run efficiently and your product has continuous price and demand support.
The fabric they sell is universal and have good demand as of now.
@VakhariaBhumil@nid_rockz Yes, there’s no special moat in the business but the scale they have achieved makes them first choice for buyers because they know they can get any quantity and consistent quality, because of this they get some premium as well despite being in commodity business.
@VakhariaBhumil@nid_rockz Many are doing it and much more capacity is being added but most of them operate at very small scale, so for them backward integration is not possible and without backward integration your operating margin goes from 20% to 10% and efficiency also drops.
@VakhariaBhumil@nid_rockz The thing is life of machines is max 15 years, so there is replacement capex after 15 years, so depreciation is somewhat real expense for them.
@VakhariaBhumil@nid_rockz The weaving machines have faster payback like max 2-3 years if you run efficiently and your product has continuous price and demand support.
The fabric they sell is universal and have good demand as of now.