THIS MAN JUST MADE THE BEST #BITCOIN AD EVER
HE PUT $100,000 IN THE BANK AND CAME BACK THE NEXT DAY TO WITHDRAW IT
THEY REFUSED TO GIVE IT BACK
"IT’S YOUR MONEY UNTIL YOU ACTUALLY WANT IT"
MUST WATCH 🔥
At $1,000 Bitcoin was for criminals.
At $10,000 it was a bubble.
At $100,000 it was too late.
At $1,000,000 there will be a Fidelity target-date fund holding it for elementary school teachers.
History has an absolutely vicious sense of humor.
What is BITCOIN backed by? Bitcoin is backed by a lot of things, but I’ll highlight just four:
MATH: Bitcoin is backed by math. And math can’t be changed just because some politicians or bureaucrats or members of the Federal Reserve want to change it.
CRYPTOGRAPHY: Bitcoin is backed by cryptography, the same encryption that is used to secure your bank accounts and everything else in the world that is worth securing.
COMPUTING POWER: Bitcoin is backed by the most powerful computer network that humans have ever built, and that network is spread all over the world, and run in a decentralized way by millions of people.
HUNDREDS OF MILLIONS OF PEOPLE: Bitcoin is backed by hundreds of millions of people who hold bitcoin today, and bitcoin will eventually be backed by billions of people in the future. In order to change any of the fundamentals of bitcoin, such as increasing the number of bitcoin that will ever exist to some number beyond the hard cap of 21 million, you would need to get all of those people to agree to that change, and no significant number of people are going to agree to increase the number of bitcoin, because doing so automatically decreases the value of the bitcoin that they currently hold. All in all, bitcoin is an ingenious system that is backed by math, cryptography, a massive network of computing power, hundreds of millions of people, and so much more. It is truly amazing that something so incredible and so worldwide has grown to this size and scale in just 18 years. Other technologies that are now universal took much longer to reach even this early stage of adoption, and bitcoin is just getting started!
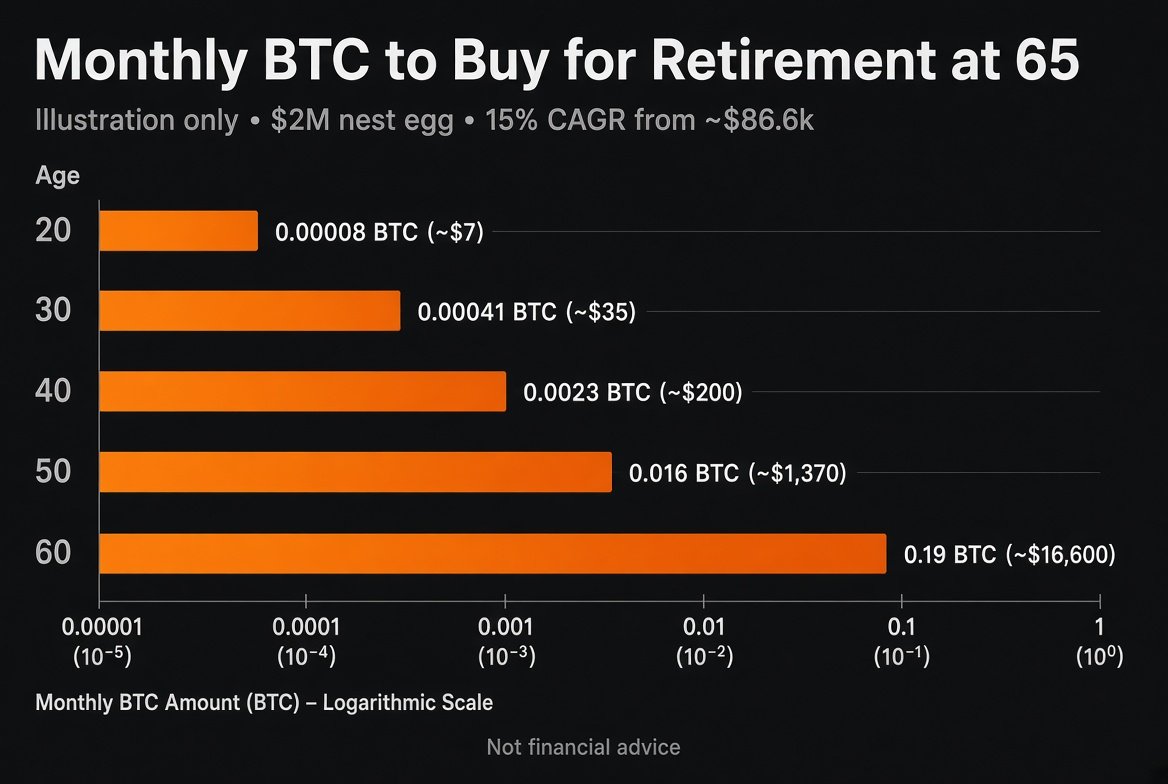
This is how much bitcoin:native you need to buy each month to retire at 65.
Assuming a $2M nest egg.
A 15% annual price growth from $86.6k and buying a fixed amount of bitcoin:native each month.
- Age 20:
0.00008 bitcoin:native/month ($7 today)
- Age 30:
0.00041 bitcoin:native/month ($35)
- Age 40:
0.0023 bitcoin:native/month ($200)
- Age 50:
0.016 bitcoin:native/month ($1,370)
- Age 60:
0.19 bitcoin:native/month ($16,600)
Younger buyers need far less total bitcoin:native because price has decades to stack.
Older buyers need a much larger stack in far less time.
The sooner you start the easier it would be.
Your Retirement Is Already DEAD.
You just don't know it yet.
You wake up. You check your portfolio. The number went up.
You smile.
You're compounding. You're winning.
You're doing everything the financial advisors in their Brooks Brothers suits told you to do.
Max out the 401(k). Dollar-cost average. Time in the market beats timing the market.
The S&P 500 returns 10% forever and you're going to retire at 65 with a boat.
You are being robbed in real-time and the number going up is the knife.
The Math That's Killing You
Listen.
The S&P 500 returns 9-10% nominal. Everybody knows this.
It's in every PowerPoint, every retirement calculator, every "invest for your future" ad with the couple walking on the beach at sunset.
M2 money supply grows at 6-7% forever.
Nobody tells you this. Nobody puts THIS in the commercial.
Do the math. 10 minus 7 equals 3.
You're getting 3%. That's it. That's what's left after monetary dilution.
And that's BEFORE:
The IRS takes their cut
Your fund takes their 0.5-1% fee
Inflation (the real kind, not the kind they admit to) eats what's left
Sequence-of-returns risk detonates your nest egg the moment you retire into a bear market
You're drowning in slow motion while someone keeps adding water to the pool and telling you you're swimming great.
The Retirement Equation Is Designed To Fail
Here's what retirement requires. Not what they tell you it requires. What it ACTUALLY requires:
Your capital must:
Grow FASTER than monetary dilution, AND
Generate spendable cash flow, AND
Do this WITHOUT being liquidated
A 3% real return cannot do this.
The "4% withdrawal rate" they taught you? That's based on 7-8% real returns. You're getting 3%. The math doesn't math. The equation explodes. Your retirement dissolves like flesh in acid.
This is why pensions don't exist anymore.
This is why they replaced them with 401(k)s and told you it was "freedom."
This is why retirement age keeps climbing.
This is why your parents are still working at 68.
The system is working exactly as designed.
You're just finally understanding what it was designed to do.
Money Printing Is A Weapon And You're The Target
M2 expansion doesn't hit everyone equally.
It's a shaped charge.
It detonates outward from the Federal Reserve and the banks and the primary dealers who get fresh money first, who can borrow at zero, who can lever up and buy assets before the prices rise.
By the time the new money reaches YOU - the wage earner, the saver, the person with a 401(k) - the asset prices are already up.
The cost of living is already up. You're always buying at the top with diluted dollars.
This is monetary gravity.
You cannot escape it by working harder.
You cannot escape it by being smarter.
You're on the wrong side of the money printer and the printer doesn't stop.
You think the S&P 500 protects you from inflation.
It doesn't.
The S&P is:
Priced in the SAME dollars being diluted
Full of companies whose profit margins compress when costs rise
Subject to valuation multiple compression when rates rise to fight the inflation the money printing caused
The S&P reacts to money printing. It does not transcend it.
When they print, your stocks go up. You feel rich. Then healthcare goes up. Housing goes up. Education goes up. Insurance goes up. Your retirement number goes up.
The goalposts move faster than you can run.
Why It Feels Wrong
Your portfolio shows $500,000. Then $750,000. Then $1,000,000.
You should feel wealthy. You don't.
Because a house that cost $200,000 now costs $600,000.
Because healthcare that cost $500/month now costs $2,000/month.
Because the retirement calculators that said you needed $1 million now say you need $3 million.
The number goes up but the finish line moves faster.
This is not your failure.
This is not because you didn't work hard enough or save enough or invest smart enough.
This is arithmetic. This is monetary physics.
This is what happens when the money supply grows at 6-7% forever and your returns can't keep pace.
If M2 grows at 6-7% forever, then:
Any asset growing below that rate is shrinking in real terms.
Any retirement plan based on 10% nominal returns is a lie told in a language designed to confuse you.
Any system that requires you to liquidate your capital to survive guarantees you will die poor or die working.
This is why retirement feels impossible.
This is why you feel trapped.
This is why people in their 60s with seven-figure portfolios are still working.
The math doesn't work. It never worked.
It was never supposed to work for you.
The money printer is on. It will not turn off.
Not for your retirement. Not for your kids' college.
Not for anything.
And every day you believe the 10% return fantasy is another day you don't prepare for what's actually coming.
Buy Bitcoin. It is a moral imperative for you and your bloodline.
⚠️ The Bitcoin cycle is testing us HARD right now...
We’ve heard it all:
Tether FUD
Saylor is selling?
OGs are giving up...
This is usually the time when people make dumb mistakes.
But you're not one of those people.
Because you came across this video.
💥 THE EXIT MANUAL – EPISODE #16
Watch someone buy a $1,750,000 pizza. In this 2010 video, a YouTuber explains how to pay for pizza using Bitcoin and records themselves spending coins that were worth only a few cents at the time.
You rant about money printing.
But when someone asks how the system actually works?
You stumble.
You can't explain the mechanics.
The cantillon effect.
Fractional reserves.
Debt-based creation.
I broke it all down simply in this article.
If you're ready to articulate it like a pro:
Read this.
https://t.co/Ulk2yBD74f
🚨Your daily reminder
Inflation is a wealth-transfer machine from the poor and middle-class to the rich.
It’s not an accident. It’s a feature of the system.
Ending inflation would be the single BIGGEST tax on the rich and the greatest relief for the poor.
So why won’t anyone fix it?
1. The state relies on inflation as a stealth tax. It quietly erodes your savings while helping governments shrink their debts without ever admitting it.
2. The already-wealthy love inflation.
Their assets rise faster than prices. They get richer by doing nothing.
3. Left-wing parties refuse to confront it because their economics require more spending, more debt and more money creation. Fixing inflation would expose the flaws in their entire model.
4. Right-wing parties won’t fix it either because they’re terrified of the political cost of discipline.
5. Central banks won’t fix it because inflation is their tool and ending it would mean admitting that decades of policy have failed.
Inflation isn’t a technical glitch.
It’s the biggest legalised theft in our economy and we’ve normalised it.
Bitcoin will eventually trade for
• 200,000 USD
• 500,000 USD
• 1,000,000 USD
• 10,000,000 USD
• 100,000,000 USD
- 1,000,000,000 USD
etc.
Here's how it will happen:
(THREAD 👇)
Buy every dip.
The US can’t afford falling asset prices. Stocks are the retirement system and the tax base. If markets drop, the system breaks.
QT is over. Rate cuts, QE, deregulation, stimulus and housing relief are next.
No matter what they say, remember: they have to print.