Me: “I’m not good enough.”
Jesus: “I know.”
Me: “I can’t stop sinning sometimes.”
Jesus: “I know.”
Me: “I’ve failed You more times than I can count.”
Jesus: “I know.”
Me: “I don’t deserve Your love.”
Jesus: “You’re right.”
Me: “Then why would You save me?”
Jesus: “Because I came to save sinners.”
THAT is the good news of the gospel.
Jesus didn’t come for people who had their lives together. He came to save sinners who could never save themselves.
You don’t earn His love by becoming good enough. You don’t pay Him back by becoming perfect. You don’t make yourself righteous through your own efforts.
Christ lived the perfect life you could never live. He died the death your sins deserved. He paid the debt you could never repay. And He rose again, conquering sin and death.
While we were still sinners, Christ died for us (Romans 5:8).
We were guilty. He was innocent.
We were unrighteous. He was perfectly righteous.
We owed the debt. He paid it.
And through faith in Him, we are justified—not because of our righteousness, but because of His.
This doesn’t mean sin no longer matters. It doesn’t mean we make peace with our sin or use grace as an excuse to keep rebelling against God.
It means our hope is not in our ability to be perfect. Our hope is in the One who already was perfect on our behalf.
🚨 A New Payment System Will Launch In The United States of America.
David Sacs said it openly in front of President Trump.
And guess what?
President Trump said that they will rewire the entire banking and financial system with blockchain technology.
Guess who also said that exact phrase before President Trump? @bgarlinghouse and @JoelKatz.
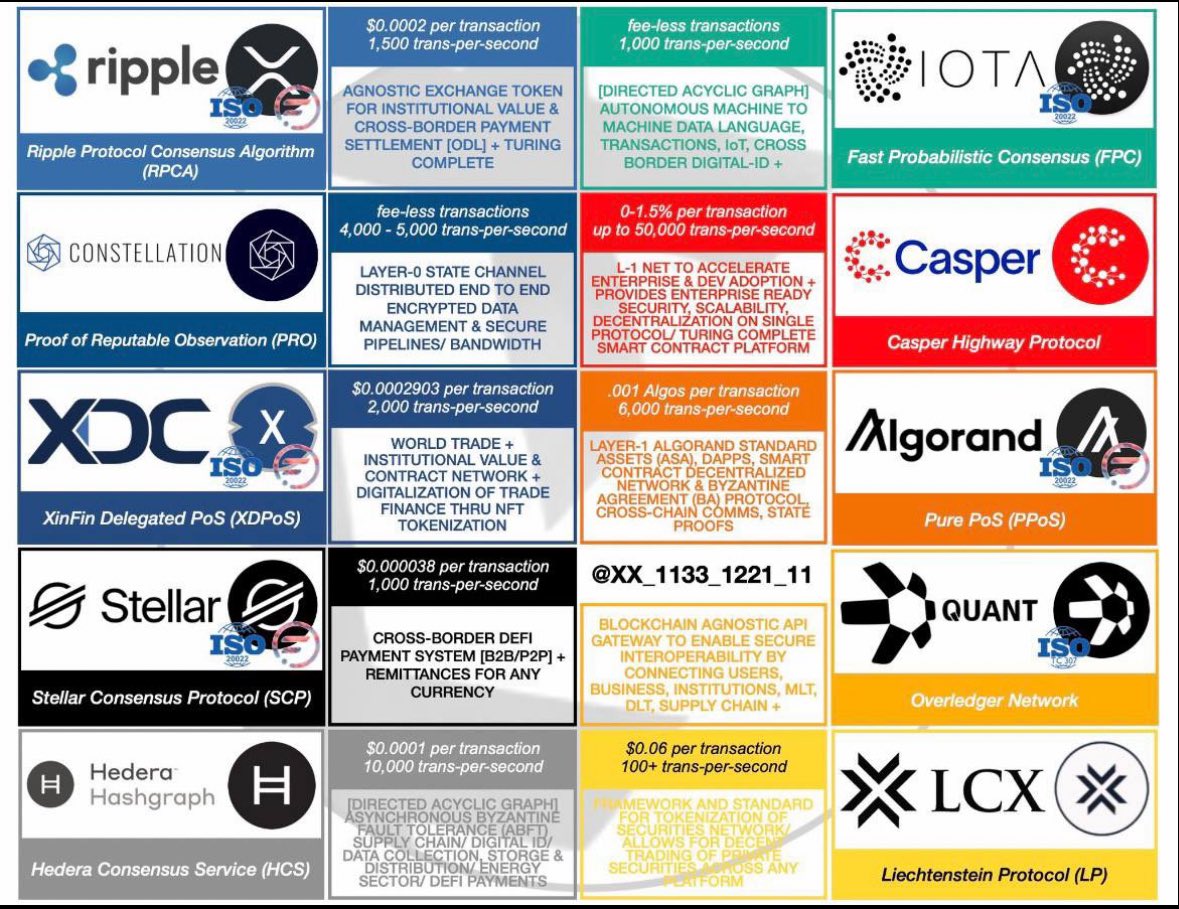
They’ve been hinting at mass adoption for XRP and RLUSD!
🚨‼️Marriage is not two people promising perfection; it’s two sinners promising forgiveness. That’s why the modern world is terrible at it. They want Disney romance without Calvary sacrifice. They want chemistry without covenant, intimacy without responsibility, and compatibility without sanctification. That’s not marriage, that’s romance marketing.
A Christian marriage is a workshop, not a honeymoon suite. God uses it as a forge to temper pride, selfishness, impatience, and rebellion. Husbands learn to lead by dying; wives learn to follow by trusting; both learn to love by forgiving. The Devil hates that forge, because the hammering makes saints out of sinners.
The world says “find someone who completes you.” The Bible says “find someone who sharpens you.” Sparks fly in a forge, not in a fairy tale. A Christian spouse isn’t a soulmate who eliminates problems; they’re a helpmeet who exposes them so grace can solve them. If that sounds unromantic, you’ve never tasted the romance of the cross.
A good marriage is not built on compatibility, but on covenant. Compatibility changes with chemistry and circumstances; covenant holds when chemistry evaporates. When two believers anchor to Christ rather than emotions, storms stop being threats and start being testimonies. That’s God’s design, not easy, but eternal.
Time to quiet the noise.
So what IS actually holding up adoption?
Not law.
Not the Clarity Act.
Not “banks being scared.”
What’s slowing visible adoption is institutional sequencing.
Infrastructure always scales in this order:
1) Legal survivability ✅
•XRP survives court scrutiny
•Secondary market sales not securities
•No injunction on usage
Done.
⸻
2) Regulatory lane assignment ✅
•XRP treated as commodity-like in practice
•CFTC jurisdiction for derivatives
•CME futures live / launching
•Eligible for institutional risk frameworks
Done.
⸻
3) Plumbing build-out ✅
•Custody
•Prime brokerage
•OTC liquidity
•Treasury rails
•Stablecoin cash leg (RLUSD)
This is what Ripple spent years building quietly.
Mostly done.
⸻
4) Risk committee sign-off ⏳
(This is the bottleneck)
Banks move slowly because:
•Every corridor = new counterparty risk
•Every flow = new compliance review
•Every scale-up = balance sheet exposure
This phase is:
•Slow
•Quiet
•Bureaucratic
But once approved → flows scale fast.
⸻
5) Public visibility ❌ (last, not first)
Institutions never announce:
•Live settlement routes
•Treasury movements
•Liquidity strategies
This isn’t a sing-along.
Visibility comes after stability.
Retail sees the end, not the beginning. No participation ribbons.
⸻
So… can we prove XRP is being used?
Yes — just not the way retail expects.
Here’s the proof stack ⬇️
⸻
PROOF TYPE #1 — On-Demand Liquidity (ODL)
This is not theoretical.
Ripple’s ODL:
•Uses XRP as a bridge asset
•Is live in *multiple* corridors
•Replaces pre-funded nostro accounts
This is documented in:
•Ripple quarterly reports
•Earnings calls
•Partner bank disclosures
You don’t see volumes tick on Binance because:
•XRP is sourced OTC
•XRP is held briefly
•XRP is recycled fast
That’s exactly how settlement works.
How it’s Supposed to work. How it’s Designed to work.
⸻
PROOF TYPE #2 — Corridor behavior (the tell)
Look at:
•Mexico
•Philippines
•Brazil
•Asia-Pacific routes
These corridors show:
•Consistent XRP liquidity demand
•Low retail participation
•Stable turnover
That’s not speculation.
That’s payment flow behavior.
⸻
PROOF TYPE #3 — Institutional infrastructure alignment
Ask yourself why these exist now, not 5 years ago:
•Prime brokerage (Ripple Prime)
•Institutional custody
•OTC desks scaling XRP inventory
•CME futures
•Tokenized treasury integrations
•RLUSD as programmable cash leg
Institutions don’t build this stack for meme coins, maybes, or hopefuls.
They build it for settlement scale.
⸻
PROOF TYPE #4 — Silence itself - This is the one retail really hates.
If XRP were not being used:
•You’d SEE aggressive marketing
•You’d SEE incentive programs
•You’d SEE hype to attract liquidity
Instead, you SEE:
•Delayed press releases
•Back-dated announcements
•Minimal price commentary
•Focus on rails, not charts
You HEAR about the NDA’s.
That’s institutional posture.
⸻
The Uncomfortable Truth
Note: Read this Twice 👇
Adoption doesn’t stall because institutions can’t use XRP.
It stalls because institutions won’t scale until volatility drops and liquidity deepens.
ENTER ETF’s.
They want:
•Predictable spreads
•Tight volatility bands
•Deep OTC books
•No front-running risk
The phase that comes right before repricing?
Right here baby.
⸻
The Champ Doesn’t Bark
They’re Not Boisterous
They Take Care of Business
•XRP is being used
•Usage ≠ speculation
•Settlement ≠ holding
•Institutions move quietly
•Visibility comes last
Nothing is “holding XRP back.”
It’s doing exactly what infrastructure assets always do:
•Build silently
•Prove stability
•Scale suddenly
It’s supposed to be…
Boring.
BY DESIGN.
Are you scared on $XRP price action right now? 🚨WATCH THIS!
In Q4 2016, $XRP got crushed in a brutal shakeout.
Price dropped to just $0.0054, then exploded to $3 in months.
That’s a 55,455% gain or a 554x. Insane, right?
It’s happening again. Today’s dump? Pure manipulation. Designed to shake you out.
But this time, it’s bigger.
Trillions are lining up behind $XRP:
• Spot ETFs now live
• Ripple driving real-world adoption (cross-border + tokenization)
• Strategic reserves by companies & countries
• Pro-crypto policy shift in the U.S.
• $XRP, an American-made asset, aligned with the next political wave pushed by President Trump
•Ripple's CEO and legal counsel are in talks with President Trump
Yet you’re scared of red candles?
Don’t be. I’ve done the research and I’m giving it to you straight. FREE!
I know what I hold. I know what’s coming to $XRP.
This is the generational wealth window you don’t want to sleep on.
I'm ready. Are you?
Repost for someone who needs to see it.
Follow for more no-BS truths.
‼️THE FINAL MIGRATION TIMELINE FOR ISO 20022‼️
SWIFT has split the last phase into 3 stages.🧩
We are right now in Phase 2 : The Coordinated Global Migration Window.⏳
• Phase 1 — Operational Readiness
ISO 20022 goes fully live on 17 November 2025.⏰
Systems across the network reach full readiness.
Banks confirm infrastructure, testing, and capacity.🏦
• Phase 2 — Coordinated Global Migration Window
This runs from 17–24 November.🗓️
Europe Asia and the United States are executing synchronized migration steps. 🌎
Everyone is aligning systems at the same time.🎚️
This is the global coordination phase happening RIGHT NOW.✅
• Phase 3 — Full Switch / Cut-Over
The switch hits on November 22.🎯
MT payment instructions stop being supported for live traffic.
Legacy MT messages begin getting rejected or converted under contingency.🙇♂️
Documented below.👇
SUPPLY SHOCK IS COMING!🔥
Forget the $750 price prediction of Jake Claver for this year—it's too soon.
The major price pump is expected in March 2026. That's when the transition of private and public ledgers will happen, creating a supply shock that will drive the price up.🚀
Evernorth is basically MicroStrategy—but built for $XRP from the ground up.
And here’s why that matters for price.
When a publicly listed company or a regulated fund accumulates an asset on the open market, every purchase adds real demand. There’s no pre-mine, no discount, no OTC sweetheart deals. It’s market-rate buying pressure that tightens supply.
Evernorth has already said their treasury company will buy XRP directly from exchanges, not through private allocations.
That’s rare. Most institutional vehicles negotiate discounts; Evernorth isn’t.
Every time they accumulate, the circulating supply that retail traders can access shrinks. Combine that with XRP’s fixed supply and suddenly small waves of demand can move price much faster.
But it’s not just buying pressure.
They’re also creating utility: liquidity pools, lending, and yield programs built around XRP as the base asset.
More on-chain use = more transaction volume = more reason for institutions to hold XRP for settlement.
Now imagine what happens when Evernorth lists on Nasdaq.
Wall Street traders, pensions, and ETFs can get regulated exposure to XRP by buying Evernorth shares—capital that previously couldn’t touch crypto directly.
That flow of fiat liquidity has to be hedged somehow. Where do you think Evernorth goes to maintain its treasury ratio?
Right—back into XRP on the open market.
So you’ve got:
Real market accumulation
A shrinking float
Growing utility on the XRPL
Fresh institutional capital entering through Nasdaq
Those are the same ingredients that pushed Bitcoin from a few hundred bucks to tens of thousands once MicroStrategy and others started stacking.
Only this time, it’s being done legally, transparently, and with the explicit intent to grow the XRP ecosystem.
Whether you’re an investor, a trader, or just watching from the sidelines, this setup isn’t random price action—it’s infrastructure turning into demand.
And that’s the kind of alignment that historically sends charts vertical.
https://t.co/I1ZNLRMnE5
What do $XRP and ISO 20022 have in common?
One is built for ultra-fast payments.
The other is the new language of global finance.
Spoiler: they’re made for each other.
And July 14 is a key date. 🧵👇
🚨 As a former mortgage banker, let me be VERY clear:
The FHFA just issued a directive for Fannie Mae & Freddie Mac to begin considering cryptocurrency as an asset in mortgage risk assessments, without converting to USD.
This is MASSIVE.
We’re talking about the 2 giants that hold over $7 TRILLION in housing loans now prepping to allow digital assets as reserves for single-family loans.
You will soon be able to use your crypto stack as part of your home loan qualifications.
No more "sell to qualify."
No more "crypto doesn’t count."
This opens the floodgates for TRUE adoption and marks the beginning of a tokenized housing market backed by the U.S. mortgage system.
This isn’t speculation.
This isn’t hopium.
This is POLICY.
And it’s effective immediately.
#KWYH #XRP #Crypto #HousingMarket #DeFi #BullishAF #SuperCycle