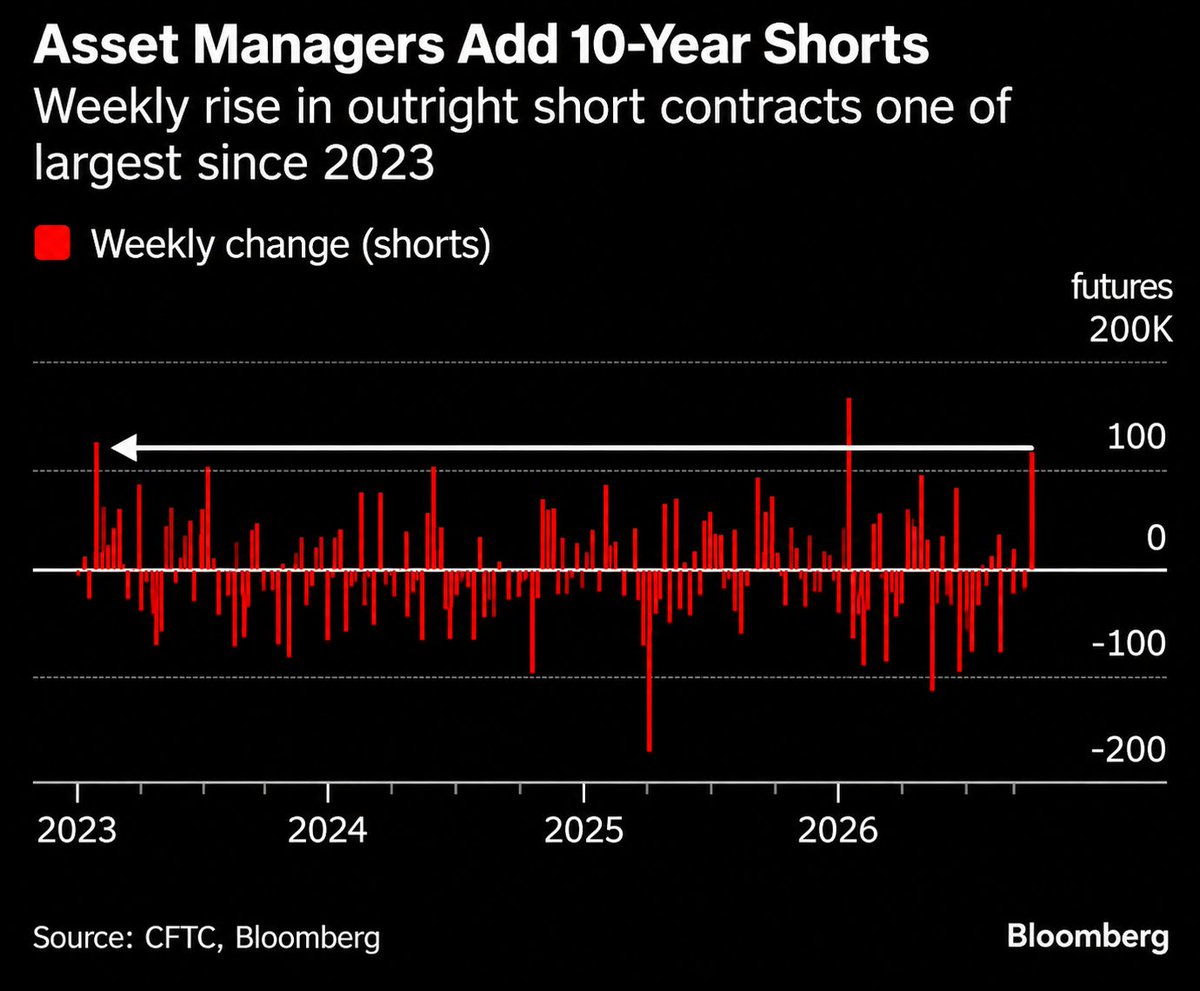
Treasury short positioning is EXPLODING HIGHER:
Asset managers added more than +100,000 10-year Treasury futures short positions in the week ending September 22, one of the largest weekly increases since early 2023.
This comes as investors continue positioning for higher Treasury yields, with 10-year futures open interest rising in 13 of the last 14 trading days and 5-year contracts in 11 of the last 12 sessions.
Across both maturities, the amount of futures risk added since the start of last week totals ~$32 million per 1 basis point, equivalent to ~$75 billion of the current 5-year Treasury note.
The bearish positioning has intensified as the 30-year Treasury yield reached 5.65%, its highest level since 2002, with elevated energy prices adding to inflation pressures and heavy government and corporate debt issuance weighing on the world's largest bond market.
Meanwhile, some institutional market participants see 6% on the 30-year yield as a possible scenario over the next several months, meaning the short positioning could continue if yields move higher.
However, the growing concentration of short positions is also increasing the risk of a Treasury futures short squeeze if upcoming inflation or employment data are unexpectedly weak, or if Fed officials deliver more dovish signals.
The Treasury market is becoming increasingly crowded on the short side.