Model portfolios are becoming easier to scale, but harder to distinguish.
With active ETFs now in half of advisor models, the shift goes beyond adoption. Active strategies are becoming core building blocks, giving advisors more ways to address index concentration, diversify exposures and differentiate portfolios without sacrificing scalability.
Main Management CEO/CIO Kim Arthur shares his perspective alongside Elise Terry of @BlackRock and Ty Peebles, CFA of @WestEndAdvisory in a new Barron's Custom Content sponsored feature exploring what this evolution means for advisors and the future of portfolio construction.
Read the feature: https://t.co/oAiAEyxKg8
September added just 29,000 jobs and July was revised back into negative territory, yet participation climbed to 61.8% as people came back into the labor force, which is why this report reads very differently depending on which page you stop on.
Full breakdown on our YT: https://t.co/CTAJJ8sucl
After 65 straight months of core inflation above the Fed's 2% target, markets more than doubled the odds of an October hike in a single week, from 27% to about 58%.
What is keeping inflation sticky even with oil down 7%? Watch our latest Weekly Market Commentary to find out: https://t.co/KPMEvMTKr9
#Inflation #FOMC #Fed #InterestRates #CorePCE #Macro #Market
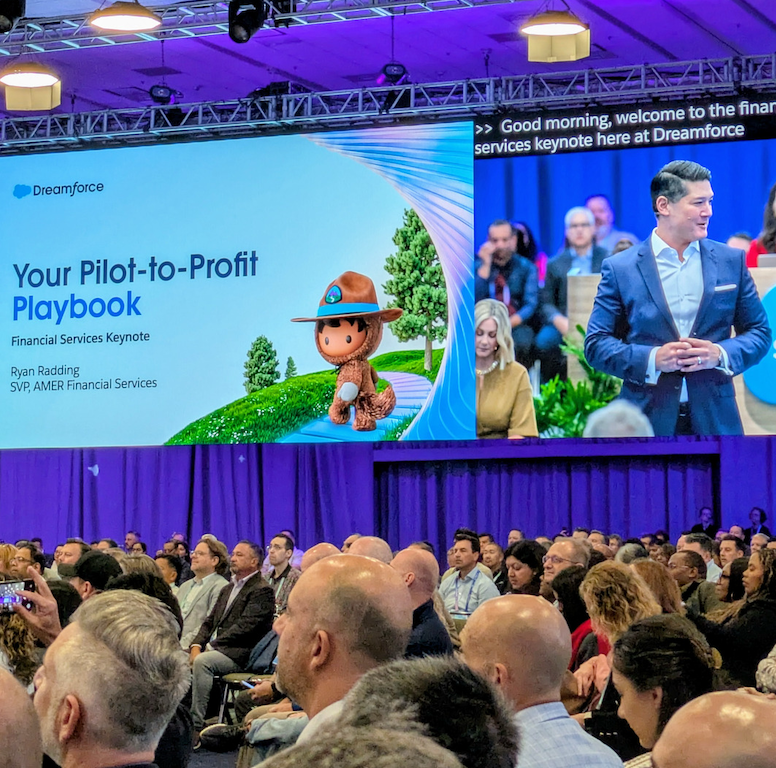
With @Dreamforce in our backyard this year, it meant a front-row seat to where AI in financial services is headed next.
Our lens was simple: where can this rapidly evolving technology help us work smarter and create more capacity for advisors, while strengthening the judgment, interpersonal relationships and partnerships that define Main?
Thanks for having us @salesforce for three days of ideas, innovation and plenty to bring back to HQ.
Diesel just hit an all-time high of $5.97 a gallon while core inflation sits at its lowest level since March 2021, which is a stranger combination than it sounds and the reason this week's Fed meeting is getting so much attention.
Full breakdown: https://t.co/2LxlZ3Gzxc
The August jobs report was strong enough that hike probabilities rose on the release, and weak enough underneath to complicate the picture: payrolls tripled forecasts at +162k, while hiring announcements ran 57% below normal and wage growth slowed to 3.09%.
That could leave inflation as the deciding factor for the Fed, so it's worth knowing where the labor data actually stands before Friday's CPI.
Our research team, led by @afvarner, walks through these considerations and more in our full Weekly Market Note episode: https://t.co/ybGPOh3Aey
As Main has grown, so have the ways we partner with and support our clients. Our new websites makes it easier to see what that partnership looks like in practice. The new https://t.co/oOLCzqjCz0 & https://t.co/WvYh13N0JY are live.
This new experience is designed around the people who use it: advisors, institutions and family offices seeking a clearer view into how we invest and the philosophy, perspectives and people behind our approach.
A few highlights to explore:
• Clear, plain-language overviews of all our strategies, where each one could potentially fit and the deeper thinking behind them:
• Resource Portal with current fact sheets, quarterly letters and presentations for every strategy, plus our latest research & market commentary, all in one place: https://t.co/GpC1sbBgm1
• Our new Events calendar featuring the latest opportunities to engage with Main, including our Advisor Summit Series, a two-day on-site due diligence experience at our San Francisco office with the core teams behind the strategies. https://t.co/W1Qi2cqzuW
Main Management has been a partner-owned, independent asset manager since 2002, and one of the early pioneers of ETF portfolio management.
Explore our new homepage and discover more of what’s behind Main Management here: https://t.co/zA4y6J0pff
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
• Fed Outlook: CPI surprised to the upside, but markets still price a 95% chance of a cut at Wednesday’s FOMC. SEP projections and language will guide the path ahead.
• Inflation: Headline and Core CPI hit their fastest pace since January. Shelter cooled, but food and tariff-driven goods inflation picked up.
• PPI: Deflationary at -0.12% MoM, driven by margin compression—raising the risk of future pass-through pricing.
• Business & Consumers: NFIB optimism hit its best since January, while Michigan Sentiment slid as long-term inflation expectations rose.
• Housing: Mortgage rates dipped to ~6.5%, lifting applications to their highest since 2022. A “five handle” could unlock more buyer demand.
Watch the full episode and hear how these trends shape the macro outlook in the latest Weekly Market Commentary: https://t.co/Pshg0N8hsX
Main Management is pleased to share that the Net Expense Ratio of the Main BuyWrite ETF (BUYW) has been reduced to 0.99%, effective immediately.
“Lowering BUYW’s Net Expense Ratio to 0.99% encompasses our mission: Put clients first, deliver exceptional service, and manage what we can control, with the goal of allowing investors to keep more of their potential returns.” - Darol Ryan, Managing Partner at Main Management
We invite you to read the latest press release for full details: https://t.co/JCbp1vSlbc
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
• Jobs: Payrolls rose just 22K, with June revised negative (the first decline since 2020). JOLTS, ADP, and job cut data all confirm a softer labor market.
• Participation & Unemployment: Prime-age participation hit a post-2024 high, while U3 and U6 unemployment climbed to their highest since 2021.
• Fed Outlook: Weak jobs data boosts odds of a September cut—90% for 25bps, 10% for 50bps—pending CPI/PPI this week.
• Productivity & Costs: Q2 productivity surged to 3.3% (best since 2023), while unit labor costs eased.
Watch the full recap and hear how these trends shape the macro outlook here: https://t.co/S5UDR8R6SY
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
- GDP revised up to 3.3%
- Corporate profits rebound, margins steady
- Durable goods & capex show strongest gains in years
- Consumers spend more than inflation, energy costs decade-low share
- Housing prices soften, hinting at affordability
Watch the full recap and hear how these trends shape the macro outlook: https://t.co/qZxKV7buVT
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
- Markets Move Higher: Broad strength across equities, led by small caps and healthcare. Tech and communication services cooled after leading much of the year.
- Fed Policy Shift: Powell’s Jackson Hole speech interpreted as dovish, with markets now leaning toward a 25 bps rate cut in September.
- Housing Strain: Existing home sales up, but high prices and rates keep the market tight. Inventories at highest since 2016; permits slowing sharply (lowest since mid-2020).
- Global Manufacturing Revival: U.S. PMI hits highest since 2022 (53.3), India strongest since 2009. Europe improving but still near contraction. Services more mixed, though U.S. remains solidly in expansion.
Watch the full recap and hear how these trends shape the macro outlook: https://t.co/mb11X3iW6a
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
• Markets mostly green: Europe leads (+27% YTD); small caps and healthcare show strength, signaling broader rotation
• Inflation pressures: CPI in line (+0.2% headline, +0.3% core MoM); tariffs lift durable goods; PPI +0.9% MoM, biggest since March 2022
• Fed at a crossroads: Weak payrolls suggest easing, but hot inflation pressures tightening; September FOMC likely contentious
• Consumer resilience: Retail sales +0.5% MoM, June revised higher; autos and furniture rebound despite tariff uncertainty
• Industrial production mixed: Output soft, but AI-driven high-tech demand boosts semiconductors to strongest growth since 2021
Watch the full recap and hear how these trends shape the macro outlook: https://t.co/oOP37IZB3d
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
- Markets climb: S&P +2.5%, led by Consumer Discretionary & InfoTech. Healthcare and Energy slip into negative YTD.
- Trade gap narrows: Deficit at $60.2B, lowest since Sept. 2023. Imports (-3.7%) and exports (-0.5%) ease post-tariff surge, with U.S. businesses absorbing most costs via margin compression.
- Productivity rebounds: Q2 +2.4% QoQ, best output growth since Q3 2023. Manufacturing logs 5 straight quarterly gains.
- Debt rises, delinquencies tick up: Household debt hits $18.4T (+$185B QoQ). Severe delinquency rates edging higher but remain below long-term medians.
- Mixed manufacturing & credit: Factory orders fall on transport volatility; ex-transports +0.4%. Consumer credit growth accelerates, driven by non-revolving loans.
Watch the full recap and hear how these trends shape the macro outlook: https://t.co/DIKzAap2YE
This week’s Market Note with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers:
- Business Survey Data: NFIB expectations and capex plans tick higher despite headline slippage.
- Bitcoin: Quietly making record highs.
- Copper: Futures jump on talk of tariff risks, flagging cost pressure.
- S&P 500: Dividend yield near a 150-year low as dynamics have shifted.
- Inventories: Durable-goods stockpiles post their steepest drop since 2020.
Watch the full recap and hear how these trends shape the macro outlook: https://t.co/vHMRBsDmws
“Trust, transparency, and true partnership.”
In this candid conversation between Kim and @RustyVanneman , Main Management’s new Advisory Board Chairman Rusty Vanneman, CMT, CFA, BFA™ shares why joining Main Management was an easy decision — and what sets the firm apart after decades of due diligence across the industry...
This is a must-watch and/or listen episode: https://t.co/mp8X8J5WNy
This week’s Market Note conversation with Alex Varner (Head of Research) and James Maxwell (VP of Research) covers a full slate of developments across geopolitics, Fed policy, and key macroeconomic data...
Click here to watch the full episode for in-depth insights on what’s driving markets and where things may be headed next: https://t.co/9e3tQJ2EnG
Highlights include:
- Israel–Iran tensions escalate, pushing oil and energy prices higher
- FOMC holds rates steady; projections still call for two cuts in 2025 despite weaker GDP and rising inflation expectations
- Retail sales, industrial production, and housing all show soft data as high interest rates and prices weigh on demand
- The U.S. deficit remains in focus, with spending outpacing revenue despite tax inflows
Looking ahead, the team previews key data to watch — including the final Q1 GDP release and the all-important Core PCE and consumer spending figures due Friday. Be sure to check back weekly for regular updates from the team at Main Management.