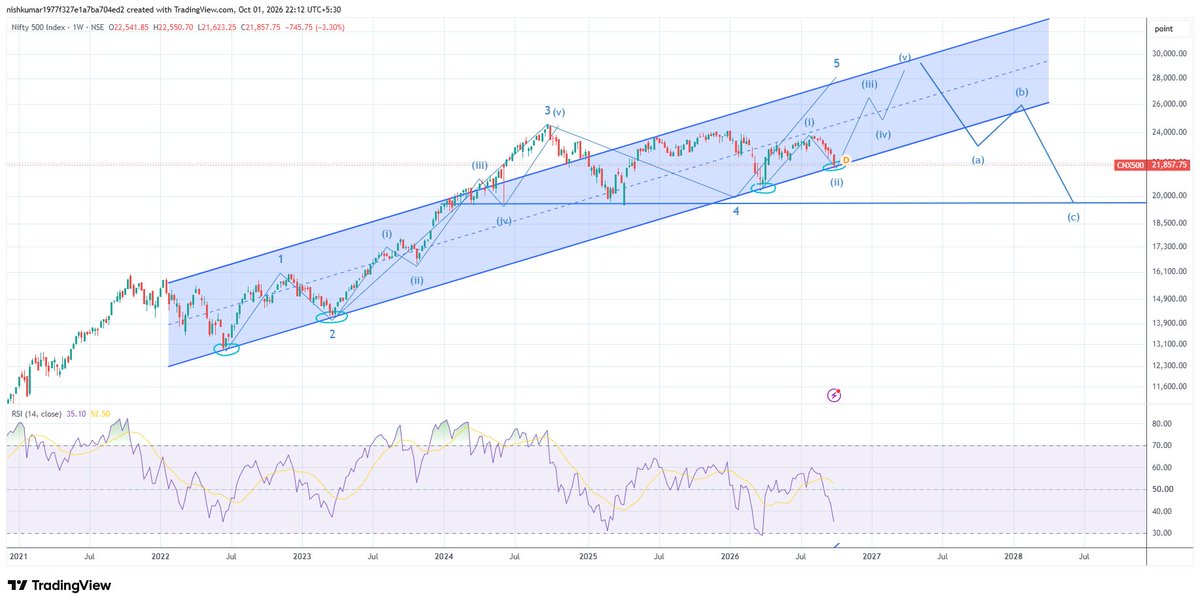
#Nifty500 21857
Weekly chart - One candle is one week
Every time the price has touched the lower end of this rising channel you know what happened. This week was the 4th time. I don't want to pass any judgements. Let's see if the charts speak!!
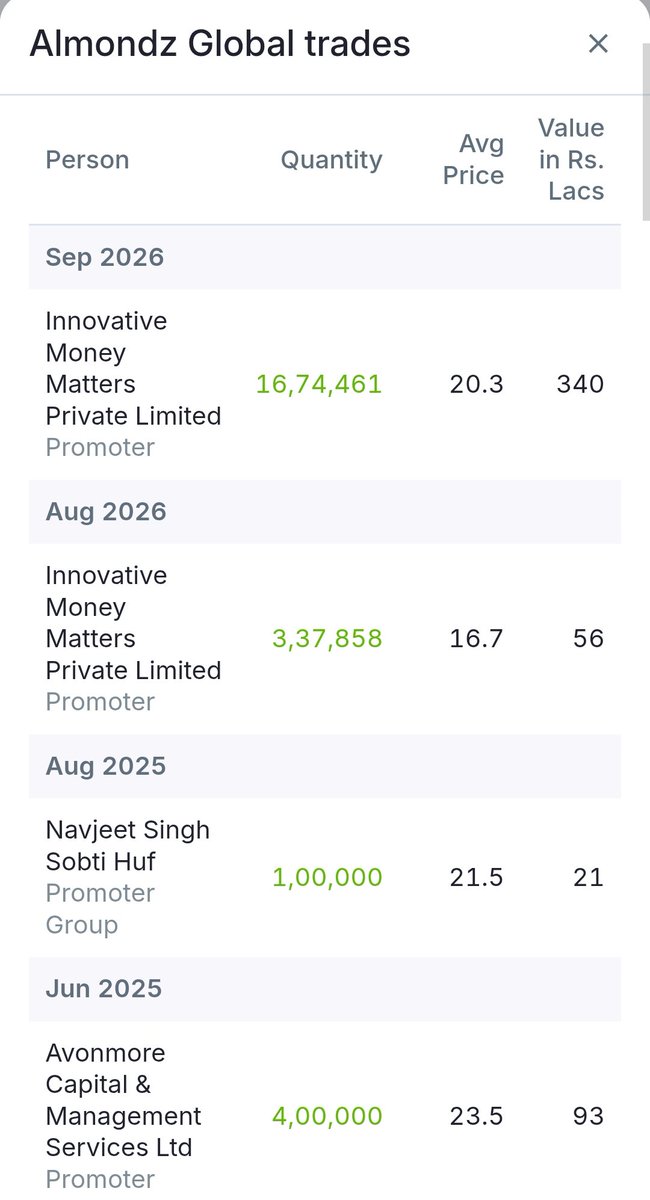
Dynamic Industries - 140
Mcap - 40 cr only
Chemical sector sector stock
Book value - 165
Those who knows History of chemical stocks returns will understand the undervalution here.
Company into Dye pigments manufacturing ���
🔥 Awfis Space Solutions Ltd ~ ₹293
Is India’s Flexible Workspace Story Entering Its Next Phase of Growth?
The more I study Awfis Space Solutions, the more interesting the business becomes.
Strong Q1 FY27:
Revenue ₹425 Cr, +27% YoY;
EBITDA ₹162 Cr, +28% YoY,
PAT ₹24 Cr, +140% YoY.
(but the sharp PAT growth needs some caution as other income contributed significantly to PBT)
Cash EBITDA – More Important Than Reported EBITDA
Management’s Q1 FY27 cash EBITDA was approximately ₹44 crore, up around 34% YoY, with a 10.1% cash EBITDA margin.
This is a useful metric to monitor because flexible-workspace businesses carry significant depreciation due to fit-outs and leased assets.
I would track:
Revenue → EBITDA → Cash EBITDA → Operating Cash Flow
rather than PAT alone.
Business momentum remains healthy: Coworking revenue grew 27%, while Transform grew 25%.
Scale-up continues: 251 centres, ~170,000 seats across 18 cities and ~3,600 clients; overall occupancy 76% and mature-centre occupancy 83%.
GCC/enterprise demand is a major growth driver, with 100+ GCC clients contributing ~24% of rental revenue.
Premiumisation is interesting: New premium inventory could command 30–50% higher pricing, potentially supporting future revenue and margin expansion.
Capital efficiency is attractive:
ROCE around 55% and net debt/equity around –0.08x, indicating a net-cash position.
FY27 guidance:
Revenue >₹1,800 Cr, cash EBITDA ₹190–200 Cr, 22,000–25,000 gross seat additions and ~20% growth in Transform.
Key risks:
Occupancy ramp-up, lease-related margin pressure, execution of new centres and ensuring that profit growth increasingly comes from core operations rather than other income.
The real long-term thesis is not simply about adding desks.
It is:
More centres → more seats → higher occupancy → premiumisation → higher revenue per seat → operating leverage → stronger cash generation.
If management can execute this cycle while maintaining high ROCE and keeping the expansion capital-light, the business has the potential to compound at an attractive rate.
Personal View:
The more I study Awfis, the more interesting the business becomes.
It is evolving from a conventional coworking operator into a diversified workplace platform with exposure to flexible offices, enterprise clients, GCCs, premium managed workspaces and design & build.
What particularly stands out is the combination of 27% revenue growth, 55% ROCE, improving occupancy at mature centres, premiumisation and a relatively capital-light expansion strategy.
The key metric I would track over the next few years is not just revenue growth, but whether Awfis can simultaneously increase occupancy, revenue per seat, cash EBITDA and ROCE while maintaining balance-sheet discipline.
Personally, I’d love to see Awfis emerge as one of India’s biggest workplace infrastructure platforms over the coming decade as India’s office market, GCC ecosystem and flexible-workspace adoption continue to expand.
Interesting company to track - but the valuation and quality of earnings need to be watched as closely as the growth.
(Not a recommendation. Please do your own research and due diligence after gaining adequate knowledge.)
Do anyone understand when I say, sales is 230 Cr, and Mcap is only 32Cr?
And profit making Co?
Auro Impex?
It means, one can buy whole Auro Impex and power ltd Co for just 32 Cr!!
Tumko 230 Cr sales karti Co, sirf 32Cr main milti hai...
Mcap is the Value of the Co and that is why I look at Mcap always.
Former Anthropic researcher Jacob Coxon’s warning on FOX should be a wake-up call:
“We know how to control nuclear weapons… We don’t yet know how to control AI.”
Nuclear weapons have physical, predictable limits. Advanced AI does not.
Sector to focus : Cyber security
@Sharad9Dubey Same thing with Greenpanel Industries.
Himnashu Jindal who was one of the key managements who turned around Orient Bell joined this company and has bought few qtys from open market!
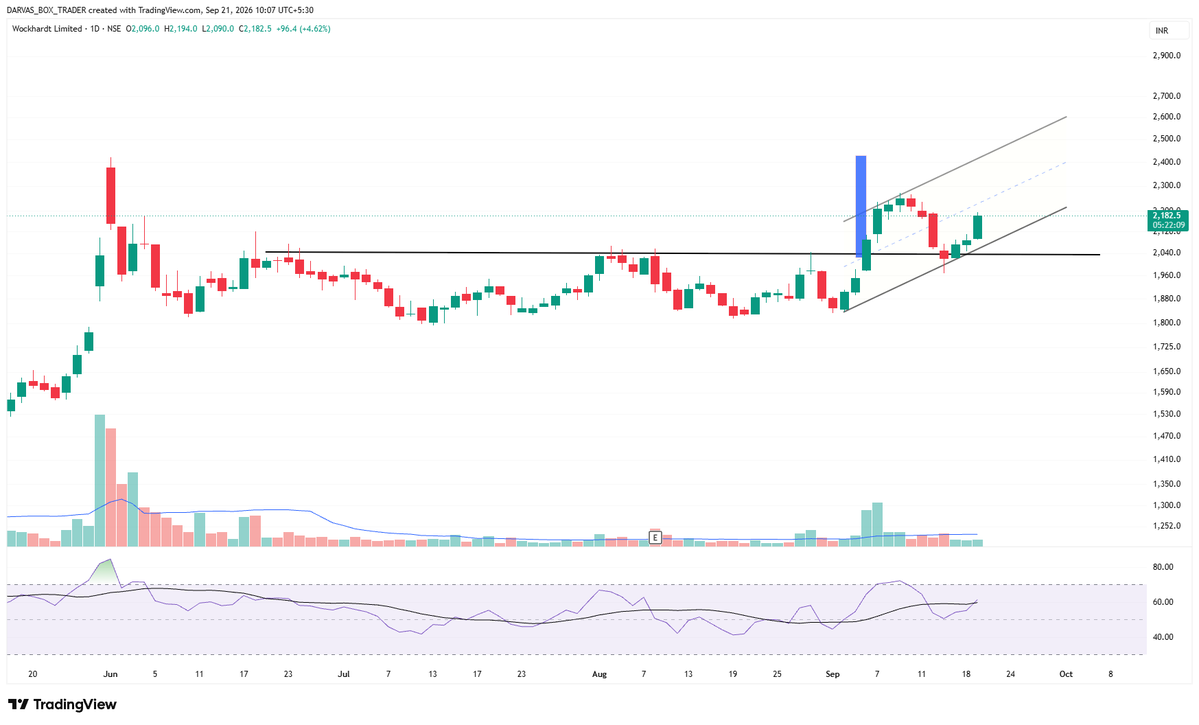
🚀 It’s time to make the Stock Screening process SIMPLE.
A small step towards making your Stock Market journey simpler, faster & more efficient.
I’m excited to announce the launch of our Stock & Sector Analysis Scanners , now available for everyone!
No more spending hours on deep research. ✍️
No need to go through 100s of charts. ✍️
👉 Just a few clicks to identify:
• Where the Smart Money is flowing
• Which Sectors are showing strength
• Which Stocks deserve your attention..
https://t.co/QylLeNlfSm
Guys, explore it. Hope you’ll love it! ❤️
#DARVAS 🥸