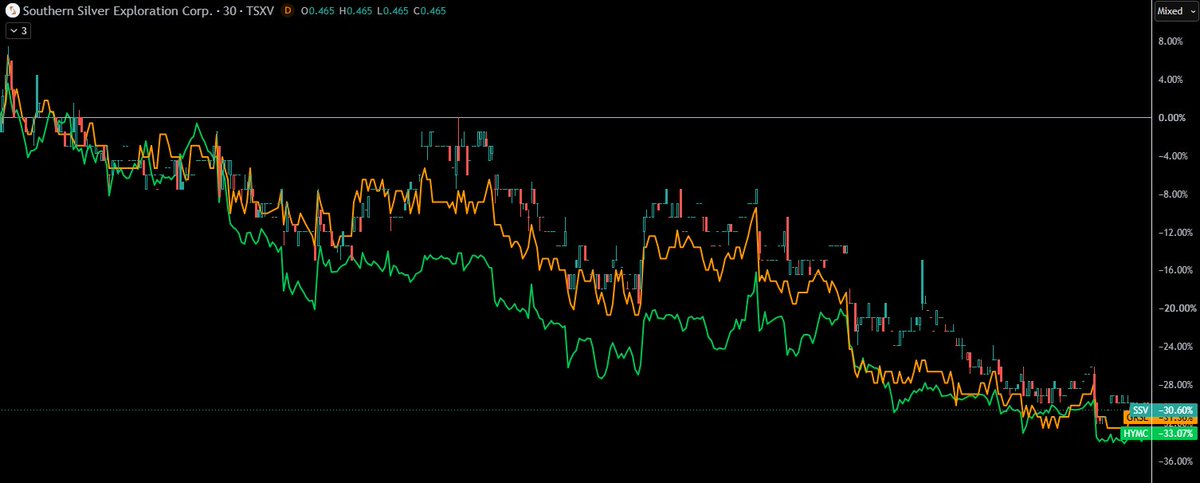
$SSV.V - Southern Silver
$GRSL.V - GR Silver
$HYMC - Hycroft Mining
3 bullrunners that is all more than -30% down since their AUG top.
All 3 are good buys from here.
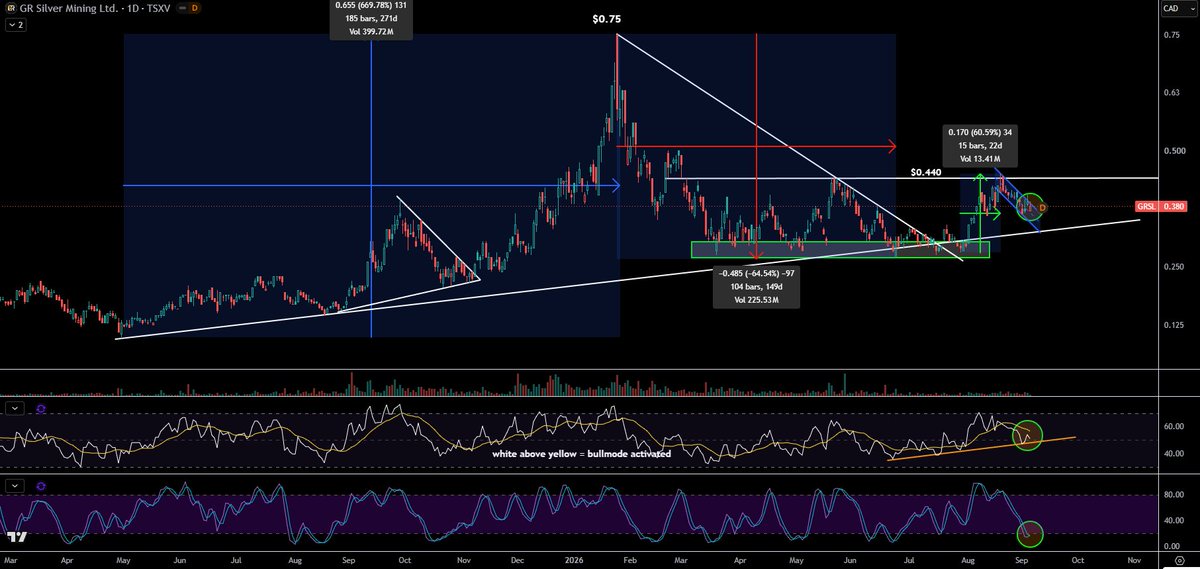
$GRSL.V - GR Silver Mining
Currently -37% from its recent intermediate high and entering a strong support zone around oversold levels.
I continue to claim GRSL is one of the best buys for the next intermediate upleg cycle. Any dips from here on out to be bought.
A good idea? Rotate out of $MGG.V here and rotate more into $GRSL.v. Thank me later when you see the upside next leg up.
#Silver
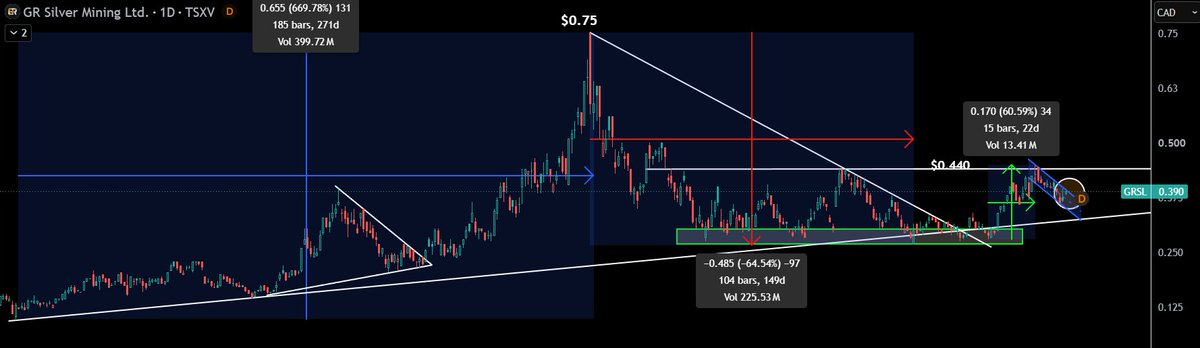
$GRSL.V - GR Silver Mining
Still a buy in my book. Next time we surpass $0.440 it will become a new floor I suspect.
Ideal entries are leaving, I can't tout BUY for much longer here.
As always, no financial advice, always DYODD.
GRSL is a top 6 holding for me right now. I expect a good run into New Years and a newsflow that surprises to the upside.
#Silver
Anyone watching what’s going on in the world right now should treat every single dip in #Gold and #Silver as a gift from above.
There is no other destination for precious metals than much higher.
We may be experiencing one step back, but I guarantee that what follows will be two steps forward.
Money printing and currency debasement are the only drugs that can keep the financial system running.
Rest assured, they will keep kicking the can down the road.
If you wanna make the most out of it, you buy the #silver mining stocks. They will skyrocket.
$GRSL.V - GR Silver Mining
There’s a saying in Sweden:
“Den enes död är den andres bröd.”
Literally translated: “One man’s death is another man’s bread.”
The real meaning is closer to:
“One man’s misfortune is another man’s opportunity.”
Those who sold $GRSL here, and I know why they did, created an opportunity for those of us willing to scoop it up.
I believe $GRSL will be one of the strongest performers during the next daily cycle upleg.
I’ve positioned accordingly.
Have you?
I still consider $GRSL a very good buy at these levels.
The passing of $GRSL.V founder and CEO Márcio Fonseca earlier this year was a tragic loss. He helped build this company, and his legacy lives on through the project and the people advancing it.
The #silver is still there. The geological potential remains. And the team doing the hard work on the ground continues to move the project forward.
Look at the monster bonanza hit reported in May from San Marcial, hole SMS26-04:
• 45.1 metres at 1,623 g/t silver
• Including 18.85 metres at 3,846 g/t silver
• Including 8.25 metres at 8,579 g/t silver
All reported as true widths. Those are silver grades alone, with additional lead and zinc.
For me, that is one of the most spectacular silver intercepts I’ve seen in years. The combination of grade and width is extraordinary. I believe its the best hole in the #silver market globally the past 5 years.. Not to be ignored.
With Eric Zaunscherb now leading the company, continued drilling, an updated resource estimate and a planned PEA provide a clear path toward demonstrating what this project could become.
I believe GR Silver has something very special taking shape. Márcio’s contribution deserves recognition, and the team carrying his work forward deserves attention.
#SILVER
I believe the precious metals #bullmarket, especially the rise in #Gold, will continue deep into the 2030s.
We have a large window to make an extraordinary amount of money.
This will not happen in a straight line. There will be violent corrections, false breakdowns and periods when people declare the bull market dead. A secular bull market is defined by increasingly higher cycle highs and lows, not by the absence of major drawdowns.
WHY:
THE FISCAL MATHEMATICS ARE BROKEN
The United States is running enormous deficits despite not being in a major recession.
#US public debt is already around 101% of GDP and is projected to reach approximately 120% by 2036. Interest costs are compounding and consuming an increasingly large share of government revenue.
#Europe, #Japan, #China and many emerging economies also face ageing populations, growing entitlement costs, military spending and heavy debt burdens.
Debt does not guarantee immediate money printing, but it gradually removes every politically acceptable alternative.
Eventually governments must choose between austerity, higher taxes, restructuring, inflation or financial repression.
History suggests they will choose currency debasement, negative real rates and periodic central-bank intervention.
#GOLD IS BEING REMONETISED
Central banks have accumulated approximately 1,000 tonnes of gold annually during the past four years, twice the average of the previous decade.
In the latest survey:
89% of central banks expect global gold reserves to increase.
45% expect to increase their own holdings.
74% expect the dollar’s share of global reserves to decline during the next five years.
Gold has no counterparty risk, cannot be printed, cannot default and, when stored domestically, cannot easily be frozen or sanctioned by another country.
Central banks are not preparing for the #dollar to disappear tomorrow. They are protecting themselves against excessive dependence on it.
DE-DOLLARISATION IS SLOW, BUT REAL
The dollar’s share of global foreign-exchange reserves has fallen from approximately 72% in 2001 to around 57% today.
This is diversification, not abandonment.
#BRICS represents more than a quarter of global trade and a much larger share of global population, commodity production and economic growth. Its members are gradually increasing local-currency settlement and developing payment infrastructure that reduces dependence on Western-controlled systems.
A common #BRICS #currency is unlikely anytime soon. It is also unnecessary.
Every transaction settled outside the #dollar, every bilateral payment connection and every additional tonne of #gold held instead of government debt weakens dollar concentration at the margin.
A complete replacement is not required to move gold substantially higher.
THE RESERVE-CURRENCY PARADOX
Global reserve demand structurally supports the dollar, makes #American imports cheaper and helps the United States finance persistent deficits.
But that same strength makes American manufacturing and exports less competitive.
If the United States seriously wants to reshore strategic production, rebuild its industrial base and reduce its trade deficit, it benefits from a weaker real exchange rate. (It is in their interest to see the dollar weaken.)
#America effectively wants the dollar to remain the centre of the financial system while becoming less expensive.
That is an extremely difficult balance to maintain.
The likely outcome is not the sudden death of the dollar. It is gradual erosion of its purchasing power while its financial network remains dominant.
WEAPONISING THE FINANCIAL SYSTEM HAS CONSEQUENCES
Freezing national reserves, expanding #sanctions, threatening #tariffs and using access to the dollar system as a geopolitical weapon give other countries a rational reason to create alternatives.
#Trump’s aggressive and transactional approach has accelerated that incentive, including among traditional American allies.
Tariffs, higher rates and global fear can strengthen the dollar temporarily. However, repeated coercion encourages countries to diversify their reserves and payment systems over the longer term.
You can force countries to use your system for a period of time. You cannot force them to trust it forever.
THE WORLD IS BECOMING MORE #MULTIPOLAR
Cheap drones, ballistic missiles, electronic warfare and precision weapons allow weaker countries to inflict enormous damage at a fraction of the historical cost.
This makes invasions, occupations and large troop concentrations considerably more dangerous and expensive.
Military superiority still matters, but the cost of enforcing geopolitical dominance is rising rapidly.
The United States will find it increasingly difficult to maintain the global order through coercion alone. It must compete through trade, alliances, investment and mutually beneficial agreements.
This military shift is not the main reason for gold’s rise, but it reinforces the transition towards a more fragmented and multipolar world.
#DEGLOBALISATION IS #INFLATIONARY
The previous global system prioritised efficiency and the lowest possible production cost.
The new system prioritises security.
Countries are reshoring factories, duplicating supply chains, stockpiling strategic materials, rebuilding #militaries and investing in #energy independence.
At the same time, the world needs enormous investment in electrical grids, data centres, #AI infrastructure, defence, #nuclear energy, renewable power and transportation.
These projects require vast quantities of metals, energy, labour and capital.
A less efficient and more fragmented world is structurally more inflationary, which is favourable for scarce real assets.
GOLD SUPPLY CANNOT RESPOND QUICKLY
New mines often require more than a decade to move from discovery into production.
The industry faces declining grades, permitting delays, political risk, environmental restrictions, higher construction costs and shortages of skilled labour.
Even dramatically higher gold prices cannot create new production overnight.
Investment and central-bank demand can change within months. Mine supply takes many years.
That imbalance is extremely powerful in a sustained bull market.
#SILVER PROVIDES ADDITIONAL LEVERAGE
Silver is both a monetary metal and an essential industrial material.
The market is expected to record its sixth consecutive annual supply deficit in 2026. Only approximately 28% of mine production comes from primary silver mines, meaning supply cannot respond freely to higher silver prices. Much of it depends on the economics of #copper, #lead, #zinc and #gold mines.
AI infrastructure, data centres, vehicles, electrical grids, electronics and energy investment all require silver.
Thrifting, substitution and recycling will limit demand at extremely high prices, but they do not remove silver’s strategic importance.
Because the investable silver market is relatively small, even a modest shift in financial demand can create explosive price movements.
GOLD DOES NOT NEED ANOTHER FIAT CURRENCY TO REPLACE THE DOLLAR
The #euro, #yen, #yuan and other #currencies have their own debt, demographic, political and structural problems.
That makes gold the neutral alternative.
The dollar can remain the world’s leading reserve currency, strengthen against the euro or SEK during crises and still lose substantial purchasing power against gold over a full decade.
These outcomes are not contradictory.
The cleanest long-term trade is not necessarily shorting the dollar against another fiat currency. It is measuring every fiat currency against scarce real assets.
THE #PETRODOLLAR WILL ERODE AT THE MARGINS
The dollar system is supported by far more than #oil. It rests on #Treasury collateral, global capital markets, dollar-denominated #debt, trade #finance, legal infrastructure and powerful network effects.
However, more energy and #commodity trade being settled in local currencies gradually reduces automatic dollar demand.
The #petrodollar does not need to collapse for this to benefit gold. Marginal erosion is enough when combined with growing debt and reserve diversification.
SECULAR BULL MARKETS LAST LONGER THAN PEOPLE EXPECT
The 1970s precious-metals bull market lasted roughly a decade and included an enormous mid-cycle correction.
The 2001–2011 bull market also lasted approximately ten years and survived the 2008 financial crisis.
The current move should not be viewed as one reaction to a single inflation report, war or Federal Reserve meeting.
It reflects a structural change in the global monetary, fiscal and geopolitical system.
MY BASE CASE:
The dollar remains the world’s number-one currency, but gradually loses reserve share and purchasing power.
Central banks continue accumulating gold in record speed.
Parallel payment systems and local-currency trade continue expanding.
Debt and interest expenses force increasingly aggressive financial intervention.
#Deglobalisation, #rearmament, reshoring, #AI, #electrification and #energy security keep demand for #commodities elevated.
Gold remains the monetary anchor.
Silver becomes the higher-beta monetary and industrial expression.
#Mining equities provide operating leverage to both, although they will experience much larger corrections, dilution risks and volatility.
The bull market will include several brutal corrections. Those corrections will convince people that the cycle has ended (Think #Zeberg and other clowns) when they may simply be resets inside a much larger secular move.
The thesis does not require hyperinflation, a common BRICS currency or the disappearance of the dollar.
It only requires persistent fiscal deterioration, gradual reserve diversification, declining trust at the margin and more capital competing for a limited supply of neutral monetary assets.
All four are already happening.
That is why I believe Gold, Silver and carefully selected mining equities can continue creating extraordinary opportunities deep into the 2030s.
Be prepared to build substantial wealth in the years ahead.
Oh and yeah - Repost!
Cheers,
Ape
🚨Four #Silver charts that I like A LOT right now and my thoughts:
#1 - $SSV.v - Southern Silver Exploration:
After an +80% move off the lows, $SSV began its daily cycle correction. Following a roughly -21.5% pullback, we are now seeing a bounce off RSI support, along with other signals suggesting that the daily cycle low is in and another upleg is about to begin.
$SSV is slowly breaking out of its #BullFlag (right under "resistance"), while the indicators are signalling intermediate upside ahead. In the end, #Silver decides, but this is a very sexy entry, and we could see $0.80 to $0.90 in September or early October.
I’m being defensive here, so that’s “only” 25% to 45% upside. But hey, who says no to that?
----------------------------------------
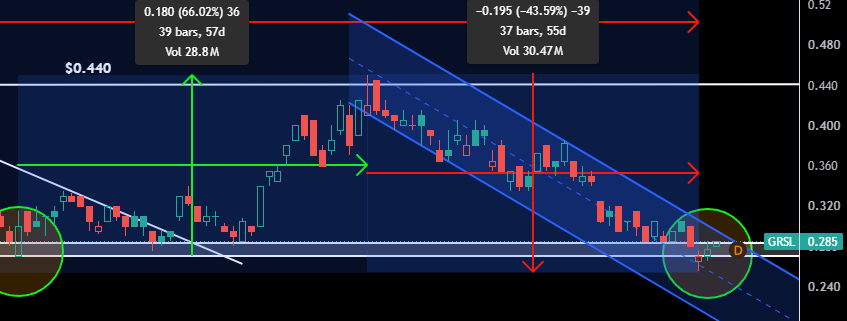
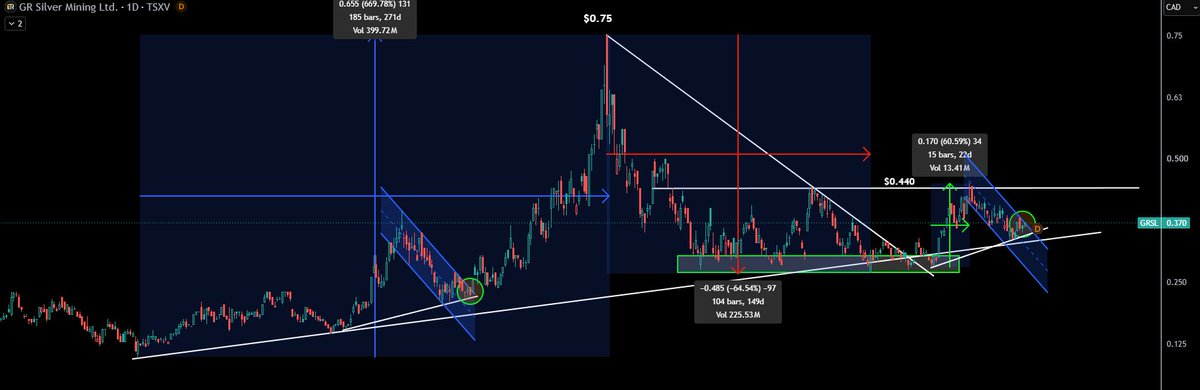
#2 - $GRSL.v - GR Silver Mining
Just like $SSV, $GRSL looks very sexy and ready for another daily cycle upleg here. $GRSL recently ran +60% in 22 days and has since corrected by around -20%.
What’s especially attractive here is that $GRSL remains within its #BullFlag (also bullflagging under resistance) and is only +4% above the low of this bullish correction. That means it offers more upside potential than many of its *performance peers*, many of which have already bounced +10% to +15% from their lows. I've sized up GR Silver during recent pullback and you basically get the same entry as me here... As I sized up at $0.380 :)
----------------------------------------
#3 - $AGX.v - Silver X Mining
$AGX is one of my absolute favorite plays for the next 12 to 18 months in the junior #Silver producer space. The company continues to improve quarter after quarter and delivers time after time. The share price has reflected that strength, and honestly, because I want even more shares, I’m slightly annoyed that it continues to perform so incredibly well.
A +1120% move in fewer than 300 days from the May 2025 lows was extremely #sexy. When I saw $AGX correct by almost -65% during the recent market downturn while its quarterly reports kept improving and impressing, I had no choice but to make it one of my top three positions by size for the coming leg higher.
It started well, with an +81.5% move from the lows. I basically printed money after loading up near the bottom with an #oversize position. I took profits between $0.92 and $0.97 and hoped to buy back below $0.80, with something close to $0.72 being my ideal, although wishful, target.
However, the significant strength appears to have established the low at around $0.85, so I had no choice but to redeploy capital at $0.92 this last week.
Regarding the chart, there are plenty of sexy things to highlight, but what really caught my eye is that $AGX reclaimed the trendline dating back to May 2025, which supported the entire 1,120% move. It then retested that trendline, bounced perfectly, and started climbing again.
Even sexier is that $AGX finally reclaimed its 50, 100, and 200-day moving averages back in August. The last time this happened was in June 2025, and what followed was a +650% move over the next 200 days.
Christmas will come early for Silver X Mining shareholders, and if you don’t own it during a #BullRun in #Silver, then you are not APE-APPROVED!
----------------------------------------
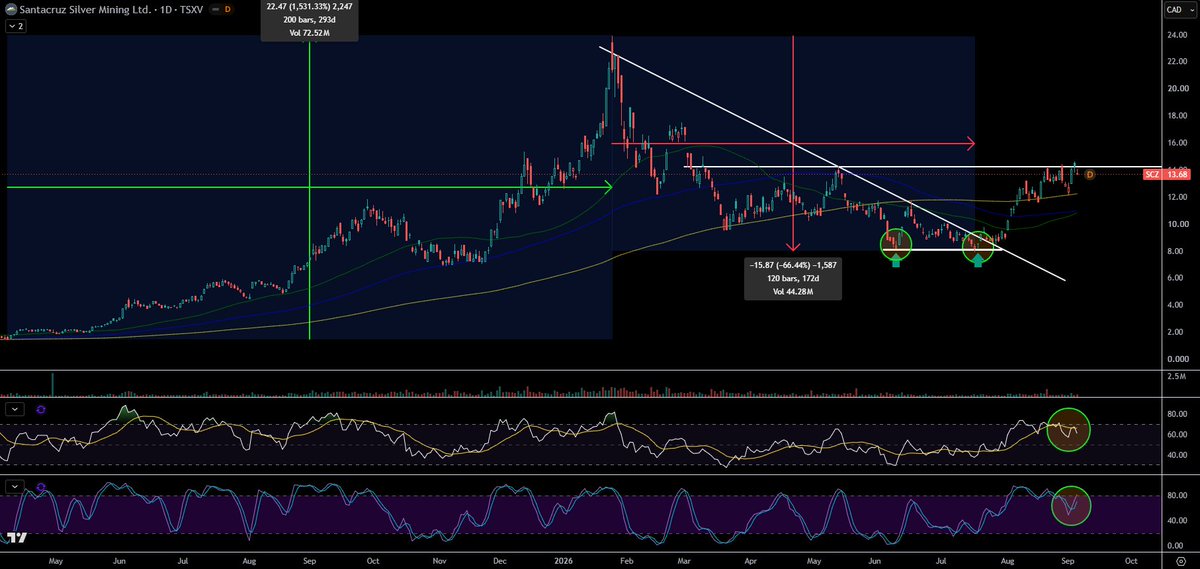
#4 - $SCZ.v - Santacruz Silver
Obviously, I can’t leave one of the absolute best plays in the precious #metals world out of this post.
#Santacruz printed more than +1,500% in fewer than 300 days during the previous leg up. That was followed by a -66% drawdown, which eventually bottomed through a fantastic double bottom.
I was very vocal around the lows in Santacruz, and I hope you guys listened. My average entry is around $8.60 after loading up near the bottom, with the low coming in around $7.90. Since then, #SCZ has rallied +85% and delivered huge gains.
It then corrected by -15% and appeared to be heading even lower. However, influential investors in the sector started recognizing its value, while recent newsletter recommendations sent $SCZ into overperformance mode, and rightfully so.
$SCZ became oversold during the correction because investors ignored the fact that close to 40% of the company’s production comes from #zinc. That zinc exposure helped offset the declining profits from #silver production during the major silver drawdown, as zinc continued printing new ATHs.
We can thank liquidity providers and algorithms for giving us cheap shares in what may be the best junior producer out there.
I reduced my $SCZ position at around $14, taking it from more than 15% of my portfolio to closer to 10%. I had to lock in some profits after gaining roughly +63% in just a few weeks.
I was hoping to size back up following a -20% correction, but that idea was disrupted by investors finally waking up to the value and a recent buy recommendation from a huge investment community. Nevertheless, the company remains an oversized allocation of more than 10% and a top-five holding in my portfolio for good reason.
Santacruz may become a leader during round two of this #Silver rally. My game plan is simple: any meaningful correction, and $SCZ will go from a top-five position by size to one of my top one or two holdings again.
I love this company, and it is probably the best fundamental play among all my oversized holdings right now. #EASY #BUY / #HOLD.
----------------------------------------
$SSV.V - Southern Silver Exploration is currently my largest position in the portfolio for the coming 6 months (Chart #1 of this post):
Why?
* Top-10 largest undeveloped #silver deposit globally
* Top-three highest #silver grade among the world’s 10 largest undeveloped #silver deposits
* Over 300Moz AgEq at approximately 256g/t AgEq
* Valued at only US$0.60 per AgEq ounce
(High-grade silver peer average: approximately US$4.46/oz)
* Cashed up and funded for its near-term work
* 12,500-metre drilling program underway right now, meaning plenty of assay newsflow ahead
Most important: Monster triggers ahead in form of an updated MRE targeted for Q3 2026 and updated PEA targeted for Q4 2026-Q1 2027.
When one of the world’s best undeveloped #Silver deposits lines up multiple major catalysts within a six-month window, you get world-class scale, exceptional grades and value-creating newsflow converging on one deeply undervalued monster asset. Now add rising #Silver prices....That is a powerful recipe for making money. #PRESS #THE #BUTTON.
----------------------------------------
Feel free to repost and help more precious-metals investors discover genuinely strong stocks in this sector. Win-win investments benefit us all, unlike “gurus” who rug-pull retail investors for their own short-term gains by promoting garbage companies.👊
#SILVER #MINING #STOCKS
Cheers,
APE
Top 6 positions in size right now (no particular order):
$GRSL.V - GR Silver Mining
$SCZ.V - Santacruz Silver
$AGX.V - Silver X Mining
$PGE.V - Stillwater Critical Minerals
$SSV.V - Southern Silver Exploration
$HYMC - Hycroft Mining
Note:
These six aren’t my top six because they’re the “best companies I could find.” They’re my top six because I expect them to outperform during the coming leg up.
There’s a big difference between the strongest companies fundamentally and the stocks most likely to deliver the biggest returns.
I’m here to make as much money as possible, not to find the prettiest investment on paper.
See you #HIGHER.
$GRSL.V - GR Silver Mining
I believe GRSL will be a huge winner coming rally. And it's sniffing on breaking out of this bullish formation.
I expect $0.60 incoming, that's a bit over +50% from here.
Don’t forget that $GRSL recently drilled one of the craziest #silver intercepts reported anywhere in the world over the past five years:
45.1m at 1,623 g/t #Silver
Including:
18.85m at 3,846 g/t Ag
8.25m at 8,579 g/t Ag
And those are TRUE widths. Absolutely insane hole.
A must own in the portfolio, as the future should be very bright for this company.
GRSL is now a top 6 holding for me.
#Silver
$ONAU.V - ONGOLD RESOURCES
I bought a new Gold Miner. I gave it a massive 8.2% allocation in the PF. Position number 6.
ONGold is a Toronto-based gold explorer holding two district-scale assets in the Canadian Shield, bought cheaply from motivated sellers. The assets are not speculative in the way a junior's assets usually are.
Monument Bay has been drilled more than 800 times over more than 232,000 metres and has carried a resource estimate before; the question is not whether gold is there but what a modern estimate at a modern price deck says about how much. The 2017 figure was struck at US$1,200 an ounce against a framework base case of US$4,000, and the pit that was economic at the former is a different and much larger pit at the latter — a cut-off effect that runs entirely in the shareholder's favour and that no amount of drilling was needed to create.
The restated estimate adds a metal the 2017 figure valued at zero, and the metal is not a hope: a 2015 Yamana estimate already booked 0.15% to 0.19% WO3 across the pit zones for 420,000 mtu of contained tungsten, on grades roughly threefold the Canadian comparators the Company names.
The 2025-26 pulp programme assayed 12,418 historical samples and, in the Company's own words, did not significantly increase the tungsten content — it confirmed it. So what the programme bought is confidence in a booked grade, not additional metal, and the tungsten case is a re-pricing of something already there rather than a discovery.
SRK Consulting was engaged in January 2026 to produce a new NI 43-101 estimate covering gold and tungsten. It would be the first estimate to carry tungsten and not the first of any kind: a 2015 Yamana estimate booked 0.15% to 0.19% WO3 across the pit zones, historical and disclaimed like everything else on this deposit. The estimate is contracted to a named consultant and guided by the Chief Executive to September 2026.
TPK, in northern Ontario, was contributed by the parent, Northern Superior, at the spin-out and is stated by the Company at 2,835 cell claims over 76,292 hectares in its most recent release.
The purchase price was extraordinary. C$250,000 in cash and 8.7 million shares bought two Manitoba properties from a company of Agnico Eagle's standing. A buyer of this size does not usually get to acquire an advanced-stage asset without paying for the drilling that de-risked it.
The board is the second asset. A five-person board holding Trelawney, Lakeshore Gold, K92, Argonaut and Bastion in its collective history, chaired by one of Canada's most recognised Indigenous resource leaders, with a chief executive whose specific expertise is permitting northern Ontario mines through to construction.
It is not the board of a company that intends to drill and hope. It is a board assembled to take a stranded advanced-stage asset through a resource, a study and a permit. The five-person board carries a discovery-to-exit record that is unusual at this size.
David Beilhart was Vice-President Exploration of Trelawney Mining and Exploration; David Medilek is President and Chief Operating Officer of K92 Mining; Michael Gentile is a mining investor with a documented junior re-rating record and co-founder of Bastion Asset Management; John Kim Bell brings Indigenous-affairs standing that is directly load-bearing for two remote projects requiring community agreement. The chief executive's own background is permitting and Indigenous consultation on Rainy River and Magino, both of which were built.
That combination is well matched to what these two assets actually need, which is not discovery but permitting, community agreement and a defensible resource.
https://t.co/JXAXY2CG4H
The past 2-3 days i've been buying this setup.
I'll share the writeup and which stock it is this weekend or monday.
But for those that are not lazy, feel free to dig up which one this is.😉
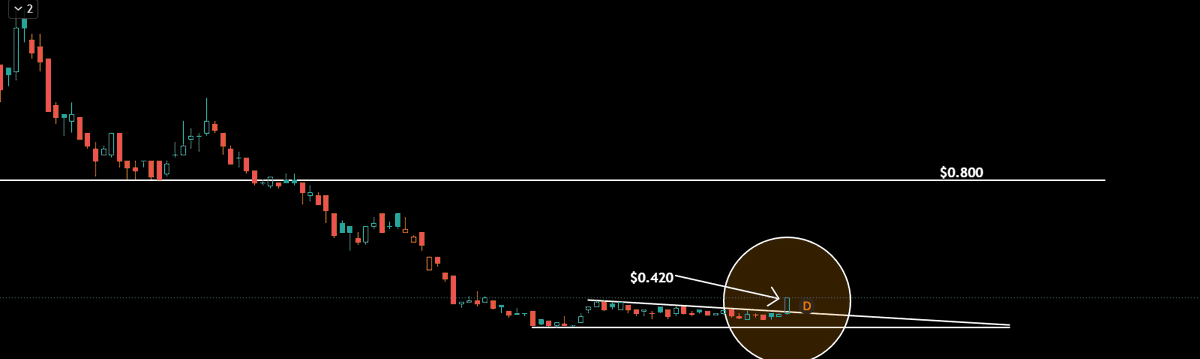
All I can say is, it's not a "wow" company. But its oversold and underpriced right now and due for a 50-100% move weeks/months ahead here.
It's a low risk/reward setup, I LOVE the chart entry.
I'm eyeing $0.800 as my target before the end of the year, but this guy comes from the January top at $2.57. That's +511.9% away. Im not chasing that 52w high, but im snatching the possible relief bounce here. Which smells incoming.
#SILVER