PSA: in light of recent cyberattacks and vulnerabilities, I recommend everyone:
* use a good password manager (1Password) and do not duplicate passwords
* use two factor auth for everything important (not via sms!! Google Authenticator or better yet YubiKey)
* Auto-updates on, and restart weekly so they actually install
* Freeze your credit
* Get an IRS Identity Protection PIN
* Get your cell carrier to give you a port-out PIN or number lock that makes the carrier refuse to move your number without the PIN
You can ask your claude code to audit what on your laptop is out of date and needs updating.
Just to be clear, if it is not clear enough already,
I’ve put a massive share of my wealth into Bitcoin, far beyond what most people would ever consider normal.
I own it outright. No leverage.
Nothing can force me to sell.
My financial future is heavily tied to Bitcoin, and I’m completely comfortable with that.
I’ve been in this accumulation mode for a couple of years already, and I plan to stay in it for at least as long as it takes Bitcoin to reach a $10 trillion market cap.
I will keep buying and holding.
And the more I understand Bitcoin, the stronger my conviction gets.
I don’t see this as a trade.
I see it as one of the biggest wealth-building opportunities of my lifetime, and I believe the long-term upside is still enormous.
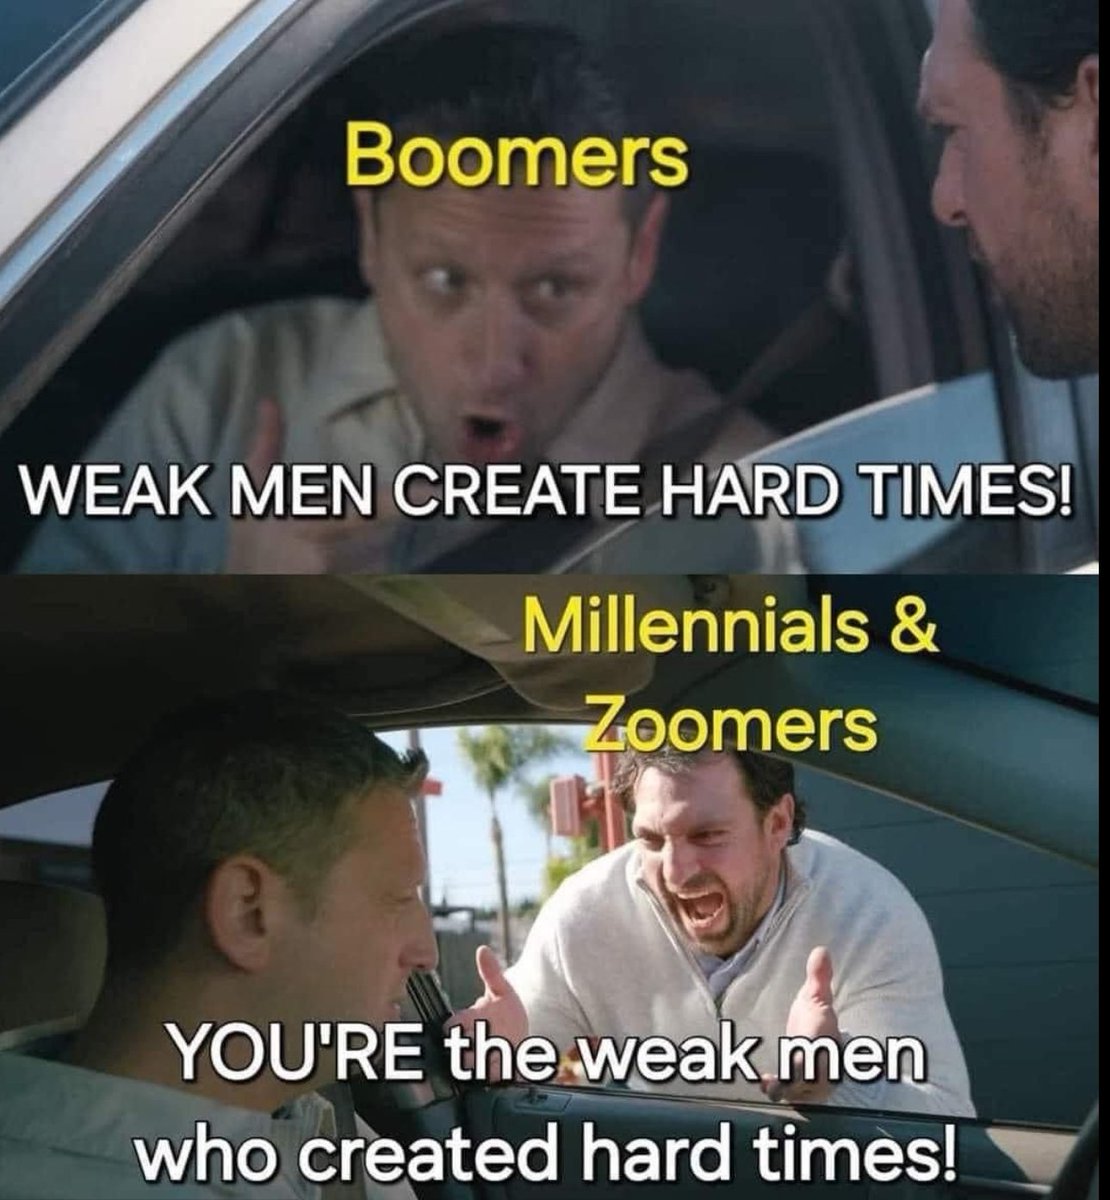
If you are a boomer that has to totally rely on social security to survive
Congrats you are a failure and you’ve managed to miss each of the largest economic booms in the history of earth
The US government will be so much better once we get rid of the pearl clutching boomer political class that currently runs the government
Almost every bad thing in the government can be tied back to keeping the boomer generation the dominate political ruling class
Social security as a concept sounds good until you realize that the boomers receiving the money have a net worth of ~50 times the younger generations of people paying the money.
Picture a millennial or zoomer renting an apartment paying money out of their meager paycheck each month to a boomer living in a million dollar house and you see the insanity that is social security.
Single biggest conviction on a very long time horizon is that Bitcoin reprices to be much closer to Gold in respect to market cap.
For anyone relatively young (maybe less than 45) that is the easiest long term high reward low risk investment decision that I can see.
The amount of BTC you own should be increasing every few years as you compound successful risk taking, alongside income into the asset, or at the least you should hold a core allocation and really leave it.
One of the best things about fud is that if it didn't exist there would be no upside.
Bitcoin continues to have several sources of fud that hang over it, and as it continually moves past those sources of fud you find new marginal buyers.
CT discourse is completely inconsequential for Bitcoin now. This is a global institutional allocation game, which will play out over decades. Another way to put it is institutional adoption super cycle.
If you study gold's first institutional adoption cycle (1971-1980) then we have a very interesting template we could be following. It became legal for US citizens in 1971 and futures launched 3 years later. 24x (nominal terms) in 8.4 years, with a 47% bear in the middle (sounds familiar).
Gold's market cap in today's dollars was ~$1T at the start, ~$12T at the top.
Bitcoin today is 1.7T.
ETF cumulative flow is only 8% below their peak right now, despite price being ~30% off its peak. Some of the inflow would have been basis trade previously too, which means the directional base didn't sell much. Bitcoin's ETF base has been much stickier than price. Very bullish.
Funnily enough I haven't seen people mention BTC super cycle on the timeline this time around. Maybe some signal there.
Diminishing returns thesis is consensus.
This cycle the awareness of debasement of fiat and theft via inflation might be at its strongest since Bitcoin’s inception due to genuine fears of a Sovereign debt crisis, whilst access to buying the asset is the easiest it ever has been.
Bitcoin is scarce digital capital, and it will continually reprice against fiat for as long as fiat exists.
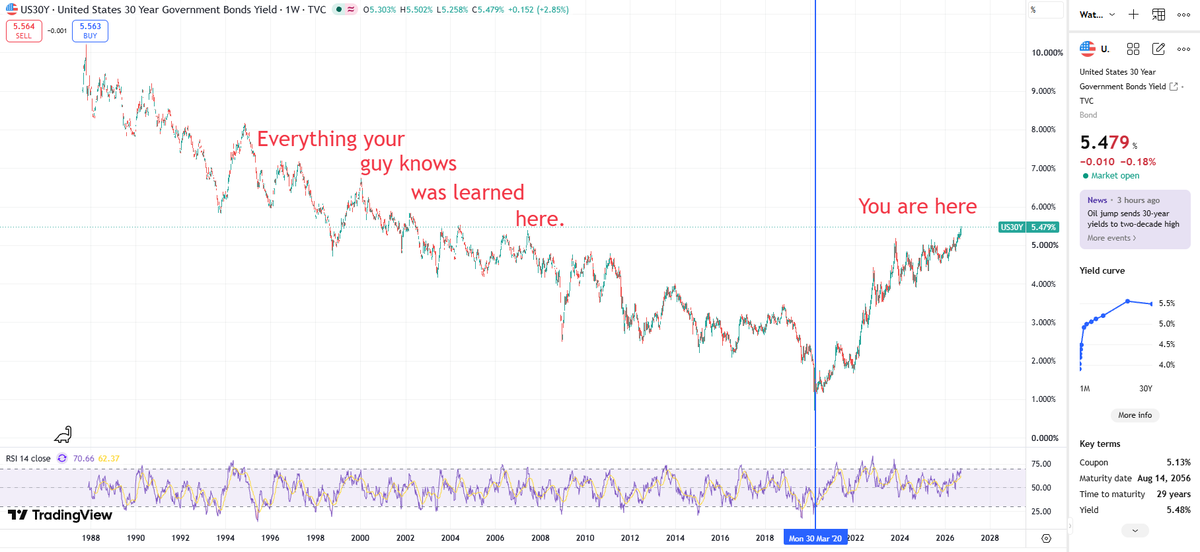
you can either look at a mortgage as a bank letting you long real estate against a perpetual devaluing dollar for a carry cost slightly above the risk free rate of return, or you can choose to be ignorant of how money works, if you spiritually have the mind of a medieval peasant
Micron will make more profit next quarter than NVDA made in quarter ending Jan 2026. 9 months ago. Everyone has been screaming about how cheap NVDA is. NVDA was worth $4.8 trillion dollars when it made $40 billion profit in one quarter. Micron is worth $1 trillion and it will make $44 billion next quarter. At this pace, Micron will pass up NVDA in quarterly earnings sometime next year or early 2028. If NVDA is cheap, what is Micron? lol. This is by far the easiest buy in my lifetime!
The Thomas Massie primary is truly insane. We are looking at the most expensive U.S. House primary in history, with spending pushing toward $35 million.
Massie's opponent, Ed Gallrein, has raised just $2 million on his own. The rest of the money, over $14 million, is coming from outside Super PACs who desperately want Massie gone.
On top of that, Pete Hegseth is being deployed to Kentucky to campaign against him. Stephen Miller & Con Inc. have been on massive Twitter tirades attacking him. And there was a highly coordinated smear campaign of unfounded allegations launched this week by Con Inc. influencers.
When the establishment is willing to spend $35M+ and go to these lengths to take one man down, it really makes you wonder why.
Whether you like Massie or not, this election will determine whether or not we as voters actually have a voice anymore. If outside special-interest money can successfully buy a seat and sway an election like this, we have a serious, serious problem.
It's only a matter of time before International Trade is settled in A global neutral reserve currency.
Some are shocked Iran is asking for Bitcoin, but a bit of historical context adds some colour.
At Bretton Woods in 1944, Britain proposed the Bancor - a neutral, supranational reserve currency not controlled by any single nation, designed to balance global trade without giving one country an unfair advantage.
The Americans rejected it. The dollar won and for a while that was fine because the dollar was backed by Gold.
That all came to an end in 1971 when Nixon's temporary suspension of the dollar's convertibility into gold became permanent.
What remained was a reserve currency backed by nothing but American political will and military might.
That arrangement has been slowly dying ever since.
Every round of quantitative easing and weaponisation of the SWIFT system via sanctions has accelerated the search for an alternative.
Countries are now asking themselves why should they trade their resources for a currency another country can print and freeze at will?
A multipolar world needs a neutral, borderless, apolitical reserve asset that no government can weaponise. This is why Iran wants Bitcoin.
In 1944 they called it the Bancor.
Today we call it Bitcoin.
This is central banking in a nutshell:
A group of rich guys go to the king and say: "Hey, you need money for your war. We'll give you all the money you want."
The king says: "Great, where's the money?"
They say: "We're going to make it up. We'll write numbers in a book and that's your money now."
The king says: "What do I owe you?"
They say: "You pay us back with interest."
The king says: "Where do I get that money?"
They say: "You tax your citizens."
The king says: "What if I can't pay it all back?"
They say: "That's fine. We'll lend you more. Same deal."
The king says: "And what do you do with the IOUs I gave you?"
They say: "We use them to prove we have money, so we can lend even more money to other people and charge them interest too."
The king says: "So you made up money, lent it to me, I tax my people to pay you back, and then you use my debt to make up even more money and lend it to everyone else?"
They say: "Yes."
The king says: "What did it cost you?"
They say: "Nothing."
That's literally how the Bank of England started in 1694. The Bank was formed to finance King William's war with France. The king gave the Bank a charter, granting it a monopoly on money.
The king could have as much money as he wanted. The bankers could always earn interest. Taxpayers covered the bill.
Now replace "king" with "United States Government" and you have the Federal Reserve in 1913. Same story, different country.
It doesn't end there.
185 central banks exist in the world today.
Across the globe, the governments get as much money as they want, the bankers load their pockets with interest, and the taxpayers pay for it all.
Oh, and if you don't pay your taxes, they'll fine you, penalize you, or throw you in jail.
The ONLY way out of this is to STOP USING THEIR MONEY.
As long as you're using the money that central banks control, the central banks will have control.
You have to stop giving them energy.
Use a different form of money that they can't control.
This is why Satoshi Nakamoto created Bitcoin.
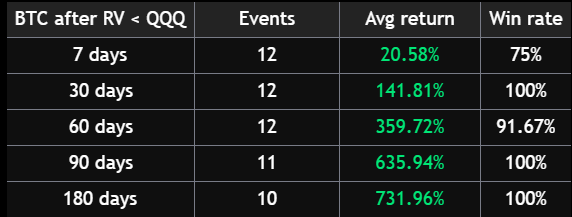
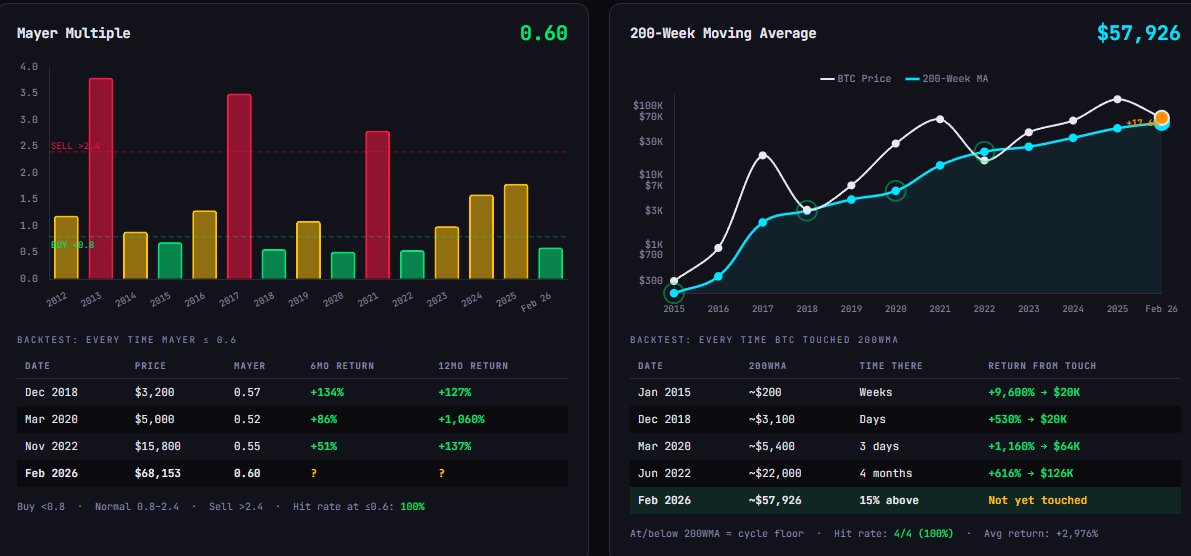
Throughout Bitcoin's life span we have seen two indicators continue to be the best global market bottom signals: The Mayer multiple (distance from 200 day moving average) and the 200 week moving average.
Both of these are clearly in long term accumulation territory. $BTC
"I'm too late to Bitcoin."
Late compared to who? Your friend? Twitter strangers? Your coworker?
Bitcoin: ~$1.7T market cap
Gold: ~$30T
Global assets: ~$300T+
Bitcoin is less than 1% of global investable wealth.
The "too late" crowd said it at $1,000. Said it at $10,000. Said it at $60,000. Saying it now.
Every cycle it ages like milk.
You're not late. You're VERY early.