Investment & Data Nerd. Behavioral finance meets personal growth with a goal of better thinking and decision making. Opinions are my own, not investment advice.
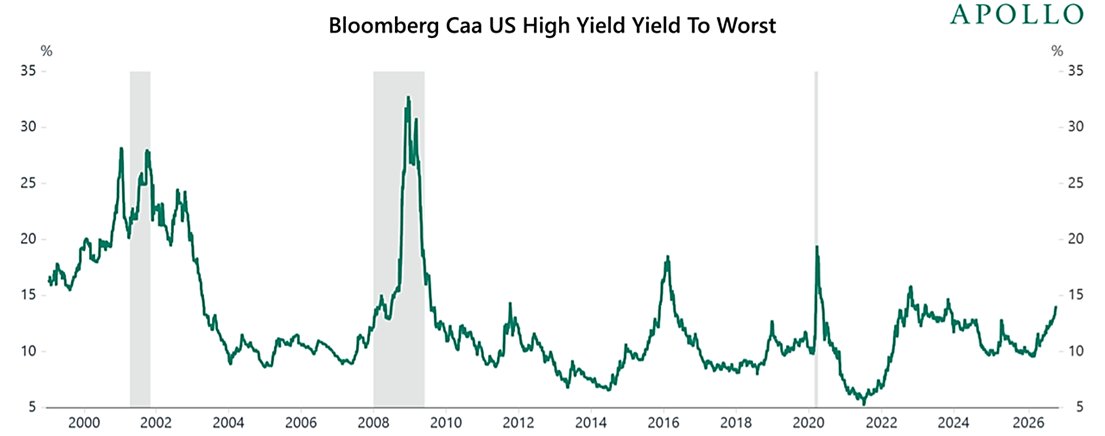
Yields on the riskiest bonds are marching higher again, nowhere near 2000 or 2008 crisis extremes, but closing in on levels seen during the 2022 sell-off. Credit stress signals are flashing, but not yet screaming.
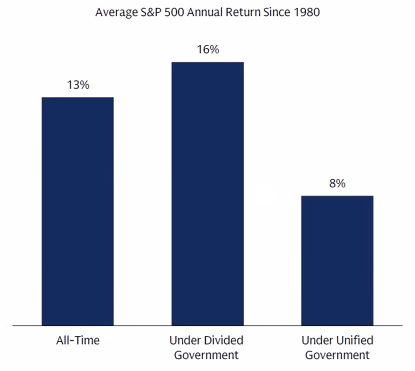
Markets historically deliver better returns during periods of split government control between Democrats and Republicans. Divided Washington might actually reduce policy risk and boost market confidence.
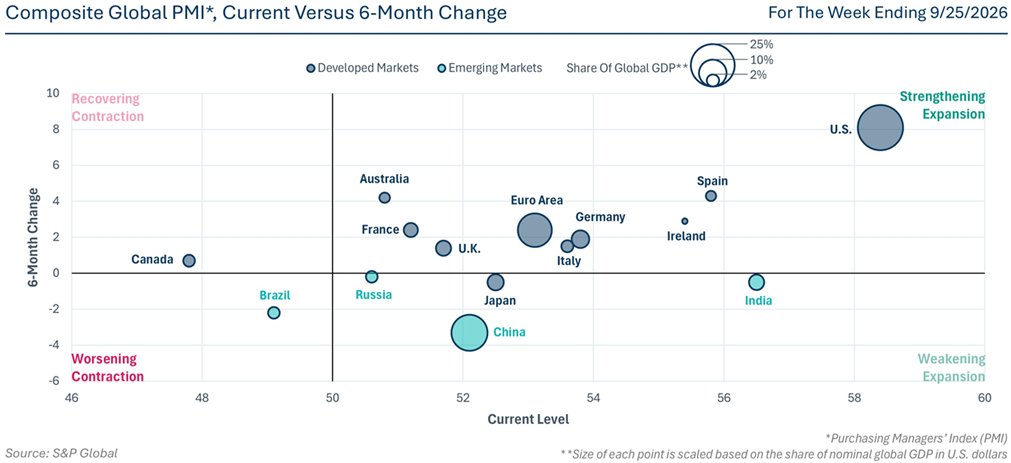
The U.S. economy’s growth, both in level and momentum, is in a league of its own globally. This resilience could shape markets and policy debates for some time.
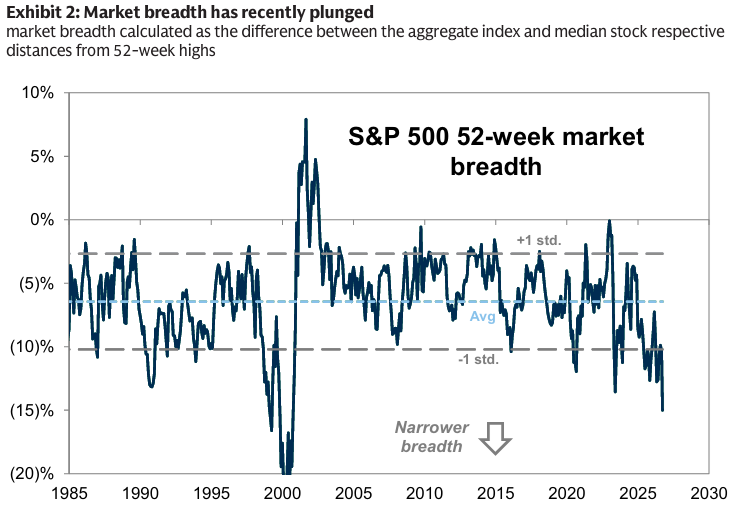
The S&P 500 is just 1% below its record high, but the median S&P stock trades 16% below its 52-week high. The typical stock is much weaker than the headline index suggests, market strength is masking significant internal weakness.
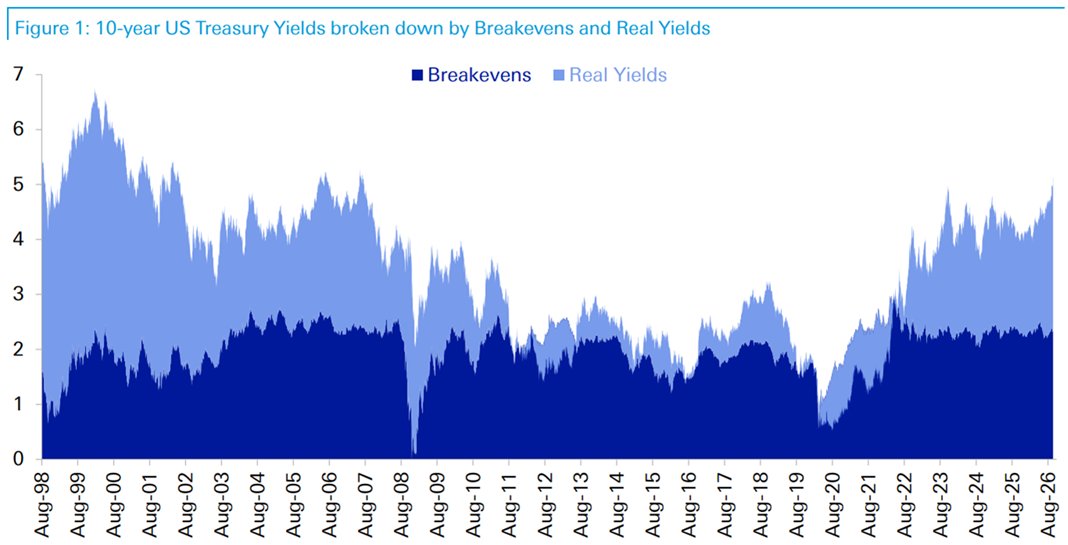
The real yield (light blue), that’s nominal yield minus expected inflation, is at its highest since the early 2000s. Not a call to rush in, but definitely a fresh angle on bond appeal worth watching.
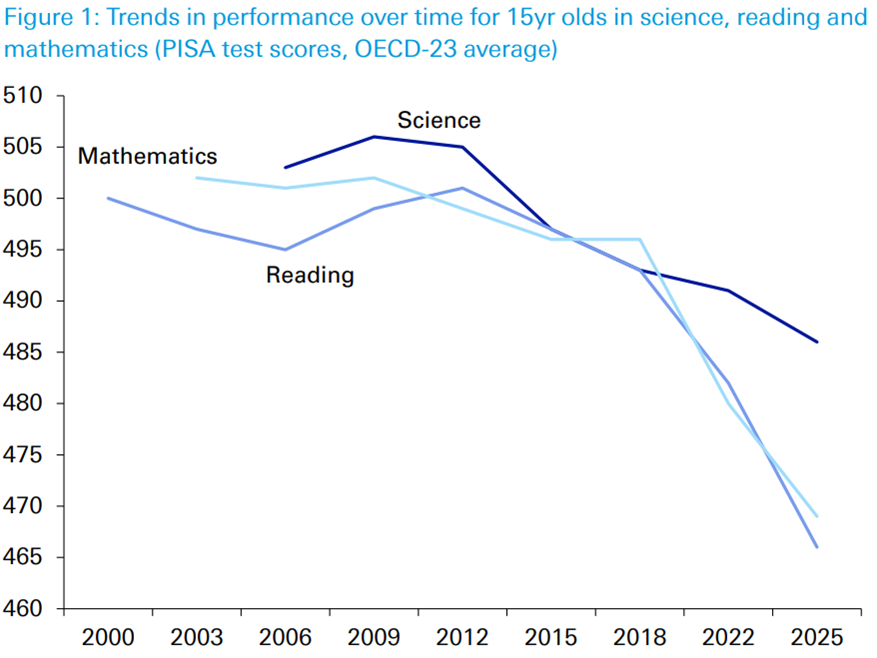
Blaming social media (or soon AI) for distractions is easy. But maybe parents should just look in the mirror. The tools are everywhere, it’s up to adults to regulate access.
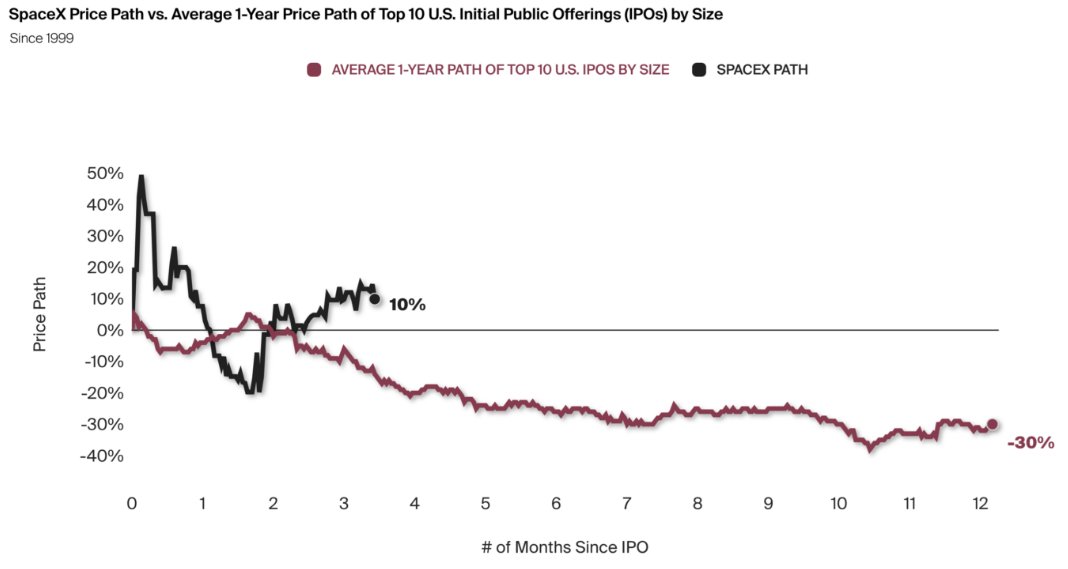
If OpenAI and Anthropic IPO as expected, they, along with SpaceX, will have a great market capitalization than every combined tech IPO since 1980. Wild!
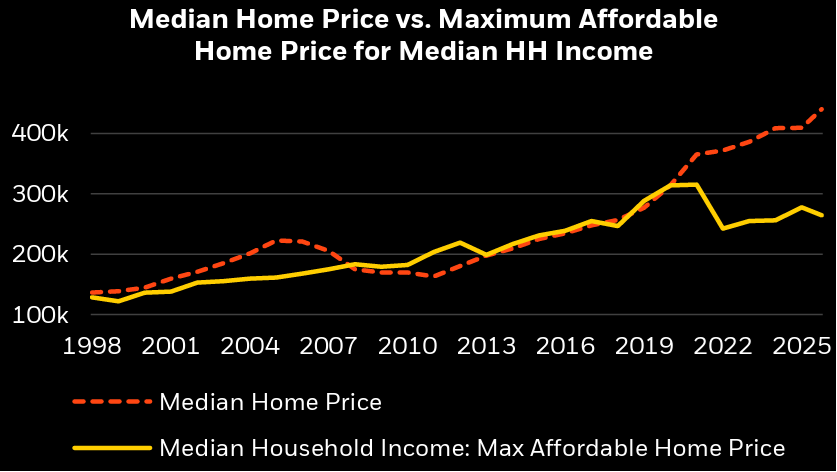
This ratio remains accurate after accounting for inflation (which is a popular question these days).