https://t.co/1XjVkQT8FL
Please share!!!
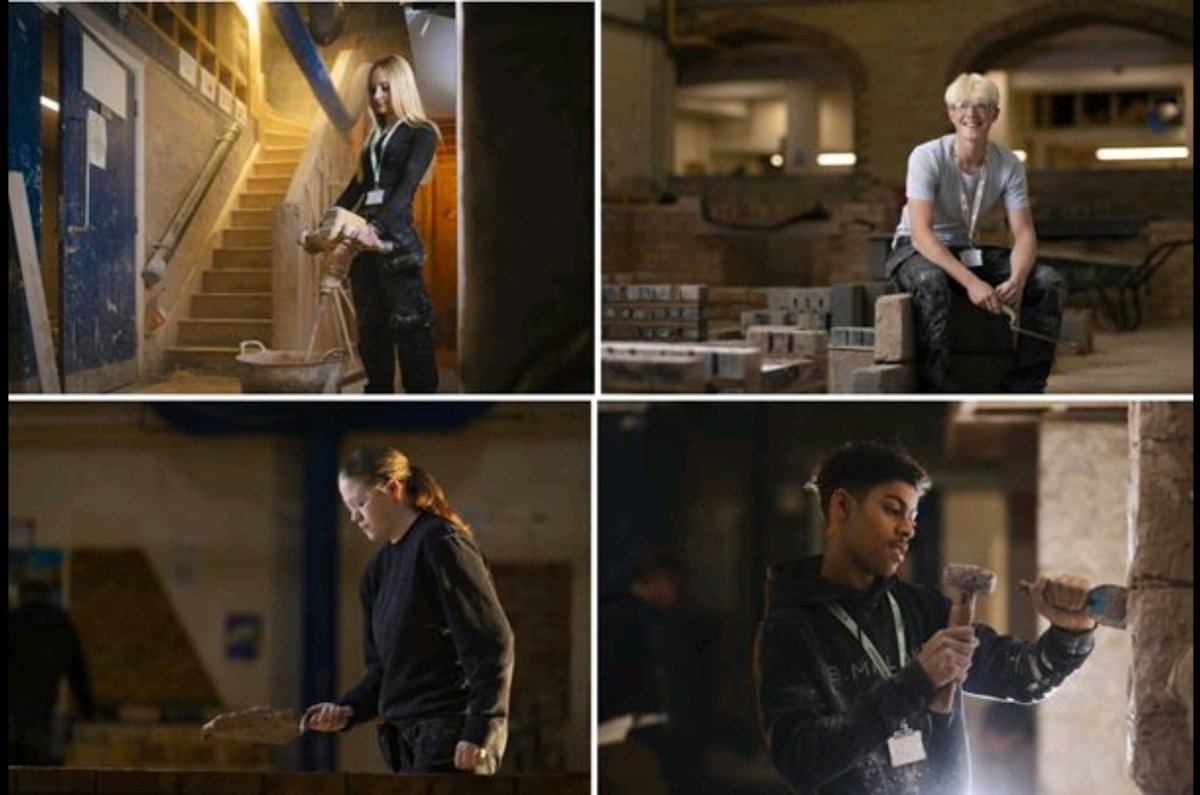
#LINCOLNSHIRE#CONSTRUCTION INDUSTRY — WE NEED YOU!
We have learners ready to learn.
We have learners ready to work.
We have learners who could become your next employees.
But we need the industry to help us give them the opportunity.
As a GMGI shareholder I had a few emails on my thoughts on Q2 earnings.
IMO - Straight up zero surprises. No upside blowout numbers but right on track. All companies are scaling nicely and they are controlling debt.
As a LT investor not trader, I basically look for any changes in my overall LT thesis or new red flags so my comments are probably more qualitative than quantitative. To me it is about growth and execution.
Meridianbet is my primary focus and they are always rock solid and the majority of the company. 30% increase in wager volume and 124% increase in new registrations. As expected from a company that has grown consistently for almost 3 decades with zero borrowed money.
Expanse Studios is my second focus and they broke 1000 new US partnerships with 13 new US partnerships as well as new operational agreements in Brazil, Peru, Romania and Croatia. They continue execute on steroids.
GM-AG, RKings, CFAC, and MexPlay are all growing and what I consider uniquely different subsidiary rev steam opportunities. Just icing on the cake. RKings is really executing nicely and CFAC will follow their model.
Investor Press Release:
https://t.co/W3j5zd6y73
I do not find much value in just copying and pasting financials but I would like to address a few questions. These are just my personal opinions. Remember I am NOT an advisor. I am a shareholder but I do welcome objective criticism from subject matter experts.
What about the $2 mil decline in EBITDA?
Blah, blah, blah... put it in context. I don't really care about $2 mil because it is not significant. Why? Because when considering an early growing company I am concerned with growth over immediate profits. If GMGI were loosing money simply operating in existing territories I would be concerned but they just expanded into 6 more countries including Brazil ( w/a $6 mil for a 5 year lic ) and in the scope of financial worries $2 mil is nothing. DKNG just spent 1.2 bil in marketing 2023 w/a loss of 1.77 bil. It is all about gaining market share.
A closer comparison would be RSI - ( Rush Street ) Q2 just went from a YOY loss of $300k Q2 2024 to a $29 million net profit Q2 2025. RSI is now trading close to $20/share. These are numbers I am looking forward to as GMGI up front capital costs decrease and their growth in market share revenue starts to add up.
Let me dive a bit further on the small loss. It is mostly from some unexpected sporting event outcomes ( plus 1.5 mil interest expense ) I actually expected this may the case and I will explain. After an interview sometime ago, in a Q and A session, I sent a question to the CEO on their thoughts how AI might affect the sports-betting pay outs. They answered the question but framed the answer on how AI will HELP their company.
My concern was the narrowing margins and unexpected sporting event outcomes that can be affected by bettors using AI. There have been several sector companies recently taking hits due to a large amount of wagers on sporting events with unexpected outcomes.
How this will be addressed?
Realizing predicting accurate and consistent sporting event outcomes is impossible and margins are compressing with increasing competition, Meridanbet was one of the few that invested in AI - nearly a decade ago and their 5th Gen AI enabled ATLAS program has just completed rollout.
Why is this important and how will it address profitability?
Sports-betting has a smaller rev margin ( around 3-6% ) than igaming ( around 6-18% ) but the majority of money in the future will be made in micro-betting or "live-betting'. With the right AI functionality, a platform can spit out 1000's of betting options in real time during an event. Meridanbet's 5th Gen AI enabled system "Atlas" that has this ability. They are in a small group of about 5-10% with this AI tech.
Why do they not have more revenue from Brazil?
Give it time. Seriously it has been 6 months and even Brazil is sorting out the regulatory details. Brazil has shut down thousands of illegal web sites to make way for the 80 or so legit companies that are now Federally Licensed to operate throughout the entire country- unlike the US where each state has different regulations.
Even the smallest sector niche players take years to be profitable with the larger companies taking a decade or more to become profitable. Remember DraftKing started around 2012 and finally had their first year of profitability over 10 yrs later. Focus on GROWTH.
While I do not expect GMGI to be a major player like DKNG, there will be plenty of opportunity. Meridianbet has a long history, over 25 yrs of growth with zero debt while remaining profitable from day one. They are the ONLY company I know of in the sector to obtain profitability from the beginning without taking on huge losses from player acquisition costs.
Per GMGI - "We expect full-year 2025 revenue to range between $185 million and $188 million, reflecting a growth rate of 22% to 24% over 2024. This reflects the impact of the customer-friendly outcomes experienced in European business late in the second quarter. We have seen July revenue growth from our European business recover as expected, up both sequentially and over 2024 by roughly 25% in constant currency. This is a return to our expected trends and consistent with our transactional volumes"
Historically GMGI has been quite conservative and typically beats estimates. My estimates were closer to $200 mil and it looks like I was a bit high.
Zooming out to the bigger picture, I am happy with all GMGI companies and their founders progress and execution. Disruptive tech adoption always takes much more time than anticipated to reach the bottom line.
A few months back I posted some 5 year charts on some X "HOT" stocks. Every one had YEARS of flat or declining SP growth proceeding their acceleration. That is the norm for small growth companies. They do require a lot more patience than other cap size companies.
I personally, do not see anything alarming to change my thesis. Almost every multi-bagger starts small and takes YEARS of grinding and spending cap ( or dilution to acquire the companies needed to scale ) before they finally accelerate and reap the rewards. When GMGI pulls the $20-50mil+ net I hear ppl mentioning they will be far, far away from a sub $2 stock.
IMO the risk/reward for small company is exceptional and the downside is limited. These are only my thoughts and as my profile says, I am a professional "hose-dragger" so consider the source.
$DKNG $PENN $GAMB $EVO $FLUT $MGM $BETZ $BRAG $EVVTY $BETS $CZR $RSI $HIMS $NVDA $AMZN $LVS $TSLA @GMGI_Official @StudiosExpanse@meridianbet@meridianbet_ofc $BTC $GOOGL $MSFT $META $MSTR $LUNR $HOOD $PLTR $LMND $OSCR
I had have a few inquiries why I scaled out of my $GAMB into $GMGI. Basically, while I really like $GAMB & think it is a great lil niche company IMO, at the current share price, $GAMB has less upside potential (1-2x long term) and more downside RISKs. $GMGI has more upside potential (5-10x long term) & less downside RISKS. I highlighted some of my reasoning below comparing the two small-caps. Again, as an LT, ST or swing I do still like $GAMB. I admit I scaled out a bit early but ideal timing is almost impossible.
THOUGHTS ON $GAMB AND $GMGI-
GAMB
I like GAMB a lot and owned it for years. The CURRENT financials and growth is ideal. It is a nice lil niche company with a lot to like!
I like the CEO.
I like GAMB balance sheet and financials.
I like the profit margin.
I like current share structure.
I like inside ownership.
I like the FCF model.
I like the future potential rev stream growth of of states lined up to legalize gaming.
I like it as a near term swing trade up to about $16 (if I still swing traded).
I think in the near term 1-3 years they will do well.
I think it is a fairly safe play for a small-cap.
Two main reasons I rolled out of GAMB into GMGI: Looking past current financials I have to look at:
Future Upside opportunity -
*What are the near and long catalysts to get SP to 10x in
5-10yrs?
*What are the odds of this company growing into a
billion dollar company?
*How fast will it happen / how set to scale?
Future Downside Risks -
*What needs to go wrong for me to loose my investment?
*How protected am I?
*What are the near and long term risks?
Future Downside risks - what can go wrong and how low can it go?
GAMB is institutionally saturated with 184 institutional positions. Many of these large institutional positions are getting lofty from entry price and when they sell bigger positions it will hit SP hard with their small float.
Institutional holdings and around 12.2 million shares owned or 35% of total shares however this number is about 75% of their 16 million float. They loaded in 2023.
That is concerning as I would rather get in before all the institutional buyers.
GMGI has less than 3% of shares held by institutions. They are certainly earlier and on the front end of retail and institutional discovery. As SP increases and liquidity it will provide opportunity.
______________________________________________________________________________
GAMB / GMGI operational risks
GAMB has concentrated accounts and heavily dependent on SEO and search algorithms.
A year or two ago Google adjusted their search engine also and is caused a large drop in GAMB rev. The vast majority of igaming/sportsbetting business, approximately 80%, is split among the top few companies in the US including FanDuel and DraftKings making for some very concentrated rev accounts.
Revenue that is highly dependent on fewer larger accounts in a competitive sector has greater risk. A recent example is Evolution loosing a key large account and its effect on earnings and SP.
GMGI has a much more diverse and larger number of revenue streams. GMGI now has 6 separate but synergistic companies that are growing and profitable.
GMGI is more geographically diverse. It has less geopolitical and economic risk as it operates in 20 different countries with multiple currencies, regulations and tax rates. If one country changes its gaming regulations or tax rate the change will not crush the company.
______________________________________________________________________________
In a sector where DATA is value, I believe GMGI has a larger global DATA advantage over GAMB. Meridianbet has been collecting date in each region they operate for decades. GMGI's other companies for 10 years. This data is very valuable in targeting, marketing, obtaining, and retaining players. 24 years of collecting consumer and regional demographic DATA inc preferences, sports, profit opportunities, spending amounts, igaming and sportsbetting behaviors from 20 different countries all around the world.
_______________________________________________________
GMGI/Meridianbet has a large tech advantage.
GMGI & GAMB are really tech/AI companies. GMGI owns and controls their critical tech. That was a HUGE upfront investment in time and money with over 100 programmers working the last 10 years. Some of the greatest engineers in the world have said a sportsbook/igaming program that supports millions of players and bets securely while monitoring all games, bets, and odds in multiple countries, currencies, regulations and languages in real time is one of the most complex programs imaginable.
By taking this difficult and costly route to create their own tech that can integrate AI, GMGI/Meridianbet not only saved a lot of money in the long run but inadvertently created a whole new B2B stream. The majority of other companies tech is antiquated and cannot integrate the AI tech to increase margins by offending the thousands of “real time” bets nor can they integrate all the regional and cultural player preferences and behaviors.
The competition for actual “bet odds” has become is fierce the straight up betting odds rev is declining as consumers shop around and margins compress. These spontaneous bets create higher profit margins. GMGI’s “Emptybet” is a prime example and other competitors and going to need this tech AI advantage.
_______________________________________________________
GAMB / Barrier to entry in affiliate marketing is lower.
GAMBS competition is the affiliate marketing area is getting fierce. Barriers to enter are lower. Affiliates currently make average $50 - $400 / life of player and this is expected to decrease as more competitors enter market. Margin compression of the referral % may effect bottom line. GAMB does currently have great margins and great positioning but how the rev may be effected in the next 5 yrs is more concerning to me.
GMGI has a much larger barrier to entry/MOAT as far as complexities of tech supporting millions of players and their bets in real time. The cybersecurity, decades of gaming programming to create content and integrate AI, each companies build out time, different gov gaming & taxation regulations and oversight w/multiple currencies, accounting & languages in each country as well as the most complex payment processing systems, B2B, B2C mobil tech, retail franchise buildout, etc is a moat! Gov regulatory moats can be complex and time consuming. Companies in these sectors have huge legal expenses required to meet regulations, deal with legal ramifications, acquisitions and minimize liabilites.
______________________________________________________________________________
GAMB is shifting to increase growth by acquisitions vs organically.
I just saw GAMBs $50 million raise by Wells Fargo for the purpose of growth by acquisition. I am interested to see how Gillespie navigates future growth as organic slows and how savvy he is in this arena as it has unique challenges. The majority of acquisitions do not always add the value expected. It will be increased debt/shares. Not a bad thing, but complexities of acquisitions and news always effects SP with a short term knee jerk reaction. The acquisition skill set often differs from that of a typical CEO's sector skill set.
GMGI has made the majority of the acquisitions needed to scale on a global level, absorbed all the one-off costs, and taken the headline hits. Goodman has a history and excels at obtaining net-net-profitable acquisitions with no debt. This is his area of expertise and why he lets the CEO founders stay in place to operate their companies while he puts deals together.
_______________________________________________________
Content provider
Content is another outsourced third party rev stream that is rapidly growing. GMGI/Meridianbet now owns Expanse Studios.
Since 2017 Expanse Studios has grown like a weed and now have over 50 games is 20 languages and are one of the fastest growing content makers with over 100 awards for their games.
Expanse has hit about a dozen Expos this year all over the world and just signed over 100 new deals in Q3 of 2024 alone. They are mobil focused and targeting the next generations gaming preferences.
By making their own content via Expanse Studios GMGI/Meridianbet will save money in the long run not having to outsource all content. Inadvertantly they have created another growing B2B revenue stream they can use and cross market across all their platforms and companies.
Recently Expanse announced they are close to entering USA via New Jersey. GMGI has left the founder/CEO Damjan Stamenkovic at the helm to continue the companies success.
______________________________________________________________________________
Entry Share Price - upside potential vs downside risk
GAMB does not have a lot of opportunity for price discovery. All financial information is easily obtainable. It has many analysts. GAMB, while still trading at an attractive multiple and PE, it is currently trading in the upper range w/ little short pressure and large institutional ownership so along with other factors listed above, IMO it does have more downside risk than GMGI (at current levels). It is much easier to place a value on with a single domestic company, well understood revenue model with limited revenue streams. GMGI intrinsic value is probably around $16 and DCF $13. As I said I do believe GAMB share price will continue to grow and it is a great little company.
GMGI share price has been crushed. As the SP rose on good news it got to around $6 six months ago and some entity placed a massive 1 million share short position and walked the price down daily by selling small orders into low bids near close. They accomplished their objective as sentiment is at an all time low.
Some companies that perform poorly and take on huge debt certainly deserve to be shorted but in other situations traders simply short low vol stocks as they are easy to manipulate, or a finance company/hedge fund will create an attack to generate returns, or load up on shares at a lower price.
Shorting can create ideal entry prices. The majority of investors/traders DO NOT analyze a company deeply, they simply judge a company by share price and direction of momentum. FOMO is huge and chasing is a normal pattern. Studies show an investor is much more likely to buy a stock that has just doubled in price that one that has dropped in half. 6 months ago investors were really impressed with GMGI.
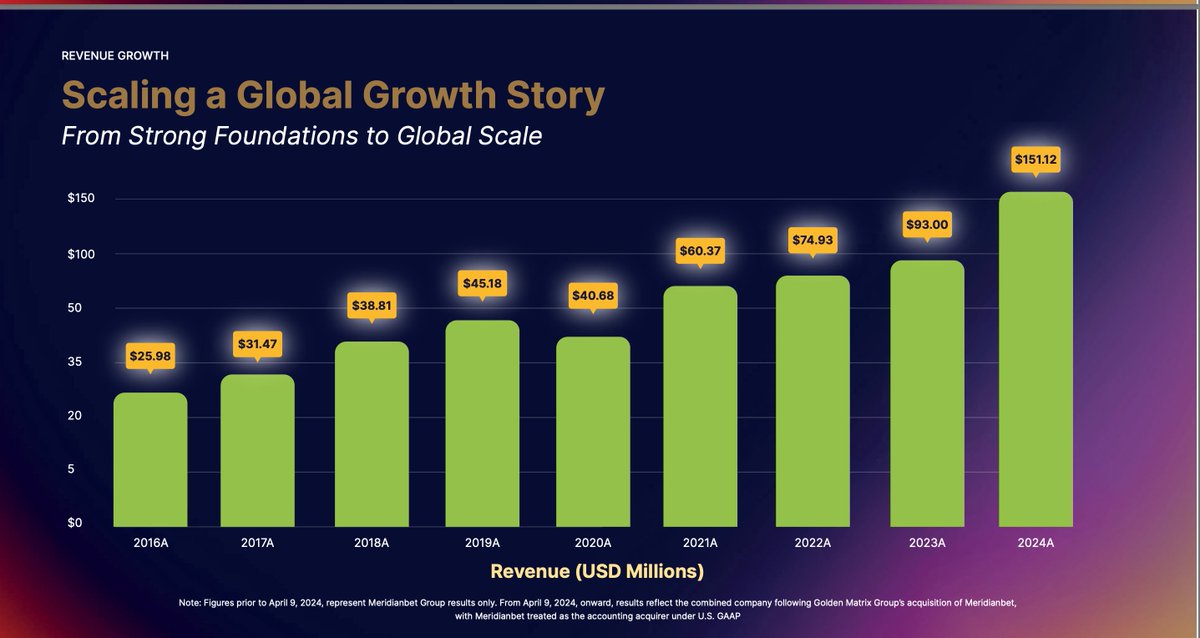
At one time GMGI traded up to $14 pre-Nasdaq on about $2.5 mil rev. Today, they are around $160 mil /$25 mil net and the company. Yes they lost a slight amount the last few qyrs but the companies were profitable and the loss was one offs from closing the acquisitions and rolling out new territories.
IMO the SP drop, and this is speculation, this may be due to a company named LIND that has a long history of naked shorting or some other shady entity The SEC as well as the GMGI/Meridianbet is aware of the party and addressing the issue.
Considering the shorting and subsequent share price drop has already happened the short position will need to be covered. A short position can be considered “pent up buying”.
On a positive note ALL small-caps should really benefit from a Trump presidency as he and the new SEC Chairman vow to crack down and finally enforce shorting/naked shorting regulations. They even talked about a temporarily halt on all shorting until they can get it under control as it has wiped out the entire sector over the last 5+ years as risk-on quick returns and market manipulation have turned investors from small-caps. This SEC area of oversight needs drastic overhaul as the avg time for a single naked short complaint to be processed is 4-6 years and 90% of most offenders go unpunished.
_______________________________________________________
Consumer Trust.
I think both GAMB and GMGI have done an outstanding job at building trust.
Trust is #1 on consumers list of priorities when looking for an igaming/gambling company. Most of the successful igaming company CEO’s like Evolution’s Carlesung and Goodman say it is their #1 priority and absolutely essential to success in the industry.
GMGI/Meridianbet has done much more than GAMB over the last several decades by committing millions of dollars and thousands of man hours to build consumer trust and make an impact in the communities they serve. I am not as versed is GAMBs commitment level and history but recognize it may not be as quite as essential in affiliated marketing as it is for an actual operator to succeed.
GMGI/Meridianbets commitment to ESG/CSR programs are second to none and has played a key role in building their reputation. I posted a list in my feed. I implore anyone interested to look at their history of community programs and ESG report.
_____________________________________________________________________________
Proven models.
GAMB and GMGI both have proven models.
GAMB as well as every one of GMGI’s companies has a proven model of success.
GAMB has been around since 2006 and CEO Gillespie partnered with college buddy Kevin McCrysytal now COO Originally they were involved in the promotion of Soccer gaming to sites in Asia.
Once the US started passing legislation he saw the opportunity in the US a bought https://t.co/tiAIA0rkTL domain ($2,500)
GAMB has won many media award and employee “Best Place to Work” which I highly value as organizational culture is a huge positive criteria in my opinion.
GAMB incorporated in New Jersey and ended up making Nasdaq in July of 2021 ( about a year before GMGI if I recall correctly ) They have a lot of competition but have secured a very nice position and brand recognition in USA. I could talk quite some time on the history of GAMB.
As far as revenue catalysts I like that GAMB has more US states lines up as they pass legislation to legalize online igaming/sportsbetting. This adds some level of security to rev growth. They also have opportunities in the media and via acquisitions as well as further expansion into Europe and other countries.
GMGI has too many companies/catalsys to go into deeply. IMO they have many more short and long term catalysts to exceed the $1 billion level faster.
GMGI now owns:
Golden Matrix - GM-AG
RKings
CFAC
MeridianBet
Expanse Studios
MexPlay (newer wildcard growing fast and still in infancy)
These companies can now cross market and scale into the others territories more easily as they have a proven business model and know how to navigate that countries gaming and tax regulations.
Not only is GMGI incredibly diversified in products and services but in the B2B and B2C areas. GMGI has both online and retail ( 800 betshop franchises ).
GMGI has the ability to add many more accretive B2B & B2C revenue streams than GAMB.
GMGI/ Meridianbet are expanding rapidly into even more countries w/recently added, Peru, Africa, Bulgaria and several others to make around 20 territories/countries.
While the US states are nice revenue streams some of the GMGI catalysts are quite large opportunities in scale. Take Brazil - a single gaming license is a 6 year license to operate 3 brands across the entire country. Brazil is already #1 in LatAm & #3 globally in online gaming rev, closing in on #1 UK, & #2 USA. Meridianbet already has a B2B footprint in Brazil and is active in community impact programs.
As popular as American Football is here in the USA, the sport of soccer/football dominates globally. Worldwide 56% of sports spectators watch soccer/football while only 11% watch American football. Leading the spectators, a full 81% of Brazil players watch or wager on soccer/football. To give an example of Brazils potential player market consider if sportsbetting/igaming is legal in majority of USA, population is 345 million - 106 million ( say 10-13 dont legalize ) = 239 mil x 25% ( est # of players that gamble online in last 12 mo ) = 60 mil players. Now consider Brazil population is 212 million x 46% ( est % of players that gamble online in last 12 months ) = 97 mil players. Rough numbers and I know only a handful of companies get the majority of the business but that is a much bigger single license opportunity and the kicker is a single tax rate of 15% vs as high as 50% is some US states like NY.
Meridianbet, the oldest of all the GMGI companies has been growing and profitable 24 years straight - other than the Covid years. Covid actually benefitted Meridianbet as it forced them to shift from retail “bet shops” to a greater online presence. Now they are shifting back and using those old accounts to their advantage.
Meridianbet has a successful repeatable business model that entails first entering via test B2B and expanding to B2C once profitability is ensured. They simply will not enter or operate in a market they loose money. They now operate over 800 betshop franchises. They do not have a hug profit margin but provide the data as well as a revenue channel for their other products/services as well as great brand marketing and exposure.
The future of online gaming companies is turn-key omni-channel solutions. Companies do not have the financial resources or tech/AI to do it all themselves and depend on outsourcing. GMGI now has a top white-label product that can be branded with any company logo/name that is either going from brick and mortar to online or simply starting a new online casino/sportsbook.
GMGI has the pieces to make them one of the most flexible and secure packages that includes the tech, content, training, cybersecurity, regulation compliance, marketing, etc
GMGI has another advantage. Synergistic companies that operate is competing regions now offer cross-marketing as well as the expertise in that geographic region to succeed. This information/data entails:
*Customer demographics
*Customer game and sport preferences
*Targeted market as they have all their data
*Customer behavior patterns and cost of acquisition
*Customer spending history
*Government specific regulation compliance issues
*Government specific taxation regulations
*Language and currency challenges
*Marketing preferencies
Typically each company needs to pay for or consult for:
“Content Localization” and “Cultural Relevance”
This is because different content must be outsourced, different tech must be integrated to produce line bets, different AI modules and software must be added and integrated for different languages, software but integrate different currencies, cultural preferences, vocabularies, language dialects and many contextual nuances of each market. Asia Pacific is very different than South America. Several GMGI companies have operated in completely different regions and this familiarity with the region, consumers, cybersecurity and government gaming regulations and taxation rates is a huge advantage.
Studies show these services need to be outsourced by the majority of companies for success. Relying on multi-lingual customer service has been shown to have horrible results.
Translation is a major need. Translators can be very good but lack variations needed for mother tongue variations like Latin American Spanish or Chinese Malaysian.
Typical customer service translators are not familiar with sports, crypto, casino or Igaming terminology and variations in various languages.
Marketing and media content need “Cultural relevance” to target specific locations and populations with appropriate words, phrases, gestures, and even colors.
Cultural Marketing Example using a color:
China - Red = Good fortune
Middle East - Red = Evil
-Communication is huge - Players need to UNDERSTAND to trust.
- Cyber security is huge
- Ease of fund movement is huge
- Sign up and access needs to be easy
- Community impact and involvement is huge
Attention to all these provides a much better conversion rate, higher profit per player and much longer player lifespan.
$DKNG $PENN $GAMB $EVO @GMGI_Official @StudiosExpanse@meridianbet_ofc
$FLUT
GAMB institutional ownership.
@Schito_74@uboat159 Agreed, the stock isn’t reflecting the company’s strong growth—yet. Feels like an opportunity for those who see the long-term potential
The Future of Gaming: AI, Trends & $GMGI 100% Potential Upside! Interview with @GMGI_Official - #PaidPartnership with Golden Matrix Group https://t.co/mcyMKTR8lB
Sometimes, I stop and remind myself how lucky I am to live in #Lincoln. From the stunning #cathedral watching over the city to the historic streets that tell stories of the past, there’s something special about this place.
#LincolnLights#VisitLincoln
https://t.co/PQjznHjwbZ
@cdntradegrljenn $GMGI without question. Founder led, 24 year old company with several subsidiaries working synergistically with one another. Growing quarter after quarter, year over year! Check them out!
Strength in numbers: Meridianbet & @GMGI_Official CEOs talk shop on profitability, smart growth, and tech edge.
https://t.co/nx36X8XoV3
Here is why our laser focus on fundamentals sets us apart.
Many thanks @G_Insider for the insightful discussion
6am local time (4am UK time):
I decided to start the day with a horseback ride down Tagaki beach, Kos to watch the sunrise. Quite possibly one of the best moments of my life.
https://t.co/HyDKjaRxvp